
Life Insurance for Loggers
Life Insurance for Loggers
Jason Stolz CLTC, CRPC, DIA, CAA
Logging stands at the top of every occupational fatality ranking the Bureau of Labor Statistics and NIOSH produce — and has occupied that position consistently for decades. BLS Census of Fatal Occupational Injuries data documents the logging industry’s fatal injury rate at approximately 111 deaths per 100,000 full-time equivalent workers — a figure that is more than 30 times the overall U.S. worker fatality rate, and nearly double the rate of the second most dangerous occupation. OSHA has specifically described logging as the most dangerous occupation in the United States. The hazards that produce this fatality rate are not abstract: falling trees and limbs, unpredictable terrain, high-powered chainsaws and logging equipment, remote worksites where emergency medical response may be hours away, and the physical demands of moving timber through conditions that rarely cooperate with plans. Life insurance for loggers exists — and for most loggers in good health, meaningful coverage is genuinely obtainable — but navigating the underwriting landscape for one of the most hazard-rated occupations in the American economy requires specific knowledge of which carriers evaluate logging work most favorably, how job duties within the logging profession translate into underwriting outcomes that differ dramatically between roles, and what policy structures produce the most complete and most affordable protection for logging workers and their families.
At Diversified Insurance Brokers, Jason Stolz, CLTC, CRPC, DIA, CAA works with professional loggers, logging equipment operators, contract timber fallers, choker setters, and logging business owners to identify life insurance coverage that fits the occupation, fits the health profile, and fits the budget. The life insurance planning conversation for a logger is fundamentally different from the conversation for a schoolteacher or an accountant — and it requires an advisor who understands the underwriting mechanics of high-risk life insurance well enough to place the application with the right carrier before the wrong carrier generates a rated offer or a decline that complicates all subsequent shopping.
See Real-Term Rates Side by Side
Life Insurance Quoter
How Life Insurance Underwriters Evaluate Logging — And Why Your Specific Role Matters More Than Your Job Title
| Logger Role / Duty Type | Primary Hazard Exposure | Typical Underwriting Outcome | Coverage Availability |
|---|---|---|---|
| Timber faller / hand faller | Directly operates chainsaw to fell standing timber; highest direct exposure to struck-by falling trees and limbs; requires precise directional felling in unpredictable conditions; highest-hazard role in the logging profession | Table rating (typically Table 2–4 range, adding approximately 50–100% to standard premium) or flat extra charge of approximately $2.50 to $5.00 per $1,000 of face amount; varies significantly by carrier and health profile | Available at most carriers for healthy applicants — outright decline is uncommon for fallers with clean health history; some carriers decline; independent broker comparison essential |
| Choker setter | Attaches cables or chains to felled logs for extraction by skidder or helicopter; works in active logging zones with moving timber and equipment; struck-by and entanglement hazards | Table rating or moderate flat extra; generally somewhat less penalized than hand fallers because direct chainsaw operation is absent; carrier variation significant | Available; independent broker comparison reveals carriers with more favorable choker-setter guidelines |
| Skidder / forwarder operator | Operates heavy equipment to drag or carry logs from cut site to landing; rollover risk on steep terrain; equipment hazards; generally does not use chainsaw directly in production role | Table rating at lower end or moderate flat extra; machine operation with cab protection viewed more favorably than hand felling or ground-based choker work | Available; multiple carriers will write; premium impact is real but manageable for healthy applicants |
| Log truck driver / hauler | Transports logs from landing to mill on public roads; MVR-rated rather than purely occupation-rated; truck driving hazards rather than direct logging hazards | Treated as a transportation occupation rather than a logging occupation by most carriers; standard or near-standard rates for healthy drivers with clean MVR; logging-specific premium surcharge typically does not apply | Generally available at favorable rates for healthy drivers; clean driving record is the key underwriting variable |
| Logging foreman / supervisor | Manages crew operations; may spend time in active logging zone but typically not performing hand felling; administrative and supervisory component reduces direct hazard exposure | Outcome depends heavily on actual described duties — supervisors who certify they do not personally operate chainsaws or work directly in active felling zones may receive more favorable treatment | Available; accurate duty description in the application is critical; favorable outcome more likely than for ground production workers |
| Logging company owner (management only) | Owns and manages a logging operation but does not personally perform production logging work; office-based ownership and business management role | Standard rates available if duties are accurately documented as management-only; the logging industry affiliation does not penalize the application if no personal logging work is performed | Standard rates available with accurate duty description; documenting management-only status is the key underwriting variable |
The table establishes the most important underwriting reality for loggers seeking life insurance: the job title “logger” is not the underwriting determination — the specific duties performed daily are. A timber faller who works directly with a chainsaw felling standing timber faces a fundamentally different underwriting evaluation than a logging foreman who manages crew safety from a supervisory position, and both face different treatment than a log truck driver whose occupational risk profile is that of a transportation worker rather than a production logger. Understanding precisely how to describe occupational duties on a life insurance application — and which carriers evaluate those duties most favorably for each specific role — is the foundational planning work that determines whether a logger receives a rated offer, a standard offer, or a decline. Life insurance for high-risk occupations and the best high-risk life insurance companies provide the broader framework for understanding how this carrier variation operates across the spectrum of hazardous occupations.
Table Ratings and Flat Extras — The Underwriting Mechanics Loggers Encounter
Most loggers in good health who apply for life insurance do not receive outright declines — they receive rated offers. Understanding the two mechanisms through which carriers price the occupational risk of logging work is essential for evaluating any offer received and for knowing whether the carrier producing that offer is providing the most competitive available terms or simply applying the most conservative guidelines in the market.
A table rating is a percentage surcharge applied to the standard premium. The table system typically runs from Table 1 through Table 8 (or Table A through Table H at some carriers), with each table step adding approximately 25 percent to the base standard premium. A logger receiving a Table 2 rating pays approximately 50 percent more than the standard rate for their age and health class; a Table 4 rating produces a premium approximately 100 percent above standard. For production loggers — particularly hand fallers — table ratings in the Table 2 to Table 4 range are not uncommon at carriers who use the table system for occupational risk pricing. The exact table assigned varies significantly between carriers for the identical applicant and the identical occupational duties, which is why comparing offers across multiple carriers produces materially different premium outcomes for the same logger.
A flat extra is a different pricing mechanism — a fixed dollar charge per $1,000 of death benefit face amount, added to the base premium regardless of the standard rate calculation. Flat extras for logging work typically range from approximately $2.50 to $5.00 per $1,000 of face amount annually, depending on the carrier’s guidelines and the specific duties involved. On a $500,000 policy, a flat extra of $3.00 per $1,000 adds $1,500 per year to the annual premium — a meaningful surcharge, but one that produces affordable absolute dollar premiums for a working logger who needs that face amount to protect family financial obligations. Some flat extras are permanent for the duration of the occupation; some carriers apply a temporary flat extra that can be removed if the insured leaves logging work for a less hazardous occupation.
The carrier variation in how these mechanisms are applied to logging occupations is the most financially significant fact in the logger life insurance market. One carrier may apply a Table 4 rating to a hand faller; another may apply a Table 2 with no flat extra; a third may apply a flat extra with no table rating at a lower total cost. The same logger receiving three different offers from three different carriers may find a premium difference of several thousand dollars per year for the same face amount and benefit period — a difference that only independent broker comparison reveals. Prescreening a life insurance application before submission identifies the most favorable carrier before any formal application creates a record in the MIB database — a particularly important step for loggers, since a rated offer or decline from the wrong carrier can complicate subsequent applications at carriers that would have offered better terms.
What Underwriters Ask About Logging Duties — And How to Answer Accurately
When a logger applies for life insurance at a carrier that asks occupational questions in the underwriting process — which all carriers evaluating potential occupational hazard do — the application or an accompanying occupational questionnaire will ask specific duty questions that determine the hazard classification assigned. The questions typically cover: whether the applicant personally operates chainsaws or power saws; whether the work involves hand felling of standing timber or operation of mechanized felling equipment; the percentage of work time spent in active timber-cutting zones versus in equipment cabs or supervisory roles; whether the applicant works in helicopter logging operations (which some carriers view as an additional aviation-related hazard); and the geographic terrain and conditions in which the work is performed.
Accurate and complete answers to these questions are both legally required and strategically critical. An understatement of actual duties that produces a standard offer, followed by a claim arising from the actual hazardous duties, creates a material misrepresentation problem that can void the policy at claim time — the worst possible outcome for the family the policy was purchased to protect. An overstatement of duties — describing supervisory or management work in terms that suggest active production logging when none occurs — unnecessarily triggers hazard pricing that the applicant’s actual role does not warrant. The accurate, specific description of actual daily duties is the foundation of an accurate underwriting evaluation and an appropriate premium outcome. Working with an independent life insurance broker who understands logging underwriting ensures that the occupational description in the application is framed accurately, completely, and in the terms that give the underwriter the clearest possible picture of the actual hazard exposure the applicant’s specific role creates.
Prior Declines and Navigating the High-Risk Logger Market
A logger who has previously applied for life insurance at a captive or single-carrier agent and received a decline or a heavily rated offer is in a more complicated position than a first-time applicant — but still not in a position where coverage is unavailable. The MIB database records inquiries and underwriting information shared between member carriers, meaning a prior decline at one carrier may be visible to underwriters at subsequent carriers. This makes strategic application sequencing critical for loggers who have been declined or who received terms they found unacceptable. Life insurance with a prior decline is a navigable situation — but it requires working with a broker who can identify which carriers have more favorable logging underwriting guidelines and sequence the application to avoid compounding a difficult underwriting history with additional adverse records.
What to do if you’ve been denied life insurance as a logger begins with not reapplying at the same carrier type that declined the first application. A captive agent’s single-carrier decline does not mean the market has rejected the application — it means that carrier’s underwriting guidelines produce a decline for that applicant profile. A different carrier with different logging underwriting guidelines may produce a standard offer, a Table 2 rating, or a flat extra that brings meaningful coverage within a reasonable budget. The independent broker function in the high-risk life insurance market is specifically to identify which carrier among the dozens offering life insurance has the most favorable current guidelines for any specific logging role and health profile — a function that requires maintaining current knowledge of each carrier’s underwriting position rather than representing only one company’s guidelines.
How Much Life Insurance Does a Logger Need?
The life insurance coverage need for a logger is calculated the same way it is for any working adult with financial dependents — by identifying the household’s financial obligations that the logger’s income currently funds and that would need to be replaced or retired if the logger died. Income replacement for the years between the logger’s death and when dependents can become financially self-sufficient is the primary component. Outstanding mortgage or land debt, vehicle and equipment obligations, children’s educational costs, and final expenses are the other components that a complete life insurance needs analysis accounts for. For logging business owners who employ others and carry business obligations, the business protection dimension — life insurance for business owners — adds an additional layer that personal income replacement coverage alone does not address.
The cost of the coverage needed is a function of the logger’s age, health profile, face amount, benefit period, policy type, and the flat extra or table rating the carrier applies to the occupational risk. How much life insurance costs for a logger in good health varies enough between carriers and between logging roles that a quoted premium from a single source is not a reliable market price — it is one carrier’s number. A healthy logger in their thirties with a flat extra of $3.00 per $1,000 who needs $500,000 of 20-year term coverage pays a meaningfully different total premium at the carrier with the most favorable underwriting guidelines for their specific role than at the carrier with the most conservative guidelines, making carrier comparison the most financially important step in the process.
Policy Types Available to Loggers
Term life insurance is the most common policy type for loggers who need maximum face amount at the lowest available annual cost during their working and family-building years. Term policies for loggers are underwritten to reflect the occupational risk through the table rating or flat extra mechanism — but the underlying term structure remains the most affordable way to deliver a large death benefit for a defined period. A logger who purchases $750,000 of 20-year term to cover mortgage, income replacement, and family obligations during the years of active logging work has the most financially efficient coverage structure for the primary need.
Permanent life insurance is available to loggers and provides lifetime coverage that does not expire when a term policy ends. Permanent coverage is appropriate for loggers with permanent family financial protection needs, estate planning objectives, or business continuation purposes that extend beyond the term period. No-exam life insurance is an option for loggers whose health profile makes the traditional fully underwritten process uncertain, or who prefer faster approval without a medical examination — though face amount ceilings are typically lower on no-exam products and the pricing reflects the reduced underwriting information available to the carrier. Life insurance with living benefits — policies that include chronic, critical, or terminal illness acceleration provisions — is available to loggers who want their death benefit to serve double duty as a financial resource if a serious illness occurs during the policy period. The most important step before selecting a policy type is determining which carriers produce the most favorable occupational underwriting outcome for the specific logging role — because the carrier with the best underwriting for term may differ from the carrier best positioned for permanent coverage.
Get Your Logger Life Insurance Review
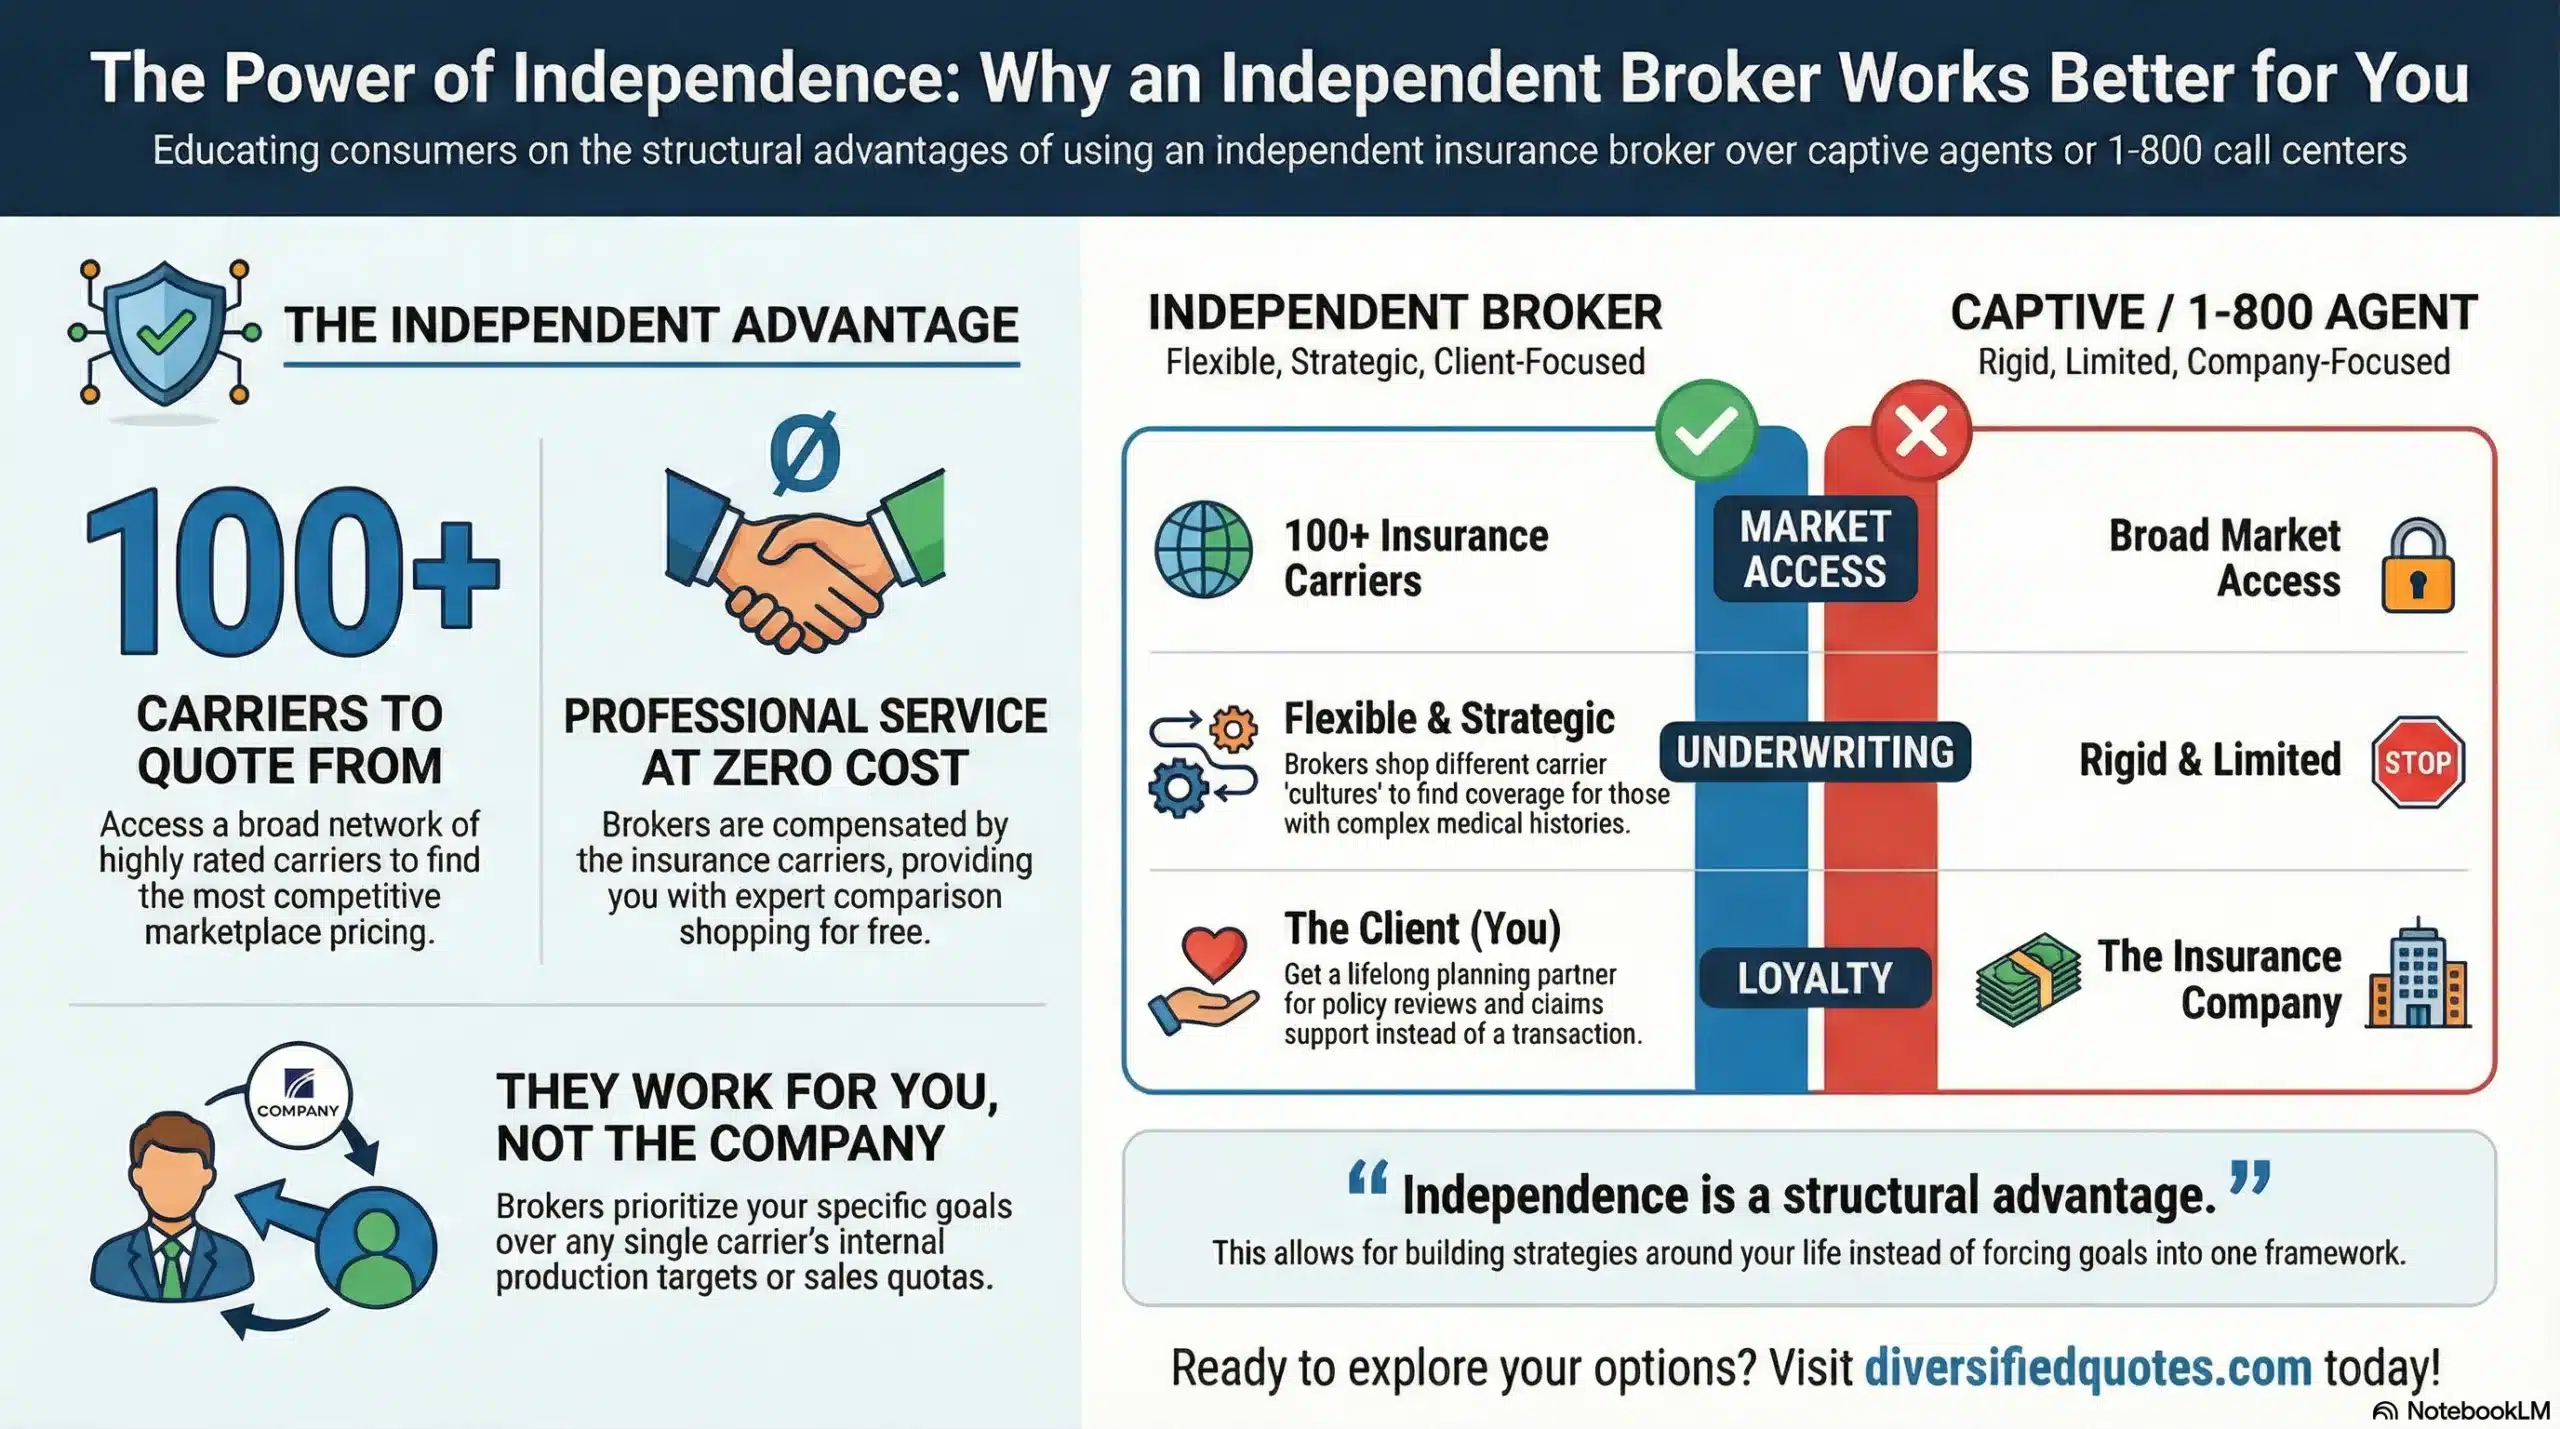
We compare underwriting guidelines across 100+ carriers and identify the company and policy structure that produces the most favorable terms for your specific logging role and health profile.
Request Logger Life Insurance OptionsCompare Term Life Insurance Lengths
Explore different term periods to find coverage that best matches your timeline and budget.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
FAQs: Life Insurance for Loggers
Can loggers actually get life insurance, or do most carriers decline the occupation?
Most loggers in good health can obtain life insurance — outright declines are not the norm for healthy logging applicants, though they do occur at some carriers for the highest-hazard roles. The logging industry’s documented fatality rate as the most dangerous occupation in the United States by BLS data means carriers take the occupational risk seriously and price it accordingly — but pricing through table ratings and flat extras is fundamentally different from an inability to obtain coverage. The practical answer for most loggers is not whether coverage is available but which carrier offers the most favorable available terms for the specific logging role and health profile.
The carrier variation in logging underwriting guidelines is substantial. Some carriers are significantly more favorable to logging occupations than others, and the premium difference between the most favorable and least favorable carrier for the identical applicant can be dramatic. A logger who applies at a single captive carrier that views logging conservatively may receive a decline or a heavily rated offer that creates the impression the market has rejected them — when in reality, an independent broker placing the application at the most favorable carrier in the market would have produced an approvable offer at a substantially lower premium. Life insurance after a prior decline for loggers is navigable through independent broker comparison at carriers with more favorable logging guidelines. The key is not reapplying at the same carrier type that declined the first application.
What is a flat extra and how does it affect my life insurance premium as a logger?
A flat extra is an additional dollar charge per $1,000 of death benefit face amount, added to the base premium calculation to compensate the carrier for elevated occupational risk. For logging work, flat extras typically range from approximately $2.50 to $5.00 per $1,000 of face amount annually, depending on the carrier’s guidelines and the specific duties involved. The flat extra mechanism means the total additional cost scales with the face amount rather than with age or health class — a $3.00 per $1,000 flat extra on a $250,000 policy adds $750 per year, while the same flat extra on a $500,000 policy adds $1,500 per year.
The flat extra mechanism differs from a table rating in that it is typically a fixed dollar surcharge rather than a percentage increase. For younger loggers with low base premiums, a flat extra can be proportionally large relative to the base premium; for older loggers with higher base premiums, the flat extra represents a smaller percentage addition. Some carriers apply flat extras as permanent occupational charges; others treat the logging flat extra as removable if the insured leaves active logging work for a less hazardous occupation — a provision worth asking about specifically, since a logger who plans to transition to supervisory, management, or a different career in future years has the option of having the flat extra removed when the occupational risk changes. The flat extra at one carrier may be meaningfully lower than at another for the identical applicant — making carrier comparison the most financially important step for any logger seeking to minimize the premium impact of occupational surcharging.
Does it matter whether I’m a hand faller, a skidder operator, or a logging supervisor?
Yes — significantly. Life insurance underwriters evaluate the specific duties performed in the logging occupation rather than the job title alone, and the duty distinctions between roles in the logging profession produce meaningfully different underwriting outcomes. A timber faller who personally operates a chainsaw to fell standing trees faces the most hazardous direct exposure in the logging profession — operating a high-powered cutting tool while in the strike zone of multi-ton falling timber — and receives the most penalized underwriting treatment. A skidder operator working from an enclosed cab to extract already-felled timber faces real occupational hazard but not the same direct struck-by exposure of hand felling, and typically receives somewhat more favorable terms. A logging supervisor or foreman who manages crew operations but does not personally perform active timber-cutting work may receive still more favorable treatment if the duties are accurately described and documented.
The practical implication is that the duty description on the life insurance application is one of the most important documents in the underwriting file for a logger. Accurate, specific, and complete description of actual daily duties — what percentage of time is spent in each role, whether chainsaw operation is personally performed, whether active felling zones are entered — gives the underwriter the information needed to apply the guidelines appropriate to the actual hazard rather than the most conservative guidelines for the entire logging occupation. A prescreening conversation with an independent broker before the formal application allows the duty description to be reviewed and presented in the most accurate and complete terms before the formal underwriting evaluation begins.
I own a logging company but don’t personally do production logging work — will I be rated for the occupation?
Generally no — if your actual duties are accurately described and documented as management and business ownership rather than active production logging. Life insurance underwriters evaluate the risk the applicant personally faces from their actual occupational activities, not the risk of the industry in which their business operates. A logging company owner who manages the business, handles contracts, oversees operations, and employs crew but does not personally operate chainsaws, enter active felling zones, or perform production logging work is evaluated as a business manager — not as a production logger — at most carriers. The standard or preferred rates available to a healthy business manager apply, without the occupational surcharge that active logging production work generates.
The critical caveat is accurate and honest duty description. A logging company owner who describes themselves as management-only but who regularly participates in active timber felling or choker setting has described their occupation inaccurately — a material misrepresentation that can void the policy at claim time if the actual duties are inconsistent with what was represented on the application. The correct approach is to describe actual duties honestly and completely. If the duties genuinely are management-only, the standard rate applies. If the owner performs some production logging work alongside management, the application should accurately reflect the portion of time spent in active logging operations so the underwriter can evaluate the actual risk profile rather than an incomplete picture of it.
How much life insurance can a logger get and what face amounts are typically available?
Face amount availability for loggers in good health is generally not the primary limiting factor — most carriers that will write logging risk will issue face amounts appropriate to the applicant’s demonstrated need and documented income, subject to the carrier’s financial underwriting guidelines. A logger with documented income who needs $500,000 or $1,000,000 of coverage to protect family financial obligations, a mortgage, and business interests can typically access those face amounts at carriers with favorable logging underwriting guidelines, assuming the health profile supports standard or rated issuance. The occupational surcharge — table rating or flat extra — increases the cost of the coverage but does not typically reduce the face amount available for healthy applicants.
Financial underwriting for higher face amounts — generally above $500,000 to $1,000,000 depending on the carrier — requires documentation of the financial need the death benefit is intended to address. Income replacement, mortgage balances, business loan obligations, and dependent financial needs are the standard financial underwriting documentation that high-face-amount applications require regardless of occupation. How much life insurance a logger actually needs is determined by the household’s specific financial obligations — not by the occupation — and those obligations should drive the face amount selected rather than an arbitrary number chosen without reference to the actual financial exposure. An independent broker conversation that works through the actual financial needs produces the face amount that provides genuine protection rather than undercoverage or overcoverage relative to the household’s actual situation.
Will my life insurance rate go down if I leave logging for a less dangerous job?
For loggers who hold policies with flat extras that were applied specifically due to occupational risk, some carriers allow the flat extra to be removed if the insured changes to a less hazardous occupation — potentially reducing the annual premium meaningfully. Whether this option is available depends on the specific carrier’s policy provisions and the terms of the flat extra as written. Some flat extras are permanent for the duration of the policy; others are explicitly written as removable upon a documented change to a safer occupational role. Asking specifically about flat extra removability before selecting a carrier is worth doing if there is any possibility of an occupational change in the future.
For table ratings applied as percentage surcharges, the situation is similar — some carriers allow a reconsideration of the table rating upon documented change of occupation, while others maintain the table rating for the original policy term. A logger who anticipates transitioning to supervisory, management, or a non-logging career within the policy period has an additional reason to work with an independent broker who understands each carrier’s policy provisions regarding occupational rating review. A second opinion on your life insurance situation is also worth seeking if you currently hold a policy with an occupational surcharge and your duties have changed — you may be paying for a rated classification that no longer reflects your actual occupational risk, and a new policy at standard rates could produce significant premium savings over the remaining years of coverage need.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for High Risk Occupations & Activities — covering pilots, construction workers, extreme sports, scuba diving & more from 100+ carriers.
Last Reviewed: June 15, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
