Life Insurance for People with Organ Transplants
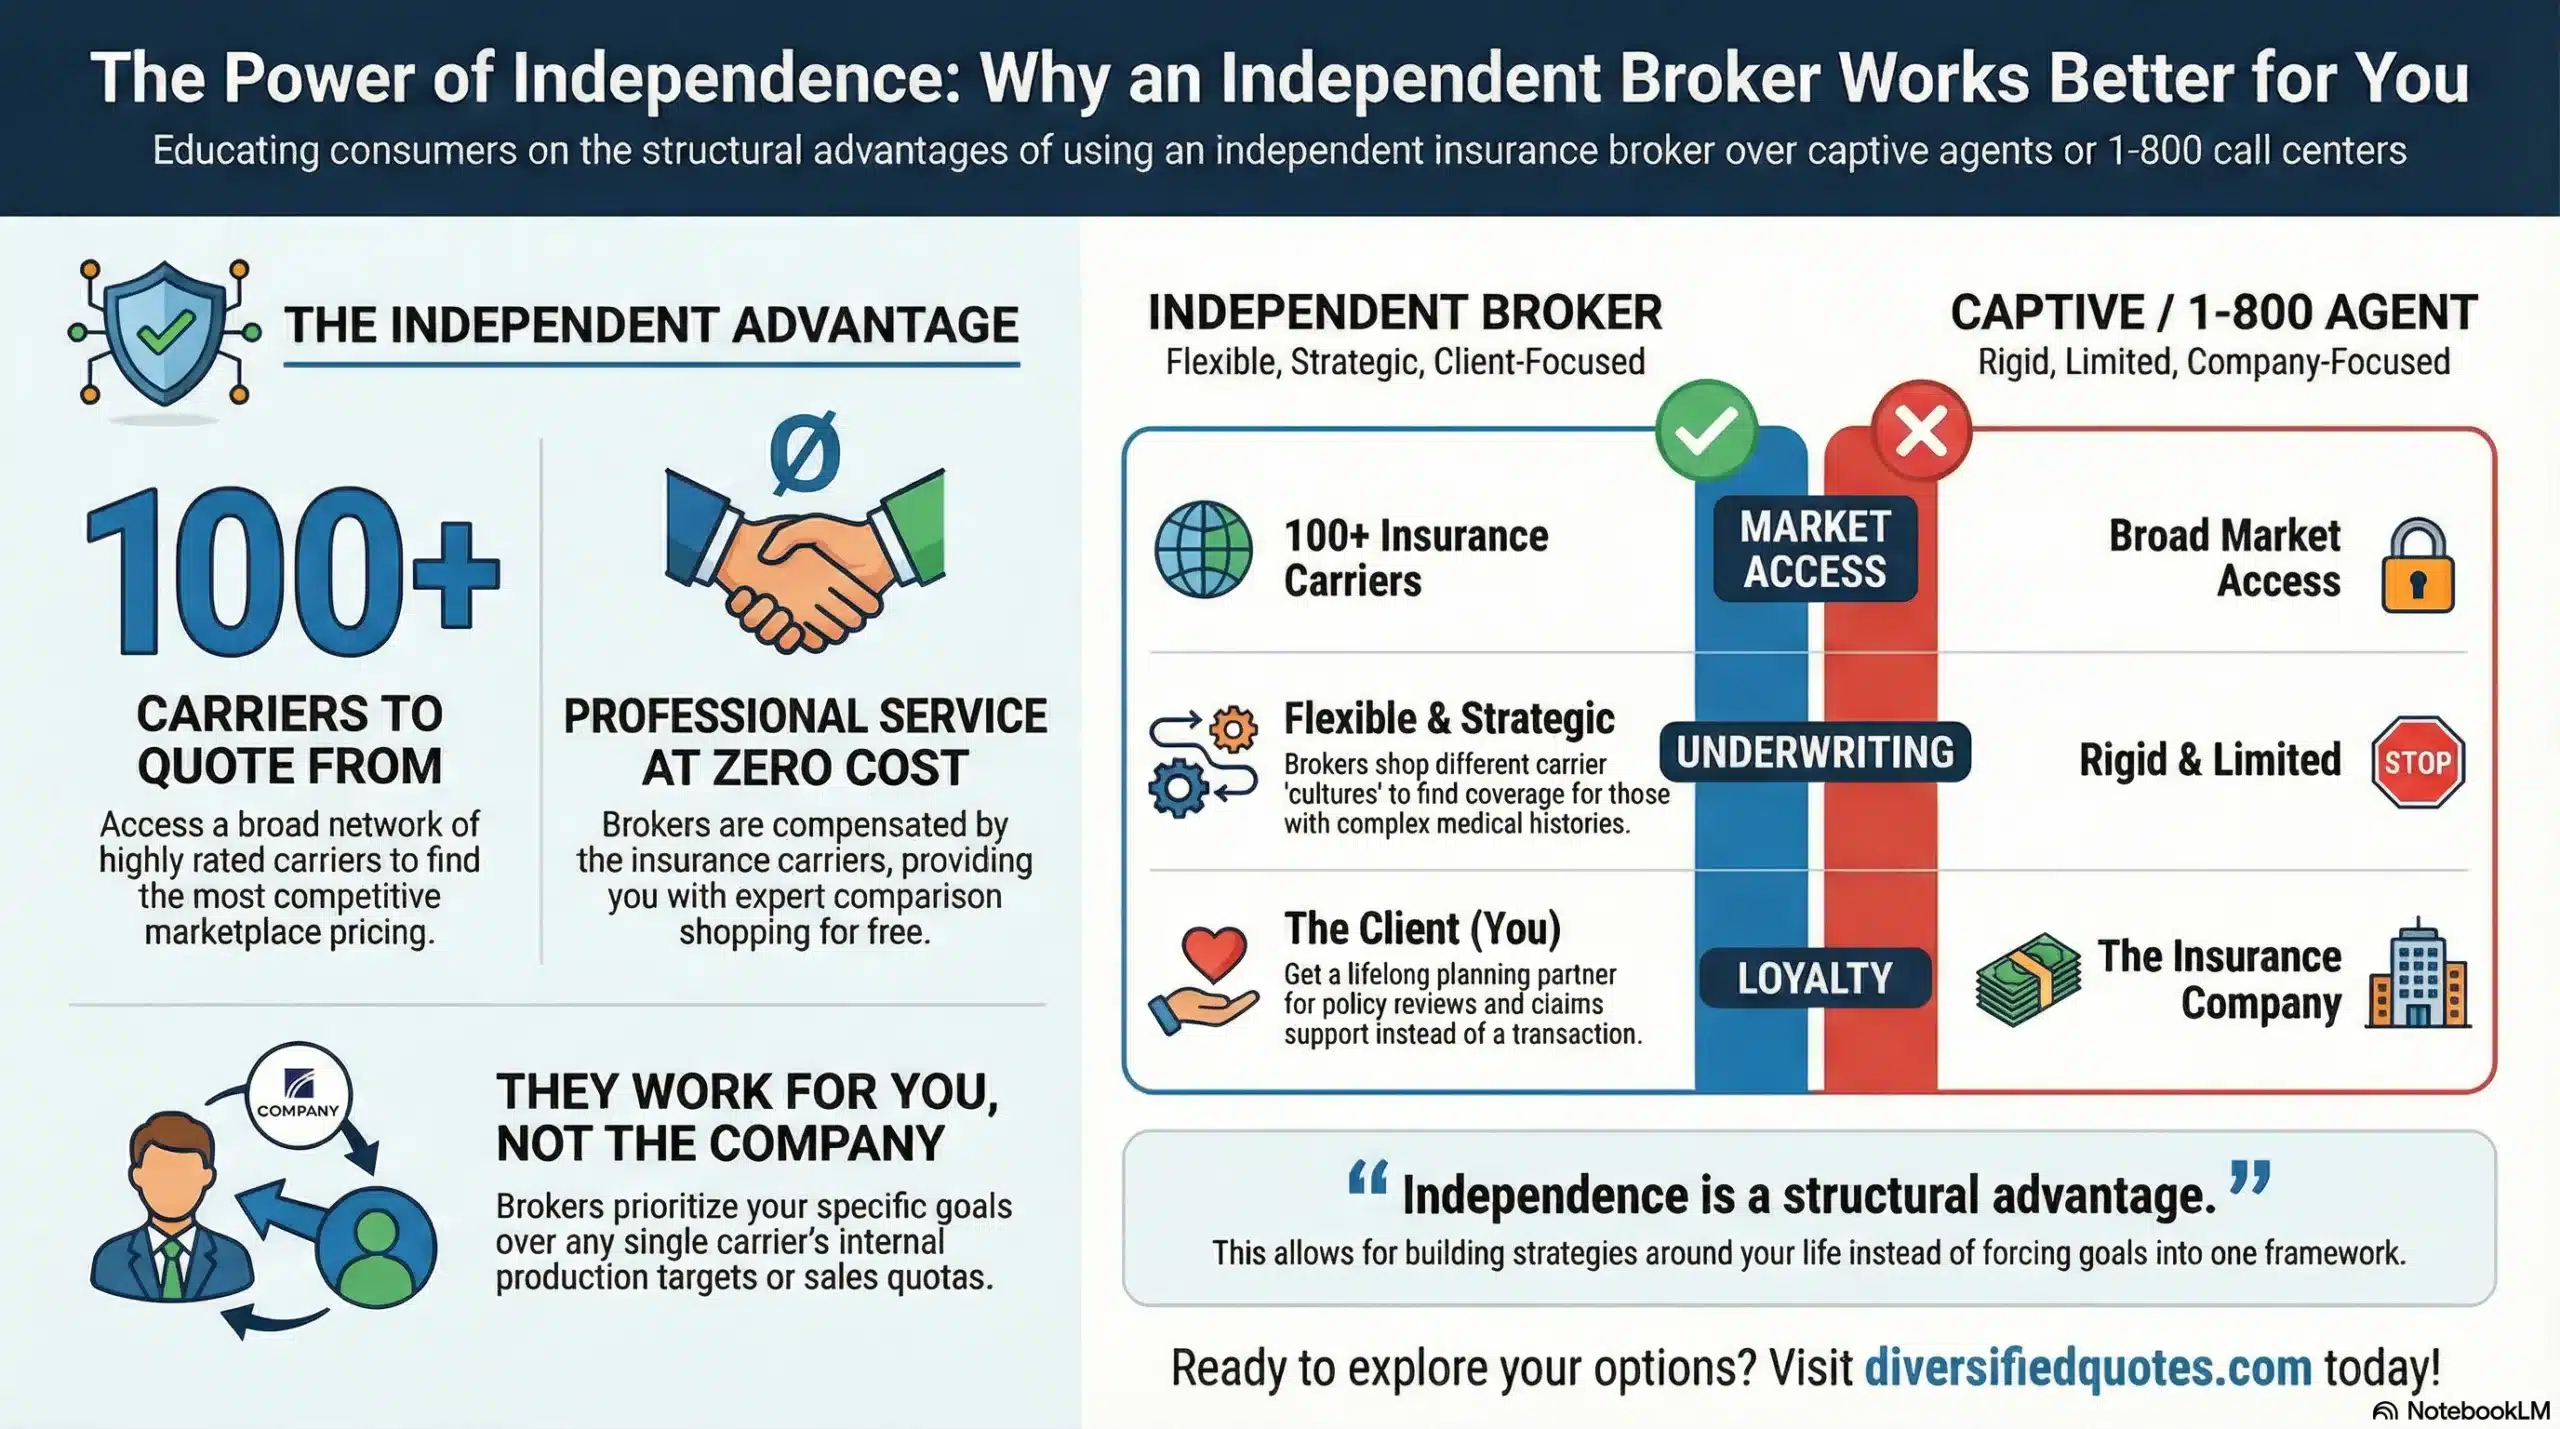
As an Independent Life Insurance Broker, we compare rates across 100+ carriers and prescreen every application before submission.
Life Insurance for People with Organ Transplants
Jason Stolz CLTC, CRPC, DIA, CAA
Life insurance for people with organ transplants is available — and for many transplant recipients who approach the application process correctly, it produces better outcomes than most people expect after being told by one carrier that coverage was not possible. The misunderstanding begins with how transplant underwriting actually works. Insurance carriers do not evaluate transplant history as a binary “approved or declined” fact about a person’s past. They evaluate the complete picture of what your health looks like today: how long ago the transplant occurred, how stable graft function has been since, whether rejection episodes occurred and resolved, how well the underlying condition that drove the transplant is controlled, how consistently you are followed by your transplant team, and whether your overall health profile — immunosuppressant regimen, comorbid conditions, infection history, current lab trends — suggests durable stability or ongoing medical complexity. When that complete picture is organized, clearly presented, and matched to carriers whose underwriting guidelines are calibrated for transplant history, many applicants who were previously declined find that life insurance for people with organ transplants becomes achievable.
At Diversified Insurance Brokers, Chief Underwriter Jason Stolz, CLTC, CRPC, DIA, CAA — with more than two decades of experience in high-risk life insurance underwriting — specializes in positioning complex medical histories for the most favorable possible outcome. Life insurance for people with organ transplants requires carrier selection as a strategy, case presentation as a discipline, and a thorough pre-screening process that identifies which pathways are realistic before any application is submitted. Applying blind to the wrong carrier — one that does not review transplant cases on a case-by-case basis — creates an avoidable decline that becomes part of your MIB history and complicates future applications. Our resource on high-risk life insurance services covers the complete high-risk underwriting framework, and our resource on what to do if you’ve been denied life insurance covers the next steps for transplant recipients who have already received a decline at another carrier.
Compare Life Insurance Rates — Including High-Risk Options
Life Insurance Quoter
How Organ Type Affects Life Insurance Underwriting — A Side-by-Side Overview
| Organ Type | Approval Likelihood (Traditional) | Typical Stability Window Carriers Want | Key Underwriting Factors | Best Initial Pathway |
|---|---|---|---|---|
| Kidney | Best among major organs — standard or rated coverage possible in stable long-term cases | Typically 2–5 years with stable function | Renal lab trends, blood pressure, diabetes control, rejection history, donor type (living vs deceased) | Traditional fully underwritten (case-by-case); simplified issue for appropriate cases |
| Liver | Possible with strong stability documentation; most carriers decline without review; select carriers consider table-rated cases | Typically 3+ years with consistent hepatology follow-up | Liver function lab trends, original transplant cause, alcohol history (if applicable), viral status, current monitoring | Narrative-driven traditional submission with select carriers; simplified issue as alternative |
| Heart | Conservative underwriting; traditional coverage challenging; possible in select long-term stable cases with strong cardiology record | Typically 5+ years; sustained stability with clean monitoring record | Functional status, cardiac monitoring, BP and lipid control, arrhythmia history, infection history, rejection episodes | Final expense or guaranteed issue foundational coverage; traditional pursuit with extended stability |
| Lung | Most challenging; majority of applicants declined for traditional; guaranteed issue typically the realistic starting point | Extended; even long-term stability often limits to graded or guaranteed issue | Pulmonary function trends, infection history (especially chronic rejection patterns), hospitalization frequency, follow-up consistency | Guaranteed issue or final expense; graded benefit as intermediate option |
| Pancreas / Combined (Kidney-Pancreas, Multi-Organ) | Complex; depends heavily on metabolic stability post-transplant and which organs are involved | Varies; metabolic improvement documentation critical | Overall metabolic profile stability, diabetes control (if applicable), multi-specialist follow-up record, complication patterns | Pre-screening essential before any application; pathway depends on dominant risk factor |
Compare Term Life Insurance Lengths
Explore different term periods to find coverage that best matches your timeline and budget.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions: Life Insurance for People With Organ Transplants
Can you get life insurance after an organ transplant?
Yes — life insurance for people with organ transplants is available, though the pathway and policy structure depend significantly on organ type, time since transplant, stability documentation, rejection history, and current health profile. Kidney transplant recipients with documented long-term stability have the most accessible traditional underwriting options. Liver transplant recipients with 3-plus years of clean hepatology records can find carriers willing to review on a case-by-case basis. Heart and lung transplant recipients face more conservative underwriting, and for many, guaranteed issue or final expense coverage represents the realistic starting point — with traditional coverage pursued as stability extends over time. No applicant should assume a prior decline is a permanent answer, as carrier selection and case presentation significantly affect outcomes.
Which organ transplant is easiest to insure?
Kidney transplants have the most accessible underwriting profile among major organ transplants. Kidney transplantation has the highest long-term success rates, the most established outcome data, and consistent lab markers (creatinine, GFR) that clearly demonstrate stability. Kidney transplant recipients with 2 to 5-plus years of stable follow-up and controlled comorbidities are most likely to qualify for fully underwritten term or permanent coverage with the right carrier. Liver transplants have a narrower market but meaningful options exist for stable long-term cases. Heart transplants require extended stability periods and face more conservative underwriting. Lung transplants are the most challenging, with most carriers declining traditional applications regardless of stability period.
How long after a transplant should I wait before applying for life insurance?
Most carriers require a minimum of 12 months post-transplant before they will review applications for traditional life insurance. During this initial period, guaranteed issue or final expense products can provide foundational coverage without a stability requirement. For fully underwritten traditional coverage, the meaningful review window typically opens between 2 and 5 years post-transplant depending on organ type — with kidney cases often accessible sooner and heart/lung cases requiring longer stability periods. Applying for traditional coverage before a meaningful stability window is established typically results in postpone or decline outcomes, which become part of the MIB record and can complicate future applications. Pre-screening through an independent broker before any formal submission is the best way to identify the right timing and carrier for your specific situation.
Does a rejection episode permanently disqualify me from life insurance?
No. A rejection episode does not automatically or permanently disqualify an applicant from life insurance for people with organ transplants. Underwriters evaluate rejection history with specific context: when the rejection occurred relative to today, how severe it was, how it was treated, how fully it resolved, and whether graft function has remained stable since. A single mild rejection episode in the first year post-transplant that resolved completely and has not recurred creates a very different underwriting picture than recent or recurrent severe rejection with ongoing instability. Clear documentation of rejection recovery and long-term subsequent stability is the strongest counterweight to rejection history in the underwriting file.
Will immunosuppressant medications hurt my life insurance application?
The presence of immunosuppressant therapy does not disqualify a transplant recipient from life insurance for people with organ transplants — it is expected and built into the underwriting framework for transplant cases. What underwriters evaluate is the nature of the regimen: whether it suggests stable maintenance versus ongoing management of complications, whether adherence is consistent, whether the medication list has been stable or has required frequent changes driven by complications, and whether the side effect profile (particularly infection susceptibility) is evident in the broader health history. A stable, consistently maintained immunosuppressant regimen with no significant side effects or complication patterns is a neutral to positive underwriting factor, not a disqualifying one.
What life insurance options are available if I’ve been declined before?
A prior decline at one carrier does not mean all options are exhausted for life insurance for people with organ transplants. Different carriers have different underwriting guidelines for transplant cases, and carriers that automatically decline may differ from those willing to review on a case-by-case basis. Additionally, different policy types — guaranteed issue, final expense, and graded benefit — are available without medical underwriting and remain accessible regardless of prior declines. Working with an independent high-risk broker who knows which carriers are most likely to review your specific organ type and stability profile is the most important step after any prior decline, because it prevents the cycle of blind applications to inappropriate carriers that generates additional decline history without productive results.
Can annuities serve as a life insurance alternative for transplant recipients?
Yes, in specific circumstances. Annuities are issued based primarily on the purchaser’s ability to fund the contract rather than on medical underwriting, making them accessible to individuals who face life insurance underwriting limitations. Certain annuity designs include death benefit provisions or beneficiary payout structures that can create a financial legacy for family members — a different mechanism than a traditional death benefit, but one that can still provide meaningful financial protection for beneficiaries. For transplant recipients who find traditional life insurance pricing prohibitive or for whom larger face amounts are not yet accessible through traditional underwriting, an annuity strategy alongside a foundational guaranteed issue life insurance policy can create a more complete family protection picture than either tool provides alone.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for Organ, Liver, Kidney & Infectious Disease — covering kidney disease, organ transplants, hepatitis, and HIV/AIDS underwriting from 100+ carriers.
Last Reviewed: September 28, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
