
Life Insurance for Pregnant Women
As an Independent Life Insurance Broker, we compare rates across 100+ carriers and prescreen every application before submission.
Life Insurance for Pregnant Women
Jason Stolz CLTC, CRPC, DIA, CAA
We place pregnant women in the Preferred Plus rate class — the single best rate class most carriers offer — on a routine, weekly basis. Not as a rare exception. As the normal, expected outcome for a healthy pregnant applicant with no complications. If you’ve put off applying for life insurance because you assumed pregnancy itself would work against you, that assumption is costing you time you don’t need to lose, and it’s based on a misunderstanding of how this is actually underwritten.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and pregnancy-related underwriting is a genuinely well-worn path in our office — one we can speak to directly from what we see happen, case after case, every week. As an independent broker working across dozens of carriers, we know exactly which specific factors actually matter for a pregnant applicant, and just as importantly, which ones don’t matter at all, regardless of what intuition might suggest.
Pregnant and wondering what it actually means for your life insurance application? Let’s talk.
Talk to a Life Insurance Specialist
| Factor | Does It Matter? | What Actually Gets Evaluated |
|---|---|---|
| Pre-pregnancy height and weight | Yes | Your baseline BMI before pregnancy, not your current pregnant weight |
| Normal, expected weight gain during pregnancy | No | Not penalized at all, as long as pre-pregnancy weight and current pregnant weight both fall in a normal range |
| Complications in the current pregnancy | Yes | Any diagnosed complication is reviewed on its own specific facts |
| Complications in a previous pregnancy | Yes | A genuine predictor of recurrence risk, reviewed alongside the current pregnancy |
| Planned natural birth | Yes | Favorable when planned; an emergency C-section signals an underlying complication and is evaluated differently |
| Gestational diabetes | Yes | Coverage remains available, but the file is underwritten more carefully |
| Which trimester you’re in when you apply | No | Not a factor at all — the underlying health picture is what matters, not the calendar |
Outcomes above reflect general, well-documented underwriting patterns and our own ongoing placement experience; they are not a quote or a guarantee, and actual results depend on the complete file and the specific carrier.
See Real-Term Rates Side by Side
Life Insurance Quoter
The Core Principle: Pregnancy Itself Is Not a Diagnosis
Pregnancy is a healthy, expected biological process, not a medical condition in the way underwriting typically treats a diagnosis. A healthy pregnant woman with no complications, otherwise good health, and a normal pre-pregnancy build is not a higher-risk applicant simply by virtue of being pregnant. This is the principle underneath every specific factor on this page, and it’s the reason we can say, plainly, that we place pregnant applicants in the top available rate class on a routine basis. The evaluation isn’t “is she pregnant” — it’s the same evaluation any applicant goes through, with a small number of pregnancy-specific facts added to the picture.
Why Pre-Pregnancy Weight Is What Gets Evaluated — Not Current Weight
This is the detail that surprises the most people, and it makes complete sense once you understand the reasoning. Medical guidance for a healthy pregnancy with a normal starting BMI generally recommends gaining somewhere in the range of 25 to 35 pounds. That weight gain is normal, expected, and medically healthy — it is not a signal of declining health the way unexplained weight gain might be evaluated outside of pregnancy. Because of this, underwriters look at your baseline, pre-pregnancy height and weight to assess your actual long-term health profile, rather than judging your current pregnant weight against the same standards used for a non-pregnant applicant.
In practice, this means a woman with a normal pre-pregnancy BMI who has gained a healthy, expected amount of weight during pregnancy is not penalized for that weight gain at all. The two figures that matter are whether her pre-pregnancy weight was in a normal range, and whether her current pregnant weight is consistent with a normal, healthy pregnancy for her stage — not whether the number on the scale today looks different than it did a year ago.
Why Previous Pregnancy Complications Matter So Much
A complication in a prior pregnancy isn’t just historical information — it’s one of the strongest known predictors of what might happen in a current or future pregnancy. Research on preeclampsia specifically has found that women who experienced it in a first pregnancy face a meaningfully elevated risk of experiencing it again in a subsequent one, and that a history of preeclampsia is also linked to a higher long-term risk of chronic hypertension and cardiovascular disease later in life, independent of pregnancy altogether. Gestational diabetes shows the same pattern: a prior occurrence is one of the strongest known risk factors for it happening again.
This is exactly why an underwriter reviewing a pregnancy-related application looks beyond just the pregnancy in progress — a clean history with no prior complications is a genuinely stronger, more predictive signal than a clean current pregnancy considered entirely on its own, and a documented history of a prior complication is worth addressing directly with real records rather than leaving as an open question.
Planned Natural Birth vs. Emergency C-Section
A planned, natural delivery with no anticipated complications is the favorable picture for underwriting purposes, and it’s worth being precise about why. The birth plan itself isn’t really what’s being evaluated — it’s what the birth plan tells you about the underlying pregnancy. A pregnancy proceeding without complications is generally expected to result in a natural delivery, so a planned natural birth is, in effect, a marker that nothing concerning has emerged.
An emergency C-section is evaluated differently specifically because it typically means something did emerge — fetal distress, a labor complication, or another issue that made a surgical delivery medically necessary partway through. It’s the underlying complication that matters to an underwriter, not the surgical procedure itself; the emergency C-section is simply the marker that reveals a complication occurred. This is a meaningfully different signal than an elective, planned C-section chosen in the absence of any complication, which doesn’t carry the same implication.
Have a specific pregnancy history and want to know exactly how it would be evaluated? Let’s look at the details together.
Get a Confidential Case Review
Gestational Diabetes: A Real Factor, Not a Disqualifier
Gestational diabetes affects roughly 5% to 9% of pregnancies, and it’s a genuine, medically meaningful factor — but it is explicitly not an automatic decline. Coverage remains available; the file simply gets a more careful, individualized look. What underwriters generally want to see includes when the diagnosis occurred during the pregnancy, whether it was controlled through diet alone or required medication or insulin, whether any additional complications developed alongside it, and critically, what happened after delivery: postpartum blood sugar testing showing a return to normal, and confirmation that elevated blood sugar didn’t persist beyond the first several weeks postpartum.
The reason gestational diabetes gets this level of attention is that it’s genuinely linked to more than just the pregnancy itself — it’s also associated with an increased long-term risk of type 2 diabetes for the mother later in life, which is exactly the kind of long-term health trajectory life insurance underwriting is built to assess. Many carriers want to see at least one normal postpartum test result, and some prefer a longer track record of stability, often in the range of a year or more, before offering their most favorable rate classes. A diet-controlled case with strong postpartum numbers and a healthy pre-pregnancy BMI is a genuinely strong file even with a gestational diabetes history on record.
Why Trimester Doesn’t Matter
This is a genuine myth worth clearing up directly: which trimester you happen to be in when you apply is not a meaningful underwriting factor. The actual factors that matter — pre-pregnancy BMI, complication history, birth plan, and gestational diabetes status — don’t fundamentally change based on the calendar. Waiting until later in a pregnancy to apply, or rushing to apply before a certain point, isn’t necessary based on trimester timing alone. What matters is whether the underlying health picture is clean, not when in the nine months you happen to submit an application.
A Track Record Worth Knowing About
We want to be direct about something rather than leave it as an abstract claim: placing pregnant applicants in the Preferred Plus rate class, the top tier most carriers offer, is a routine, weekly occurrence in our office, not an occasional exception we’re highlighting because it’s rare. This assumes, of course, that an applicant qualifies medically on every other front the way any applicant would — pregnancy on its own is not what determines the outcome. The point worth taking away is simple: being pregnant is not, by itself, a reason to expect a lower rate class or a more difficult application. For a healthy applicant with a clean history, it frequently isn’t a factor in the outcome at all.
Building the Strongest Possible File
A handful of specific pieces of information make the biggest difference in how a pregnancy-related application is evaluated. Your documented pre-pregnancy height and weight, ideally confirmed through a recent medical record rather than self-reported from memory. A summary from your OB confirming the current pregnancy is proceeding without complications, and a natural delivery is planned. Any history from a previous pregnancy, favorable or not, presented clearly and completely rather than left for an underwriter to discover independently. And if gestational diabetes is part of your history, whether it was diet-controlled, and your postpartum test results if delivery has already occurred. A complete, organized file along these lines gives an underwriter a genuinely clear picture, rather than one built on assumptions.
Realistic Rate Class Expectations
For a healthy applicant with a normal pre-pregnancy BMI, no complications in the current or any previous pregnancy, and a planned natural delivery, Preferred Plus, the top available rate class at most carriers, is a genuinely realistic and common outcome — not an exception to hope for. A history of gestational diabetes, particularly if diet-controlled with strong postpartum numbers, is still frequently placeable at a favorable rate, though possibly one rate class down from the very top tier. A more complicated history — an emergency C-section, a diagnosed complication like preeclampsia, or gestational diabetes requiring insulin — generally moves toward a more individualized review, and it’s worth understanding that a request for additional records or a short postponement is not the same thing as a decline. Our broader overview of how rate classes work and what actually drives your premium cover this system in more depth.
If a Decision Needs to Wait
In some cases, particularly where a real complication is present, a carrier may prefer to wait until after delivery and a return to normal health before finalizing an offer. This isn’t a decline — it’s simply a request for the picture to become clearer. If you’d rather not wait, coverage remains available in the meantime through simplified underwriting or guaranteed issue coverage, both available immediately regardless of where things currently stand, often used as a bridge while a fully underwritten application proceeds in parallel.
How We Help
We know exactly which pregnancy-related facts move an application toward the top rate class and which ones simply don’t matter, because we see this pattern play out every week, not occasionally. Before you apply anywhere, we’ll help you put together the specific documentation that makes a pregnancy-related file genuinely strong, and we’ll set realistic, honest expectations from the start rather than letting an outdated assumption about pregnancy and life insurance cost you time you don’t need to lose.
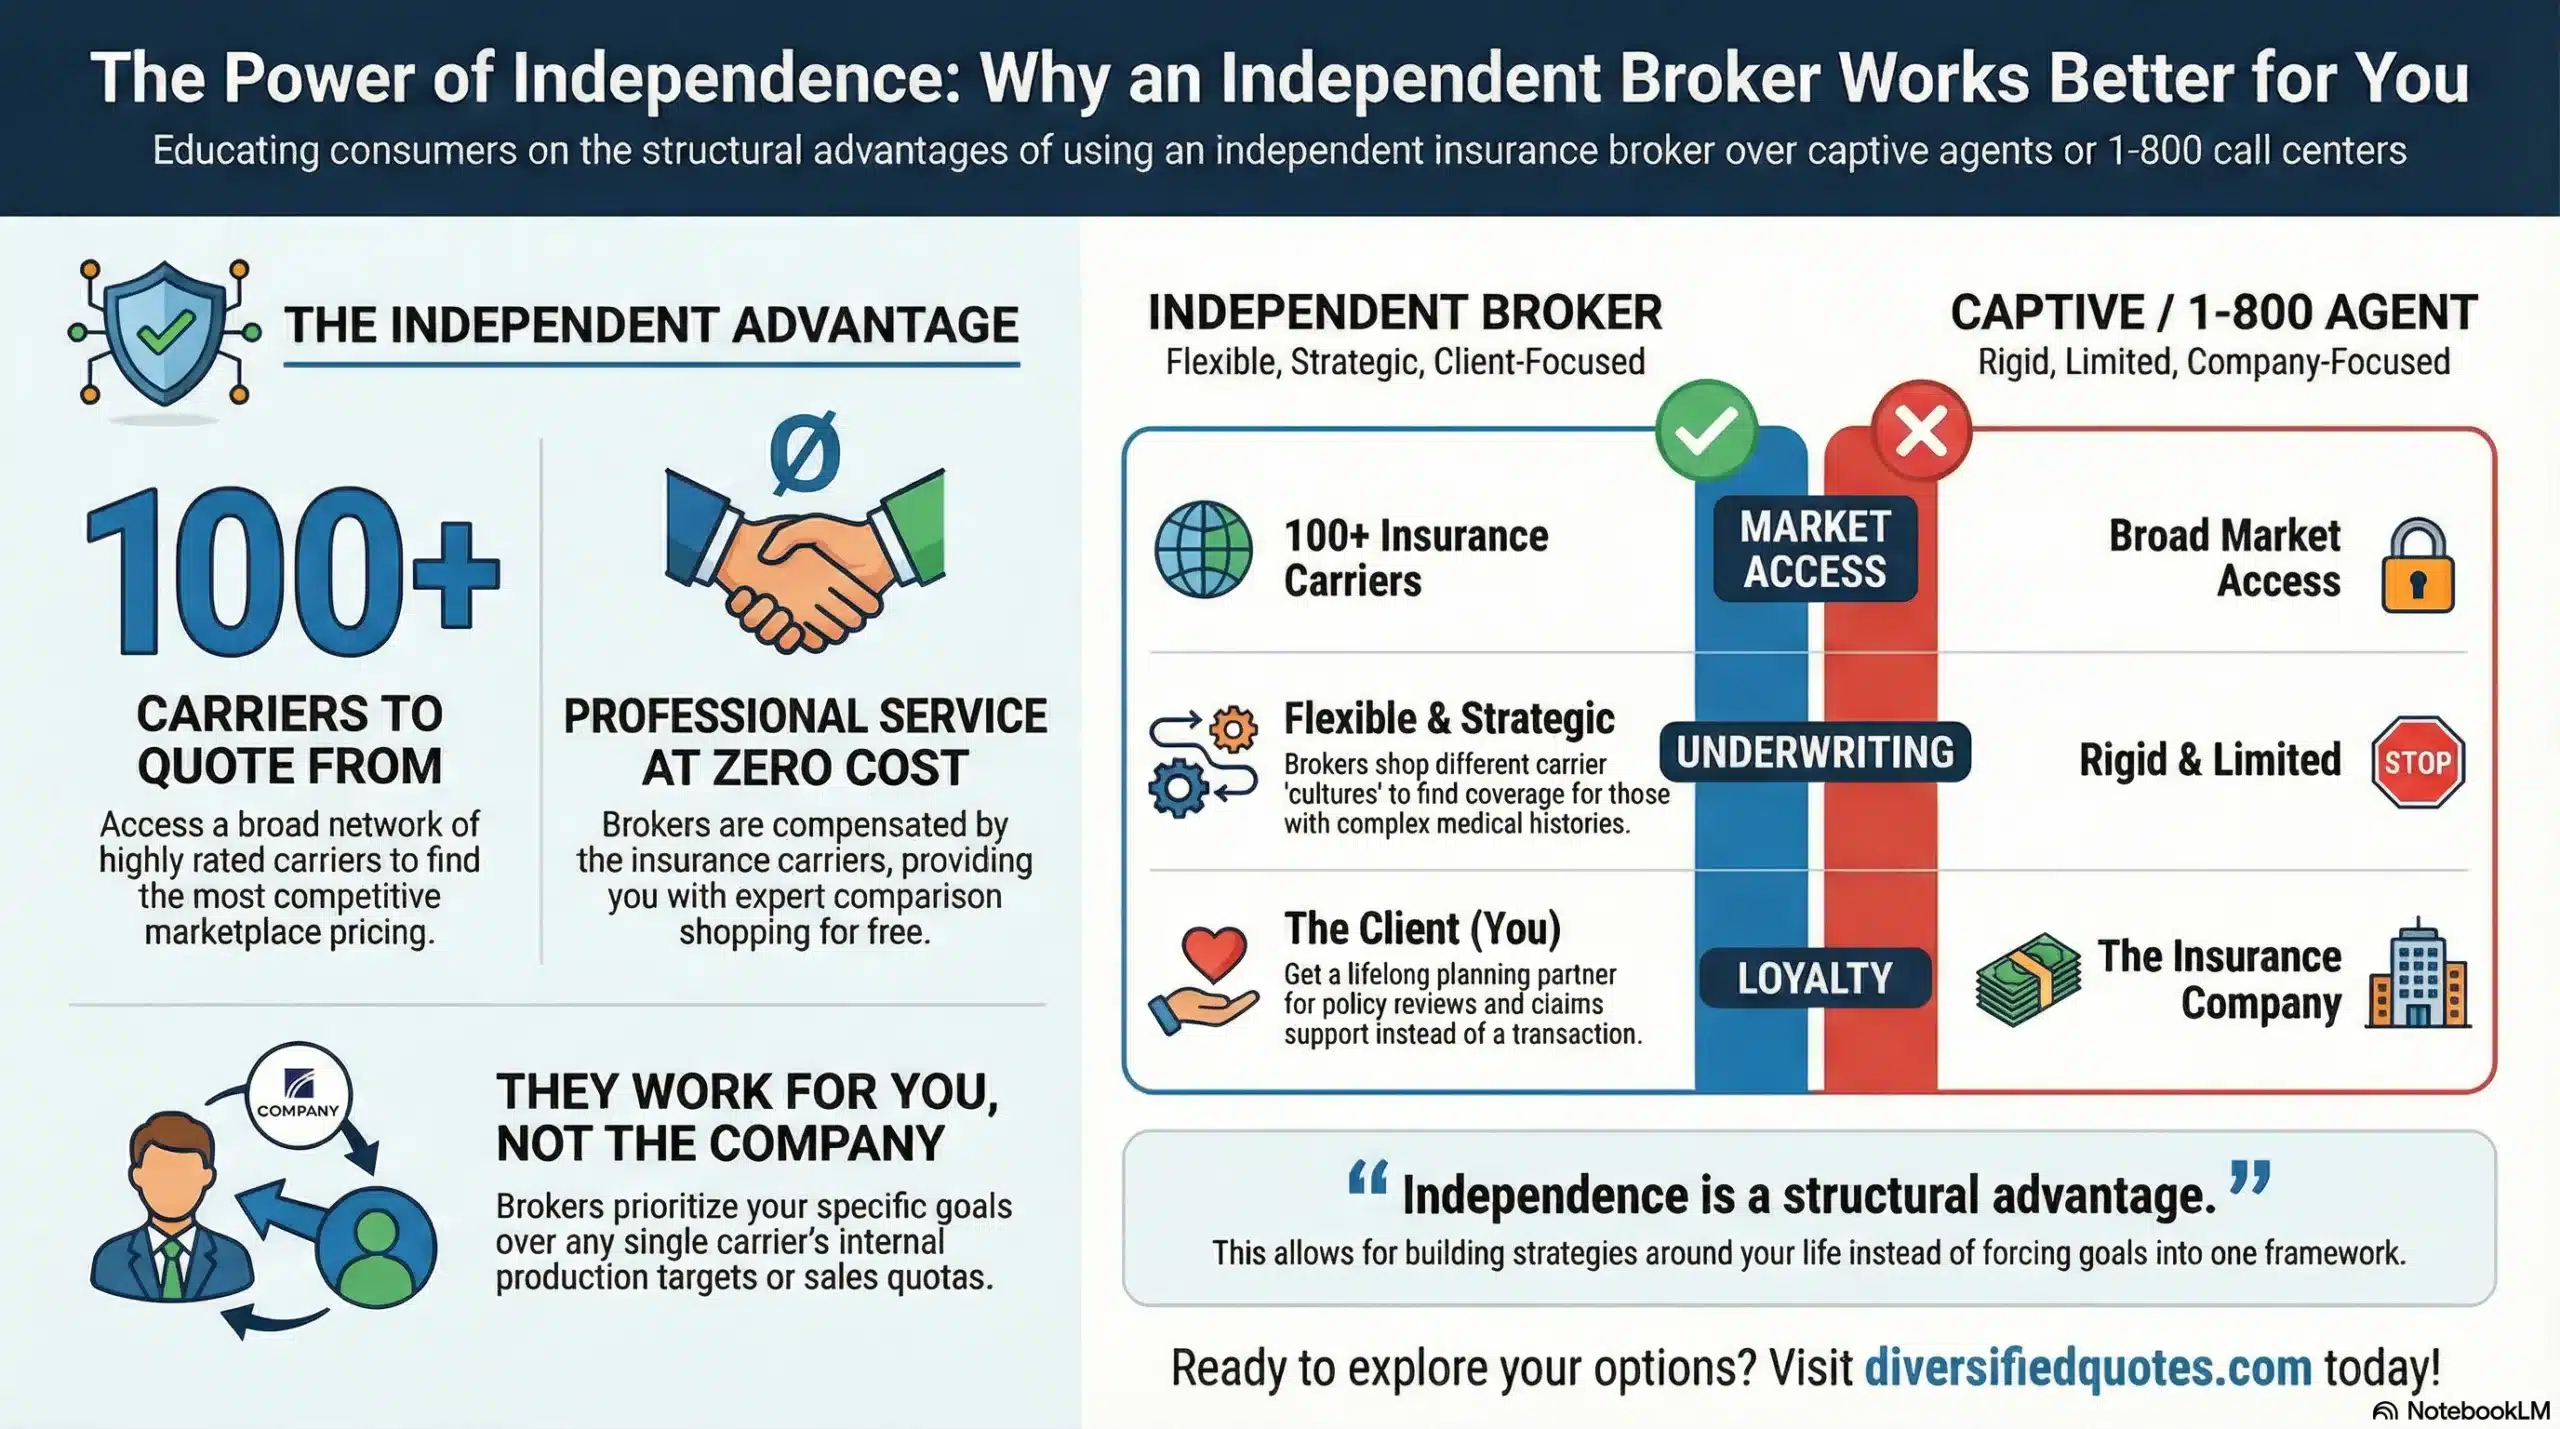
Our guidance on choosing the right policy and how much coverage you need is especially relevant right now, since a growing family is exactly the kind of life change that reasonably prompts a fresh look at how much coverage actually makes sense. If you’d like to understand why working with an independent broker matters, particularly for a case like this where carrier appetite genuinely varies, that’s worth a direct conversation.
Ready to find out what rate class your specific situation would actually qualify for?
Get Your Life Insurance Review
Financial Protection Essentials
Explore policy types, retirement distribution strategies, and beneficiary planning.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Will I be penalized for weight gain during pregnancy when applying for life insurance?
No, not for normal, expected pregnancy weight gain. Underwriters evaluate your pre-pregnancy height and weight as the baseline for assessing your overall health, not your current pregnant weight in isolation. As long as your pre-pregnancy weight was in a normal range and your current pregnant weight is consistent with a healthy pregnancy at your stage, the weight gain itself is not treated as a negative factor. Medical guidance generally supports a gain of 25 to 35 pounds for someone starting with a normal BMI, and that range is understood as healthy, not concerning.
Can pregnant women qualify for the best available life insurance rate class?
Yes, and this happens routinely, not as an unusual exception. A healthy applicant with a normal pre-pregnancy BMI, no complications in the current or any previous pregnancy, and a planned natural delivery frequently qualifies for Preferred Plus, the top rate class most carriers offer. This assumes the applicant qualifies medically on every other front the way any applicant would; pregnancy on its own is not what determines the outcome.
Does a complication from a previous pregnancy affect a current life insurance application?
Yes, and it’s reviewed carefully because it’s a genuine predictor, not just historical information. Research on preeclampsia has found that a prior occurrence significantly raises the risk of it happening again in a later pregnancy, and it’s also linked to higher long-term cardiovascular risk for the mother independent of pregnancy. Gestational diabetes shows a similar recurrence pattern. A documented history of a prior complication is worth addressing directly with real records rather than leaving it as an open question.
Why does an emergency C-section matter differently than a planned one?
Because an emergency C-section typically indicates that a complication emerged during labor, such as fetal distress or another issue that made a surgical delivery medically necessary. It’s the underlying complication that’s actually relevant to underwriting, not the surgical procedure itself, the emergency C-section is simply the marker that reveals something occurred. A planned, elective C-section chosen without any underlying complication doesn’t carry the same implication and is evaluated differently.
Does gestational diabetes disqualify me from getting life insurance?
No. Gestational diabetes, which affects roughly 5% to 9% of pregnancies, is genuinely evaluated more carefully, but coverage remains available. Underwriters generally want to know whether it was diet-controlled or required medication, whether it resolved after delivery, and what postpartum blood sugar testing showed. A diet-controlled case with strong postpartum numbers and a healthy pre-pregnancy BMI is frequently still placeable at a favorable rate, sometimes just one rate class below the very top tier.
Does it matter which trimester I’m in when I apply for life insurance?
No. Trimester timing is not a meaningful underwriting factor. The facts that actually matter, pre-pregnancy BMI, complication history, birth plan, and gestational diabetes status, don’t fundamentally change based on which trimester you’re in. There’s no need to wait until later in pregnancy or rush to apply before a certain point based on the calendar alone.
What records should I gather before applying while pregnant?
Documented pre-pregnancy height and weight, ideally from a medical record rather than memory; a summary from your OB confirming the pregnancy is proceeding without complications and a natural delivery is planned; complete details of any previous pregnancy history, favorable or not; and, if relevant, whether gestational diabetes was diet-controlled and what postpartum testing showed. A complete, organized file along these lines gives an underwriter a genuinely clear picture from the start.
What happens if a carrier wants to wait until after I deliver to make a decision?
This generally happens only when a real complication is present, and it’s a request for the health picture to become clearer, not a decline. If waiting isn’t preferable, coverage remains available in the meantime through simplified underwriting or guaranteed issue options, both available immediately regardless of where things currently stand, often used as a bridge while a fully underwritten application proceeds in parallel.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for Life Stage & Situational Needs — covering new parents, single parents, special needs children, and military service from 100+ carriers.
Last Reviewed: September 10, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
