
Life Insurance for Stay at Home Parents
As an Independent Life Insurance Broker, we compare rates across 100+ carriers and prescreen every application before submission.
Life Insurance for Stay at Home Parents
Jason Stolz CLTC, CRPC, DIA, CAA
Child care for one infant now costs more than public college tuition in thirty-eight states and Washington, D.C. That comparison, from the Economic Policy Institute’s most recent state-by-state analysis, tells you almost everything wrong with how most families think about life insurance for the parent who doesn’t bring home a paycheck. “They don’t earn an income, so there’s nothing to replace” is the single most expensive misconception in family financial planning, and it’s rarely tested against real numbers until it’s far too late to matter.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this exact gap — a well-insured working spouse and an underinsured or completely uninsured stay-at-home parent — is one of the most common, correctable mistakes we see in family coverage reviews. As an independent broker working across dozens of carriers, our office helps families calculate what a stay-at-home parent’s role would actually cost to replace, then builds coverage around that real number instead of a guess based on a paycheck that never existed in the first place.
Wondering how much coverage a stay-at-home parent in your family actually needs? Let’s run the real numbers together.
Talk to a Life Insurance Specialist
| Role Being Filled | What It Actually Costs to Replace | Why It’s Easy to Overlook |
|---|---|---|
| Full-time infant or toddler care | Ranges from roughly $572 a month in the least expensive states to more than $2,363 a month in the most expensive, according to Economic Policy Institute state-by-state data | Never shows up as a household expense while a parent is providing it directly |
| Before and after-school care for older children | Lower than full-day infant care, but a real, ongoing cost most families never price out | Assumed to be a smaller issue simply because kids are in school most of the day |
| Meal planning and preparation | A genuine, if harder to price, daily labor cost — professional meal prep and private chef services run well into five figures annually for a family | Treated as “just part of running a house,” not a service with a market price |
| Household management and logistics | Scheduling, transportation, errands, home maintenance coordination — rarely centralized in a single paid role, but genuinely time-consuming to fully replace | No single line item on a household budget captures this |
| The surviving spouse’s own career trajectory | A genuine, compounding cost — stepping back to cover caregiving gaps is linked to real, lasting wage consequences for the surviving parent | This cost doesn’t appear until years later, long after the initial financial shock has passed |
Figures above reflect Economic Policy Institute state-by-state childcare cost data and general research findings; actual costs vary meaningfully by location, number of children, and specific family circumstances.
See Real-Term Rates Side by Side
Life Insurance Quoter
The Myth: No Paycheck Means Nothing to Replace
The logic feels intuitive on the surface. Life insurance replaces lost income. A stay-at-home parent doesn’t draw a salary. Therefore, the reasoning goes, there isn’t really an income to replace, so a modest policy, or none at all, seems reasonable. This is exactly the kind of clean, plausible-sounding logic that turns out to be badly wrong the moment it meets an actual household budget.
What a stay-at-home parent’s absence actually creates isn’t a gap where an income used to be — it’s a sudden need to pay, in real dollars, for every task that parent was handling directly. Full-time childcare. Meal planning and preparation. Transportation to school, activities, and appointments. Household management that, in a two-income household, would otherwise require hiring someone or dramatically restructuring both parents’ work lives. None of this disappears because there was never a paycheck attached to it. It simply becomes visible, all at once, at the worst possible moment, when a grieving family is least equipped to absorb a sudden five- or six-figure annual cost.
What the Real Numbers Actually Show
The Economic Policy Institute tracks infant care costs state by state, and the range alone tells you how location-dependent this calculation is. Average infant care runs as low as roughly $572 a month in Mississippi and as high as $2,363 a month in Washington, D.C. — a national spread of well over $20,000 a year in center-based infant care costs alone, depending entirely on where a family lives. In New Mexico, EPI’s own case study found infant care costs exceeding $14,000 a year, more than 10% higher than average rent in that state.
The comparison that should reframe how anyone thinks about a stay-at-home parent’s daily work is this: according to EPI’s most recent state-by-state analysis, the average annual cost of infant care is now higher than in-state public college tuition in 38 states and Washington, D.C. Child care also now exceeds average rent in 17 states and D.C. These aren’t projections or marketing figures — they’re a direct comparison against public tuition and housing data most families already understand intuitively, which makes the scale of what’s actually being replaced far easier to grasp than an abstract national average ever could.
It’s worth being honest about something here: several well-publicized surveys have attempted to calculate a stay-at-home parent’s “equivalent salary” by adding up market rates for every individual task — chef, chauffeur, tutor, housekeeper, and so on — and these surveys have produced eye-catching totals ranging anywhere from roughly $115,000 to well over $180,000 a year, depending heavily on methodology. Economists who’ve studied this differently, focused specifically on the marginal time a stay-at-home parent spends on childcare and meal preparation beyond what a working parent would spend anyway, arrive at meaningfully more conservative figures. We’d rather build your coverage decision around concrete, verifiable replacement costs, like the state-level childcare data above, than around a single aggregate salary figure whose number depends entirely on which survey you happen to read.
The Cost That Shows Up Years Later: The Surviving Parent’s Own Career
This is the piece of the calculation almost no one accounts for, and it’s genuinely important. If a stay-at-home parent dies, the surviving spouse often can’t simply hire full-time replacement care and continue working exactly as before. Many surviving parents reduce their hours, decline a promotion or a demanding new role, or step back from the workforce for a period of time to manage the caregiving gap directly. Sociologists who’ve studied long-term employment trajectories have found that career interruptions are linked to substantial, lasting wage consequences that persist well beyond the interruption itself — not a one-time setback, but a compounding one, showing up in every future raise, promotion, and retirement contribution the surviving parent would otherwise have earned.
This is precisely why calculating a stay-at-home parent’s coverage need shouldn’t stop at “what would daycare cost.” A complete picture accounts for the very real possibility that the working spouse’s own long-term earning trajectory is also at stake, not just this year’s childcare bill.
Want to work through what full replacement cost would actually look like for your specific family? Let’s calculate it together.
Get a Personalized Coverage Estimate
Why the Coverage Mismatch Happens in the First Place
In most two-parent households where one parent stays home, the working parent has some form of life insurance, often a modest group policy through their employer, sized loosely around a multiple of their salary. The stay-at-home parent frequently has little to nothing, or is added almost as an afterthought at a token amount when the working parent’s own policy is purchased. This mismatch happens because the entire mental framework for “how much coverage do we need” is built around replacing a salary, and a stay-at-home parent’s contribution never registers on that scale, even though the dollar cost of losing it is often just as large, and sometimes larger, than the cost of losing the working spouse’s paycheck.
Our broader guide on how much life insurance you actually need covers the general methodology behind sizing coverage, but for a non-earning spouse, the calculation needs to start from replacement cost rather than income multiples. What would it genuinely cost, every year, until your youngest child no longer needs full-time supervision, to replace what this parent currently does? That number, not a fraction of a salary that was never being paid, is the right starting point.
Why the Need Isn’t Flat Over Time
Here’s something worth understanding clearly before choosing a policy structure: a stay-at-home parent’s replacement cost isn’t a constant number across their children’s entire upbringing. It’s highest when children are very young, since full-time infant and toddler care is both the most expensive form of childcare and the least flexible for a grieving surviving parent to arrange quickly. As children move into elementary school, the need shifts toward before- and after-school care rather than full-day supervision, a meaningfully lower cost. By the time children reach the teenage years, direct supervision needs drop again substantially, even though household management and emotional support remain genuinely valuable.
This declining-need curve is exactly the kind of pattern most families completely miss when they buy a single, flat term policy sized once and never revisited. A family with a newborn and a policy built to last thirty years at a single face amount is either overpaying for coverage they won’t need in year twenty-five, or worse, underinsuring the years that actually matter most, right now, while their children are youngest and care costs are highest.
Laddering: A Strategy Built for This Exact Situation
This is precisely the scenario life insurance laddering was designed to solve. Rather than one large policy at a single face amount for a single term length, laddering means stacking several smaller term policies of different lengths, so your total coverage steps down in stages that roughly track your family’s actual, declining need over time.
For a stay-at-home parent specifically, this might look like a shorter policy sized to cover the highest-cost years of full-time infant and toddler care, layered underneath a longer policy sized to cover the more moderate cost of school-age supervision and household support that continues well beyond that. When the shorter policy expires, your coverage naturally steps down to match a genuinely lower replacement cost, rather than continuing to pay for protection against a need that’s already substantially shrunk. This approach can meaningfully reduce total premium cost over the life of your coverage compared to buying one large policy sized for your family’s peak need and holding it flat for decades.
Term With Return of Premium: Making the Decision Easier to Commit To
One psychological hurdle families run into specifically with a stay-at-home parent’s coverage is a version of this thought: “We’re already stretching to cover one income’s worth of life insurance — spending real money insuring someone who doesn’t earn a paycheck feels like an added expense we’re not sure we’ll ever see value from.” Term life insurance with return of premium is worth understanding specifically because of how directly it addresses that exact hesitation.
A return-of-premium term policy costs more than standard term coverage for the identical face amount, but if the policy term ends and no death benefit was ever paid out, every premium dollar paid in over the life of the policy is returned to you. For a family wrestling with whether spending money on a policy for a parent who “isn’t bringing in an income” is worthwhile, this structure reframes the decision entirely: the premium isn’t money that’s simply gone if nothing happens. It’s protection during the years it’s needed most, with a full refund waiting at the end if it turns out you never needed to use it. For many families weighing coverage on a stay-at-home parent specifically, that reframing is what actually gets the policy purchased instead of postponed indefinitely.
This Fits Into the Broader Picture of Insuring Your Whole Family
Coverage on a stay-at-home parent shouldn’t be evaluated in isolation from your family’s broader protection plan. Our guide on life insurance for parents with young children covers the fuller picture of how coverage on both parents works together, including how to think about coordinating face amounts, terms, and beneficiary structures across two policies rather than evaluating either parent’s coverage as a standalone decision.
The Good News: This Is Usually an Easy Case to Underwrite
Unlike many of the specific medical situations we help clients navigate, coverage for a stay-at-home parent is, in the vast majority of cases, a genuinely straightforward underwriting conversation. Most stay-at-home parents are otherwise healthy adults with no complicated medical history driving the application, which means favorable rate classes are frequently realistic, and options like simplified, no-exam underwriting are often available for smaller face amounts, letting coverage get in place quickly without unnecessary delay.
The real obstacle for most families isn’t underwriting difficulty at all — it’s simply never getting around to applying, because the perceived need feels lower than it actually is. And because life insurance pricing is directly tied to age and health at the time of application, delaying coverage on a young, healthy stay-at-home parent for years while treating it as a lower priority than the working spouse’s coverage often means paying more, or facing more restrictive underwriting, than would have applied if the policy had simply been purchased earlier.
How We Help
We start by calculating what your specific family’s stay-at-home parent actually does, region by region, child by child, and translate that into a real, defensible replacement-cost number, rather than defaulting to a token amount because there’s no salary to reference. From there, we’ll help you decide whether a laddered structure, a return-of-premium policy, a standard level term policy, or some combination genuinely fits your family’s situation and budget.
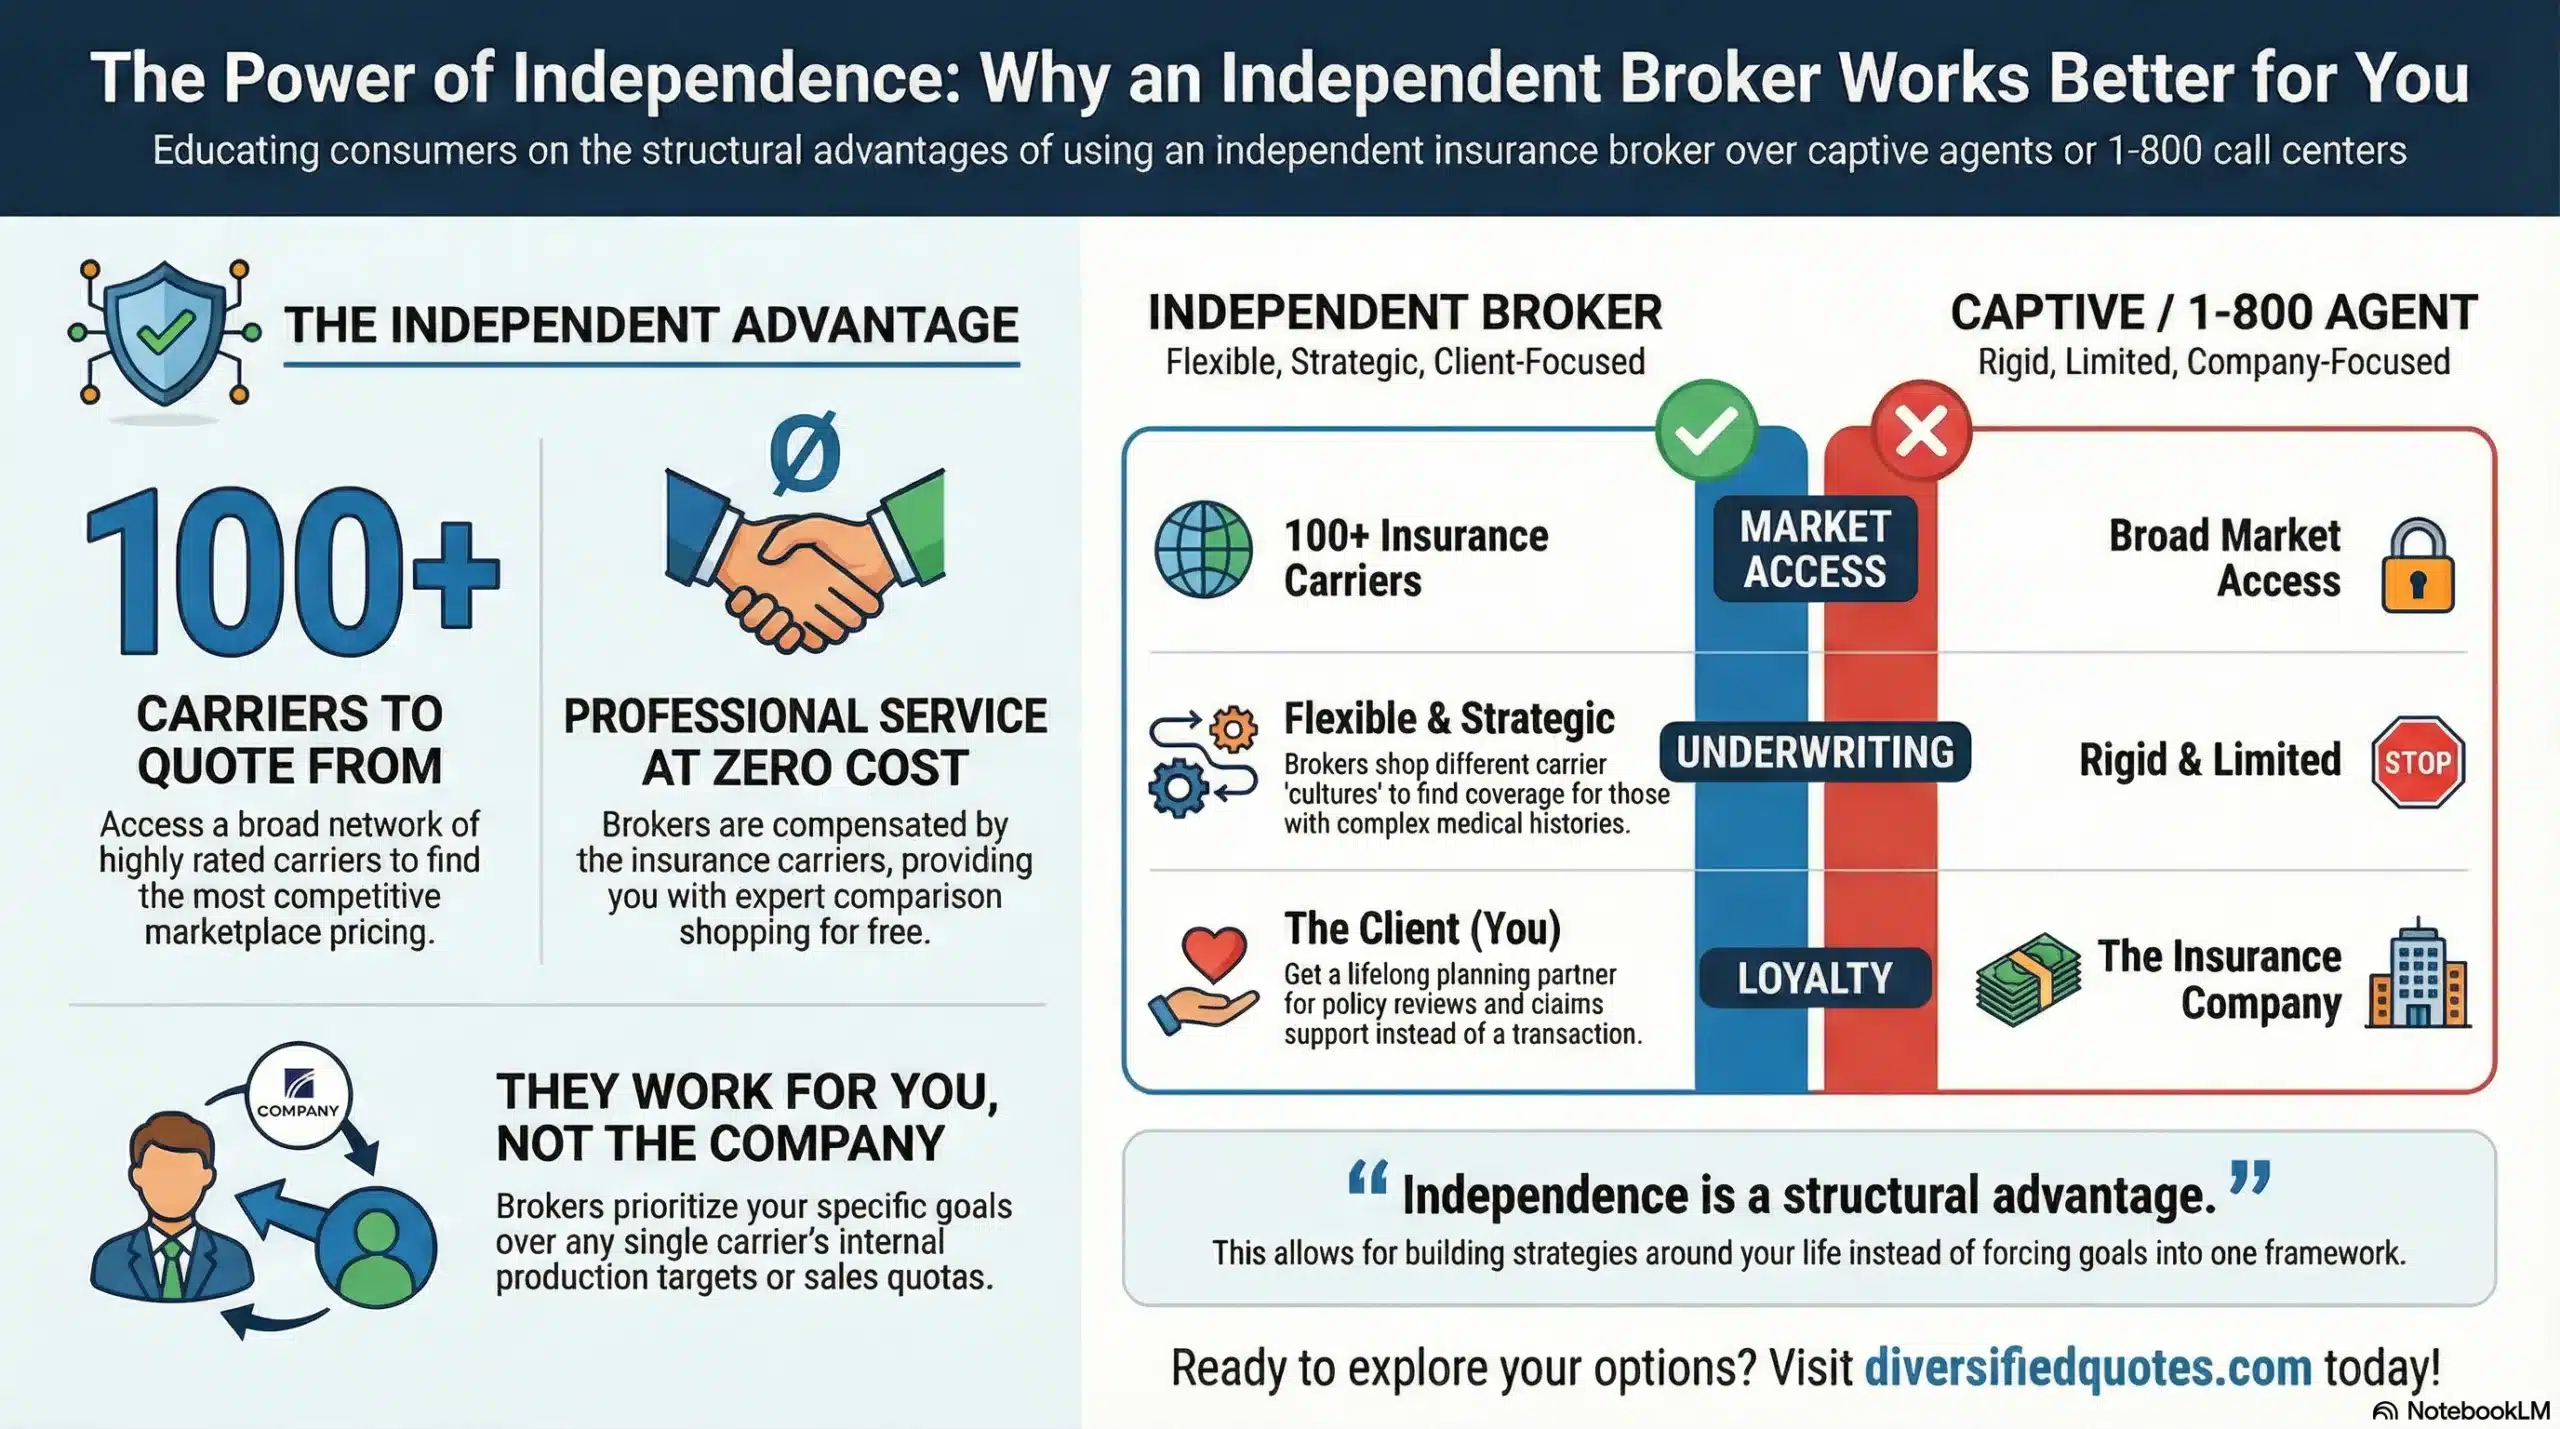
Our broader guidance on choosing the right policy reflects the same principle we bring to every family we work with: the right amount of coverage is the amount that actually reflects what would need to be replaced, not a rough guess based on whether a paycheck happened to be involved. If you’d like to understand why working with an independent broker matters for getting this calculation right, that’s worth a direct conversation.
Ready to find out what real, full coverage for your stay-at-home parent would actually look like?
Get Your Life Insurance Review
Financial Protection Essentials
Explore retirement planning, family coverage structures, and claims guidance.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Does a stay-at-home parent actually need life insurance if they don’t earn an income?
Yes, and often just as much as, or more than, the working spouse. Life insurance replaces value that would otherwise be lost, not just a paycheck specifically. A stay-at-home parent’s role, childcare, meal preparation, household management, transportation, has a real, calculable dollar cost to replace, and that cost has to be paid regardless of whether a salary was ever attached to the work being done.
How much does it actually cost to replace a stay-at-home parent’s work?
Center-based infant care alone ranges from roughly $572 a month in the least expensive states to more than $2,363 a month in the most expensive, according to Economic Policy Institute state-by-state data. According to EPI’s most recent analysis, the average annual cost of infant care is now higher than public college tuition in thirty-eight states and Washington, D.C., and higher than average rent in seventeen states and D.C. Families with more than one young child, or who also need to account for meal preparation and household management, frequently face a replacement cost well beyond childcare alone.
Why do so many families underinsure the stay-at-home parent?
Because coverage decisions are traditionally built around replacing a salary, and a stay-at-home parent’s contribution never registers on that scale, even though its actual dollar cost to replace can be just as large as the working spouse’s income, sometimes larger. The working spouse often has some coverage through an employer, while the stay-at-home parent is added as an afterthought or skipped entirely, simply because there’s no paycheck to anchor the calculation to.
Does the surviving spouse’s own career get affected if a stay-at-home parent dies?
It genuinely can, and this cost often gets overlooked entirely. Many surviving parents reduce their hours, decline advancement opportunities, or step back from the workforce for a period to manage the caregiving gap. Research on long-term employment trajectories has found that career interruptions are linked to substantial, lasting wage consequences that persist well beyond the interruption itself. This is a real, compounding cost that shows up years after the initial loss, not just an immediate childcare expense.
Why would I use life insurance laddering for a stay-at-home parent’s coverage?
Because the actual replacement cost isn’t constant over time. It’s highest when children are very young and full-time care is most expensive, and it declines as children move into school and eventually the teenage years. Laddering, stacking several term policies of different lengths, lets your total coverage step down in stages that roughly track this declining need, rather than paying for peak-level coverage across decades where the need has already substantially shrunk.
What’s the advantage of return-of-premium term for a stay-at-home parent’s policy specifically?
It directly addresses the hesitation many families feel about spending money insuring a parent who doesn’t bring in a paycheck. A return-of-premium policy costs more than standard term, but if the term ends with no claim paid, every premium dollar is returned. For families uncertain whether coverage on a non-earning spouse is worth the ongoing cost, that guarantee of a full refund if it’s never needed often makes the decision to actually purchase coverage much easier.
Is it harder to get approved for life insurance as a stay-at-home parent?
Generally not. Most stay-at-home parents are otherwise healthy adults without complicated medical histories, which means favorable rate classes are frequently realistic, and simplified, no-exam underwriting is often available for smaller face amounts. The real barrier for most families isn’t underwriting difficulty, it’s simply delaying the application because the need feels lower than it actually is.
Does waiting to insure a stay-at-home parent actually cost more later?
Often, yes. Life insurance pricing is directly tied to age and health at the time of application. Treating a stay-at-home parent’s coverage as a lower priority and delaying the application for years, while otherwise healthy and young, typically means paying more, or facing more restrictive underwriting, than if the policy had simply been purchased earlier.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance Buying & Cost Education — covering how to buy, costs, calculators, rates & buying guides from 100+ carriers.
Last Reviewed: September 16, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
