
What is the Interest Rate on a $4 Million Annuity
What is the Interest Rate on a $4 Million Annuity
Jason Stolz CLTC, CRPC, DIA, CAA
When individuals approach retirement with significant savings, a common question often arises: how much interest can a large annuity earn? For example, someone considering a $4 million annuity typically wants to understand how the interest rate works, how the investment may grow over time, and how it might translate into retirement income. While the size of the annuity investment does not directly determine the interest rate itself, the total amount invested dramatically affects how much interest is earned and how much income the annuity can potentially generate.
Annuities are insurance contracts designed to provide tax-deferred growth and, in many cases, predictable or guaranteed income during retirement. They are commonly used by individuals who want to protect a portion of their savings from market volatility while still earning interest. For investors allocating $4 million to an annuity, the objective is often to balance growth, stability, and income security over a long retirement horizon.
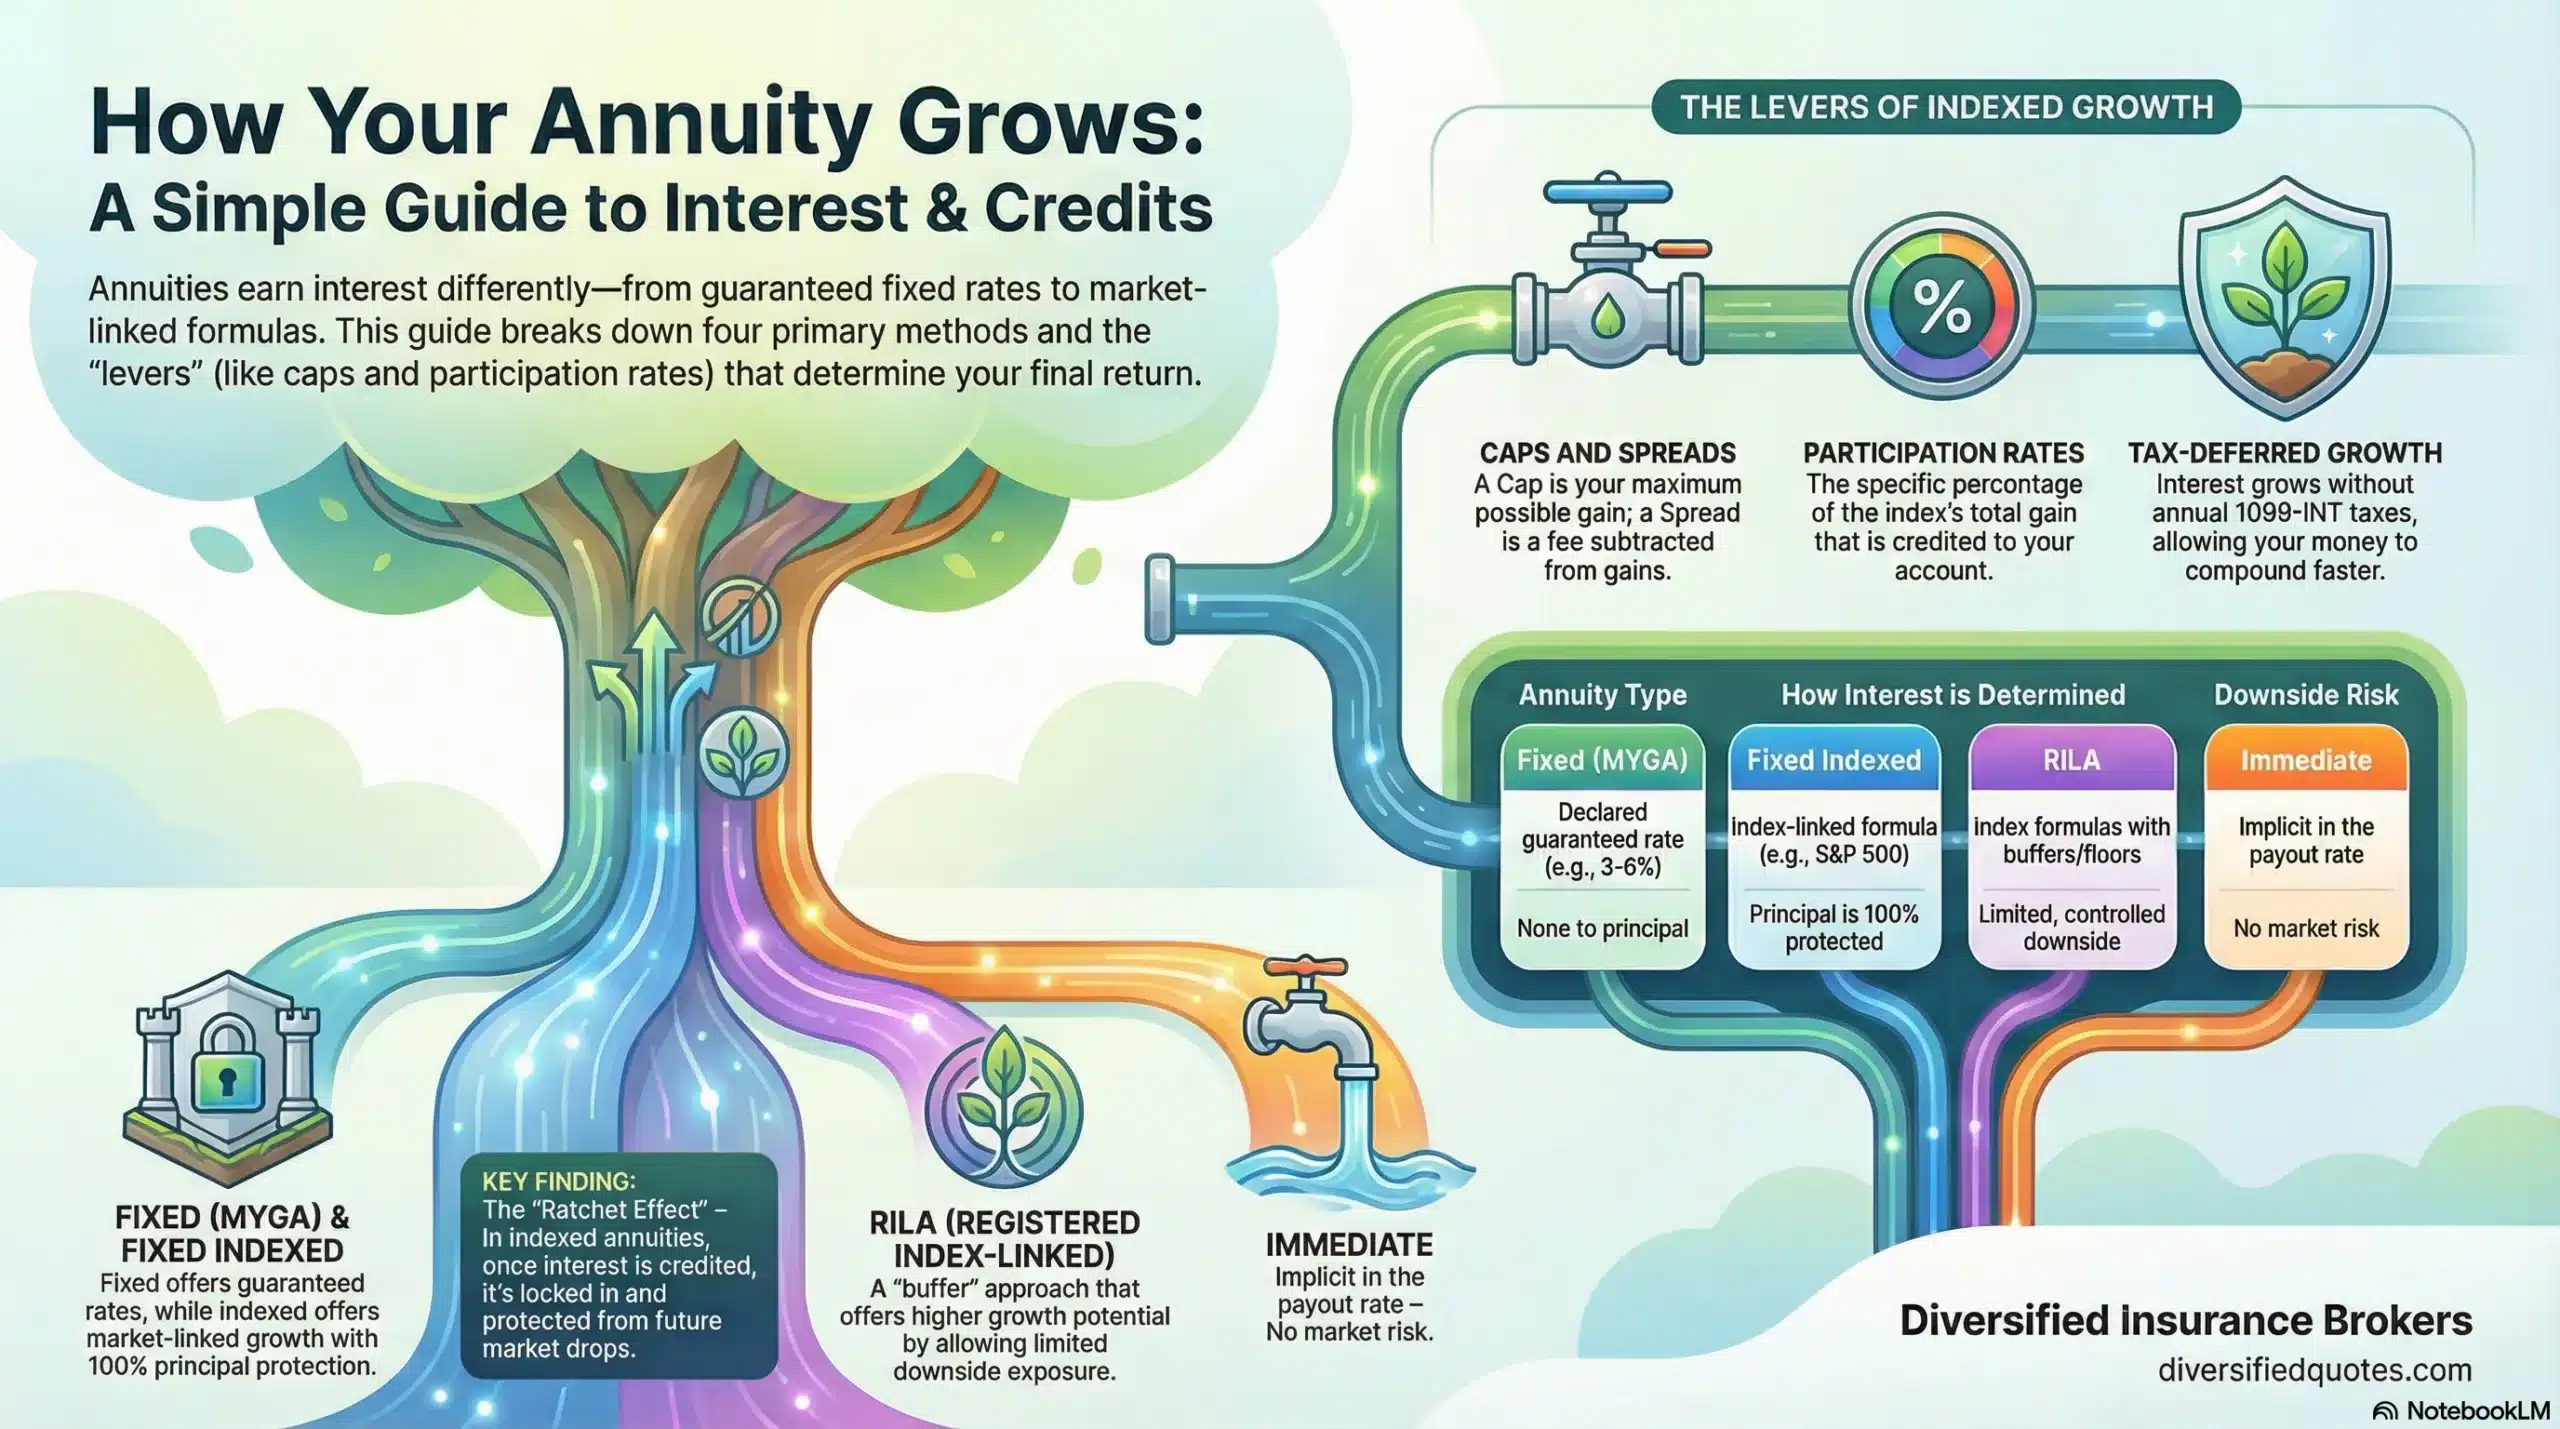
Interest credited to an annuity compounds within the contract, meaning that earnings remain invested and generate additional earnings in future years. Over long periods of time, this compounding effect can dramatically increase the value of the original investment. Because annuity growth is typically tax-deferred, the entire balance continues compounding without annual taxes reducing the growth.
Many retirees evaluate annuities as part of a broader retirement income strategy that combines protected income sources with traditional investments. Conducting an investment risk analysis can help determine how annuities fit into a diversified portfolio designed to balance risk and stability.
Understanding how interest works in annuities helps investors evaluate whether allocating a portion of their retirement savings to a large annuity contract may help support long-term financial security.
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Compare Multi-Year Guaranteed Annuity Rates
Explore the best annuity rates by term length to find the option that fits your timeline and income strategy.
How Interest Works on a $4 Million Annuity
The interest credited to an annuity contract depends primarily on the type of annuity selected and prevailing economic conditions. Fixed annuities provide guaranteed interest rates for a defined period of time. Indexed annuities link interest crediting to the performance of a financial market index while protecting the principal from market losses.
Insurance companies invest annuity premiums in diversified portfolios that typically include government bonds, corporate bonds, and other income-producing securities. The returns generated by these investments support the interest credited to annuity contracts.
Although the interest rate itself is generally the same regardless of investment size, the total dollar value of interest earned increases significantly as the investment amount grows. A moderate interest rate applied to a $4 million annuity can produce hundreds of thousands of dollars in annual growth.
Many investors evaluating large annuity allocations also examine how annuities compare with other retirement income strategies. Articles such as how much an annuity pays help illustrate how annuity balances may translate into retirement income.
Others consider how annuities may fit alongside broader financial planning decisions, such as determining what to do with retirement savings after leaving the workforce or evaluating rollover strategies like transferring a Solo 401(k) to an annuity.
Example Growth of a $4 Million Annuity
The example below illustrates how a $4 million annuity might grow assuming a hypothetical interest rate. These numbers are examples designed to demonstrate compound growth rather than represent current annuity rates.
| Year | Account Value (Example 6%) | Interest Earned |
|---|---|---|
| 1 | $4,240,000 | $240,000 |
| 5 | $5,352,902 | $302,800 |
| 10 | $7,163,394 | $405,450 |
| 15 | $9,586,192 | $542,600 |
| 20 | $12,828,542 | $726,160 |
This example demonstrates how compounding interest can significantly increase the value of an annuity over time. Even modest interest rates can produce substantial growth when applied to large investment amounts over long periods.
Factors That Influence Annuity Interest Rates
Annuity interest rates are influenced by several factors, most notably the bond market. Insurance companies invest annuity premiums primarily in fixed-income securities. When bond yields rise, annuity interest rates generally increase. When bond yields decline, annuity crediting rates may decrease as well.
The length of the annuity contract also affects interest rates. Longer surrender periods often allow insurers to offer higher crediting rates because they can invest funds over longer time horizons.
Some annuities include optional features such as lifetime income riders or enhanced death benefits. These features can affect how interest is credited because they introduce additional guarantees into the contract. Investors researching these options often explore resources such as how annuity income riders work when evaluating different contract structures.
Large retirement portfolios are often managed alongside broader tax planning strategies as well. Concepts such as Roth conversion windows may be evaluated alongside annuity strategies when designing a long-term retirement plan.
How a $4 Million Annuity Can Produce Retirement Income
While interest accumulation is important, many individuals purchase annuities primarily to create reliable retirement income. Once the accumulation phase ends, the annuity can be converted into a stream of payments that may continue for a fixed period of time or for the lifetime of the annuitant.
The income generated by a $4 million annuity depends on several factors including the annuitant’s age, interest rates at the time income begins, and the payout structure selected. Lifetime income options are particularly valuable because they address longevity risk, which is the possibility of outliving retirement savings.
Many retirees combine annuity income with Social Security benefits and withdrawals from investment portfolios to create multiple income streams. This approach helps diversify income sources and reduce reliance on market performance.
Some individuals also evaluate rollover strategies when transitioning retirement accounts into income-producing vehicles. For example, investors may explore options such as transferring a Keogh plan to an annuity as part of their retirement planning.
When used strategically, annuities can provide peace of mind by ensuring that essential retirement expenses are covered regardless of market fluctuations.
Request a Quote
Related Pages
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Does an annuity avoid probate when it passes to a beneficiary?
Generally yes, as long as a named beneficiary is on file with the carrier. Because an annuity is a contract with a designated beneficiary, proceeds typically pass directly to that person outside of the probate process, similar to how a life insurance death benefit or a retirement account with a named beneficiary works. This is one of the reasons keeping beneficiary designations current is so important — if no living beneficiary is on record, or if the designation was never updated, the contract can end up passing through the estate and probate after all.
Is a non-qualified annuity taxed differently than one held inside an IRA?
Yes, and the difference is significant. An annuity held inside a qualified account, such as an IRA, is generally taxed the same way any other withdrawal from that account would be — as ordinary income on the full amount withdrawn, since the original contribution was typically pre-tax. A non-qualified annuity, purchased with after-tax dollars outside a retirement account, is taxed differently: withdrawals are treated as coming from earnings first under a last-in-first-out rule, meaning the growth portion is taxed as ordinary income while the original principal, already taxed once, is not taxed again upon withdrawal.
What is the difference between an annuity’s accumulation value and its surrender value?
The accumulation value, sometimes called the account value, is the full contract value shown on a statement, reflecting premium paid plus any interest credited. The surrender value is what an owner would actually receive if they fully cashed out the contract at that moment, and during the surrender charge period, it’s typically the accumulation value minus any applicable surrender charge and market value adjustment. Outside the surrender period, the two figures generally match. This distinction matters because the number on a statement isn’t always the number a full withdrawal would actually produce.
How much can typically be withdrawn from an annuity each year without a surrender charge?
Many annuity contracts include an annual free withdrawal provision, commonly allowing up to 10% of the account value to be withdrawn each contract year without triggering a surrender charge, even during the surrender period. This is separate from the free-look period, which only applies immediately after purchase — the annual free withdrawal allowance is an ongoing feature that resets each year. The exact percentage and terms vary by contract, so confirming the specific allowance on a given annuity is worthwhile before assuming a standard figure applies.
What is a bailout provision on an annuity?
A bailout provision allows an annuity owner to exit a contract without a surrender charge if the insurer’s renewal interest rate drops below a specific threshold stated in the contract. This feature exists specifically for annuities where the rate guarantee period is shorter than the surrender charge period, giving the owner a penalty-free way out if a later renewal rate turns out to be unattractive. Not every annuity includes this feature, so it’s worth confirming whether a specific contract has one and, if so, what threshold triggers it.
What’s the difference between a life-only payout and a life-with-period-certain payout?
A life-only payout pays income for as long as the annuitant lives and stops entirely upon death, with no further payments to beneficiaries, regardless of how soon death occurs. A life-with-period-certain payout guarantees payments for a minimum number of years even if the annuitant dies before that period ends, with remaining payments continuing to a named beneficiary. Because life-only carries more risk for the annuitant of receiving little total income if death comes early, it typically pays a higher periodic amount than a life-with-period-certain option funded with the same balance.
Can an annuity help cover long-term care costs if health needs change later in retirement?
Some annuities offer an optional rider that accelerates or enhances income specifically if the annuitant is later diagnosed with a chronic illness or qualifies for long-term care under the rider’s specific criteria, typically defined by an inability to perform certain activities of daily living. This is a distinct feature that must be added to the contract, not something every annuity includes automatically, and the qualifying criteria and enhanced benefit amount vary by carrier and product. It’s a meaningfully different tool than a standalone long-term care insurance policy, and the two shouldn’t be assumed to provide equivalent coverage.
Do annuity income payments increase over time to keep up with inflation?
Not by default. A standard annuitized payout is typically level, meaning the payment amount stays the same for the duration of the payout period, which means its purchasing power gradually erodes with inflation over a long retirement. Some contracts offer an optional cost-of-living adjustment rider that increases payments by a set percentage or index each year, though electing this feature generally means starting with a lower initial payment in exchange for payments that grow over time. Whether that trade-off makes sense depends on how much of a retiree’s other income is already inflation-protected.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to How Much Does an Annuity Pay? — covering annuity payout calculators, income amounts & interest rates by investment size from 100+ carriers.
Last Reviewed: September 1, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
