
What is the Interest Rate on a $750,000 Annuity
What is the Interest Rate on a $750,000 Annuity
Jason Stolz CLTC, CRPC, DIA, CAA
One of the most common questions people ask when researching annuities is how much interest a specific investment amount may earn. A frequently discussed example is a $750,000 annuity. While the size of the investment does not directly determine the interest rate credited to an annuity, it has a significant impact on the total interest earned and the potential retirement income that may eventually be generated.
Annuities are insurance contracts designed to provide tax-deferred growth and, in many cases, predictable retirement income. Unlike traditional investment accounts that may fluctuate with market volatility, many annuities are structured to provide principal protection while still offering steady growth. For individuals allocating $750,000 toward an annuity, the goal is often to create stability and income certainty during retirement.
Understanding how annuity interest rates work is essential for evaluating how a large investment may grow over time. Interest credited to annuities compounds within the contract, meaning that earnings generate additional earnings in future years. Over long periods of time, this compounding effect can significantly increase the value of the original investment.
Many retirees evaluate annuities as part of a broader retirement strategy that balances growth-oriented investments with protected income sources. Tools such as an investment risk analysis can help determine how much of a portfolio should remain exposed to market volatility and how much may benefit from the stability that annuities can provide.
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Compare Multi-Year Guaranteed Annuity Rates
Explore the best annuity rates by term length to find the option that fits your timeline and income strategy.
How Interest Works on a $750,000 Annuity
The interest credited to an annuity is determined by the contract structure rather than the size of the investment. However, when the investment amount is larger, each percentage point of interest produces significantly greater growth in dollar terms.
Insurance companies that issue annuities invest premiums into diversified portfolios that commonly include high-quality bonds and other income-producing securities. These investments generate returns that support the interest credited to annuity contracts.
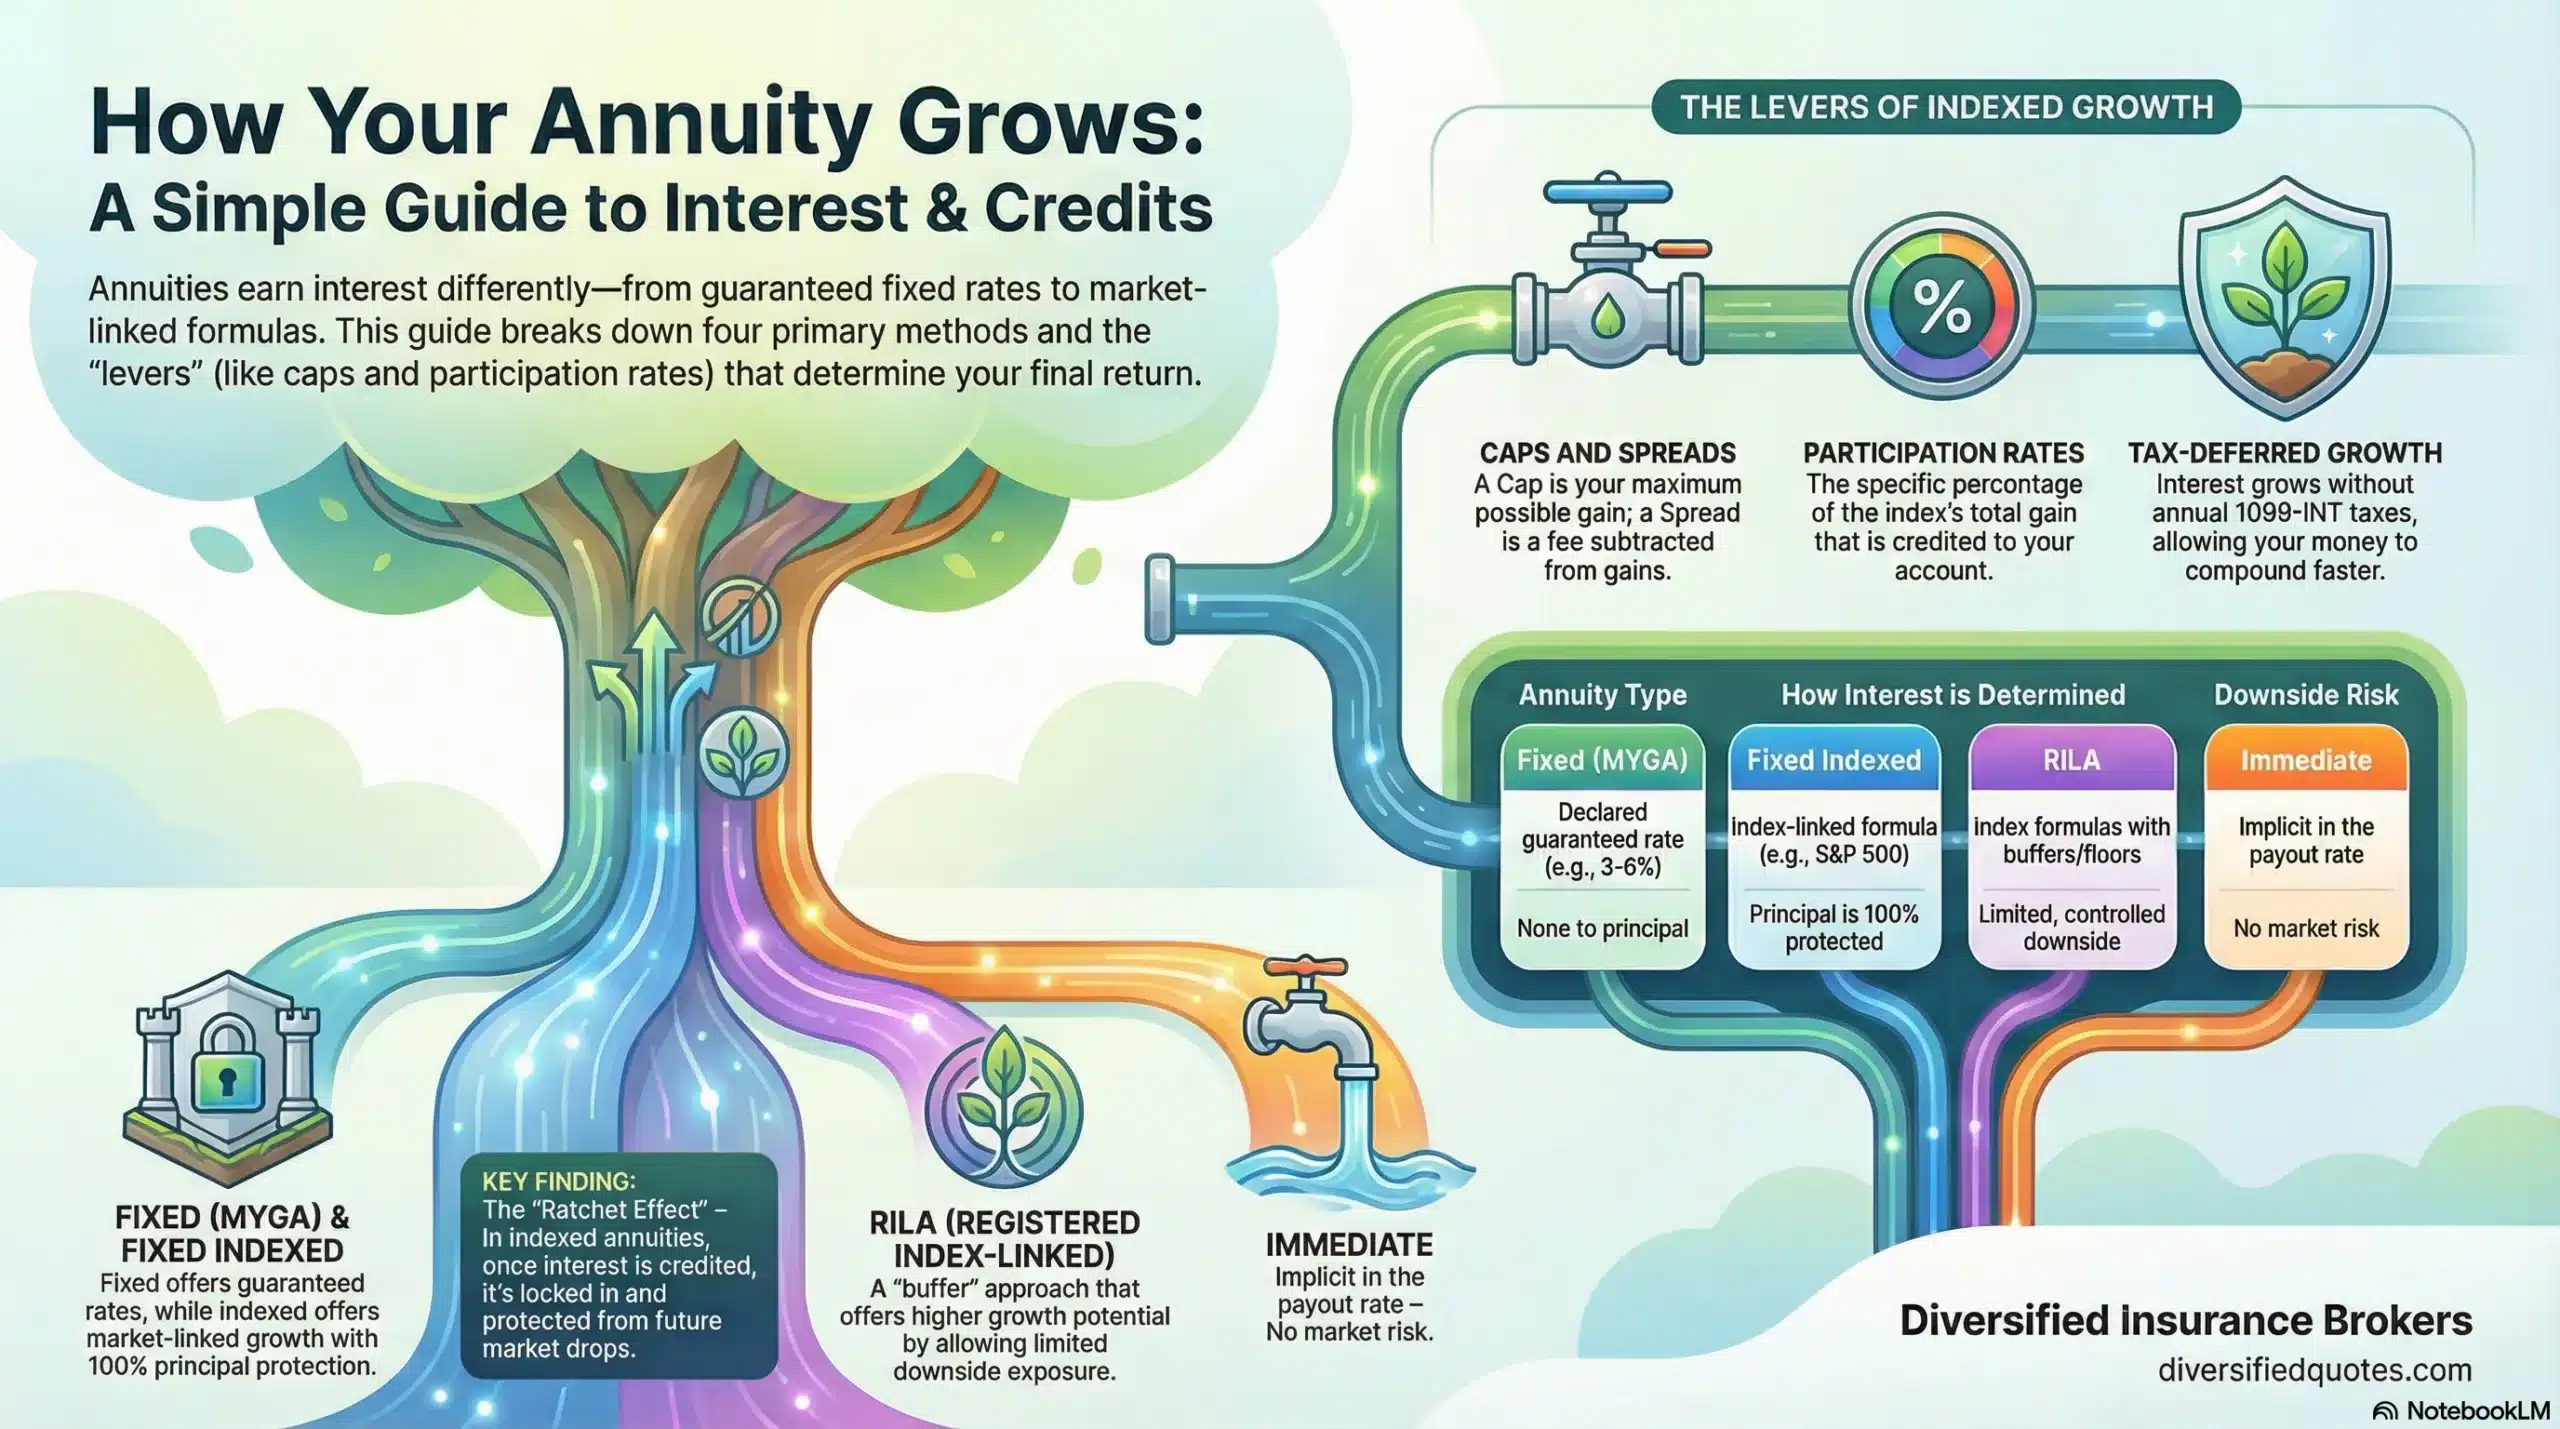
Fixed annuities typically provide guaranteed interest rates for a defined number of years. Indexed annuities link interest crediting to a financial index while protecting the principal from market losses. Both structures allow investors to grow savings while reducing exposure to market volatility.
For someone allocating $750,000 to an annuity, this structure can provide both growth potential and capital protection. Many individuals use annuities to protect retirement savings that they cannot afford to lose in market downturns.
Investors often evaluate annuities alongside other retirement planning tools such as how much an annuity pays in income or strategies for what to do with retirement savings after leaving the workforce.
Example Growth of a $750,000 Annuity
The example below illustrates how a $750,000 annuity might grow assuming a hypothetical interest rate. These numbers are designed to demonstrate the effects of compound growth and do not represent current annuity rates.
| Year | Account Value (Example 6.00%) | Interest Earned |
|---|---|---|
| 1 | $795,000 | $45,000 |
| 5 | $1,003,670 | $56,775 |
| 10 | $1,343,136 | $76,022 |
| 15 | $1,797,411 | $101,739 |
| 20 | $2,405,353 | $136,155 |
This example highlights how compound interest can significantly increase the value of an annuity over long time periods. Because annuities typically grow on a tax-deferred basis, earnings remain invested and continue compounding without annual taxation reducing growth.
Factors That Influence Annuity Interest Rates
Several factors influence the interest credited to annuity contracts. One of the most significant is the bond market. Insurance companies invest annuity premiums primarily in fixed-income securities. When bond yields rise, annuity interest rates often increase as well. When bond yields fall, annuity rates may decline.
The length of the annuity contract can also influence interest rates. Longer surrender periods often allow insurers to offer higher crediting rates because they can invest funds for longer time horizons.
Some annuities include additional features such as income riders or enhanced death benefits. These features provide additional guarantees within the contract and may influence how interest is credited. Investors evaluating these features often review resources such as how annuity income riders work.
In many retirement plans, annuities are used alongside tax strategies such as Roth conversion planning or rollover strategies like transferring retirement accounts to annuities.
How a $750,000 Annuity Can Generate Retirement Income
While interest accumulation is important, many individuals purchase annuities for income rather than growth alone. Once the accumulation phase ends, the annuity can be converted into a stream of payments that may continue for a specific period or for the lifetime of the annuitant.
The amount of income generated depends on several factors including the annuitant’s age, interest rates at the time income begins, and the payout option selected.
Lifetime income options help address longevity risk, which is the possibility of outliving retirement savings. By providing income that continues for life, annuities help retirees maintain financial stability regardless of lifespan.
Request a Quote
Related Pages
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Does putting $750,000 into an annuity earn a better rate than a smaller investment would?
No — the interest rate an annuity credits comes from the structure of the contract itself, not the size of the deposit. What changes at this scale is the arithmetic: because the balance is large, every single percentage point of interest translates into a much bigger dollar figure than the identical rate would produce on a smaller account. The rate stays the same regardless of investment size; the payoff from that rate does not.
What is an enhanced death benefit rider, and is it worth adding to a large annuity?
An enhanced death benefit rider is an optional feature that increases or otherwise improves what a beneficiary receives if the annuity owner passes away before the funds are fully paid out, beyond what the contract’s standard death benefit would provide. Like other riders, it’s added to the base contract for an additional cost and doesn’t change how interest is credited during the accumulation phase. Whether it’s worth adding depends on estate planning goals and who the intended beneficiaries are, which makes it worth evaluating on its own terms rather than assuming it’s automatically included.
Can a $750,000 annuity fit alongside a Roth conversion or a retirement account rollover?
Yes, and the two are often planned together rather than treated as separate decisions. Some retirees use annuity funding as part of a broader sequence that also involves converting a portion of tax-deferred savings to a Roth account, or rolling funds from an existing retirement account into the annuity itself. Because the timing and tax treatment of each piece can affect the others, this is generally a case where the annuity purchase and the surrounding tax strategy should be planned as one coordinated decision.
Why would someone prioritize protecting $750,000 over trying to grow it in the market?
For many people approaching or already in retirement, a balance this size represents money they genuinely cannot afford to lose to a market downturn, since there may not be enough working years left to recover from a significant loss. An annuity’s principal protection trades away some of the upside potential a fully market-exposed investment might offer, in exchange for knowing the balance won’t decline due to market performance. That trade-off tends to matter more as the money is needed sooner or as it represents a larger share of someone’s total retirement resources.
Why do annuities with longer surrender periods sometimes offer stronger interest rates?
A longer surrender period means the insurer holds and invests the underlying funds for a longer stretch of time before the owner can access them without penalty. That extended time horizon gives the insurance company more flexibility in how it invests the premium, which can translate into a stronger crediting rate offered to the contract owner in exchange for the longer commitment. Shorter-term contracts generally trade a lower rate for more near-term flexibility.
What actually determines how much monthly or annual income a $750,000 annuity produces?
Three factors combine to set the income amount: the annuitant’s age when income payments begin, the interest rate environment at that time, and the specific payout option selected, such as a fixed number of years versus a lifetime payout. The same $750,000 balance can produce meaningfully different income figures depending on how these three variables line up, which is why an income estimate is only accurate once all three are known rather than assumed.
Does tax deferral make a bigger difference on a $750,000 annuity than on a smaller one?
Yes, in absolute dollar terms. Because interest credited inside an annuity isn’t taxed annually the way it would be in a taxable account, the full balance keeps compounding without yearly tax drag chipping away at the growth. On a balance in the mid six figures, that untaxed compounding builds up a noticeably larger cumulative advantage over a long holding period than the identical benefit would produce on a much smaller starting balance, simply because there’s more principal benefiting from the deferral each year.
Is it risky to put $750,000 into a single annuity rather than spreading it across accounts?
It’s worth thinking through deliberately rather than defaulting to either extreme. Placing a large sum into a single contract concentrates that money with one insurance company and under one set of contract terms, which is a different kind of consideration than market risk — it’s a question of counterparty and structure rather than performance. Many people address this by splitting a large sum across more than one carrier or contract, or by keeping a portion outside annuities entirely in more liquid accounts, so that no single company or contract structure holds the entire balance.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to How Much Does an Annuity Pay? — covering annuity payout calculators, income amounts & interest rates by investment size from 100+ carriers.
Last Reviewed: September 1, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
