
Life Insurance on Suboxone
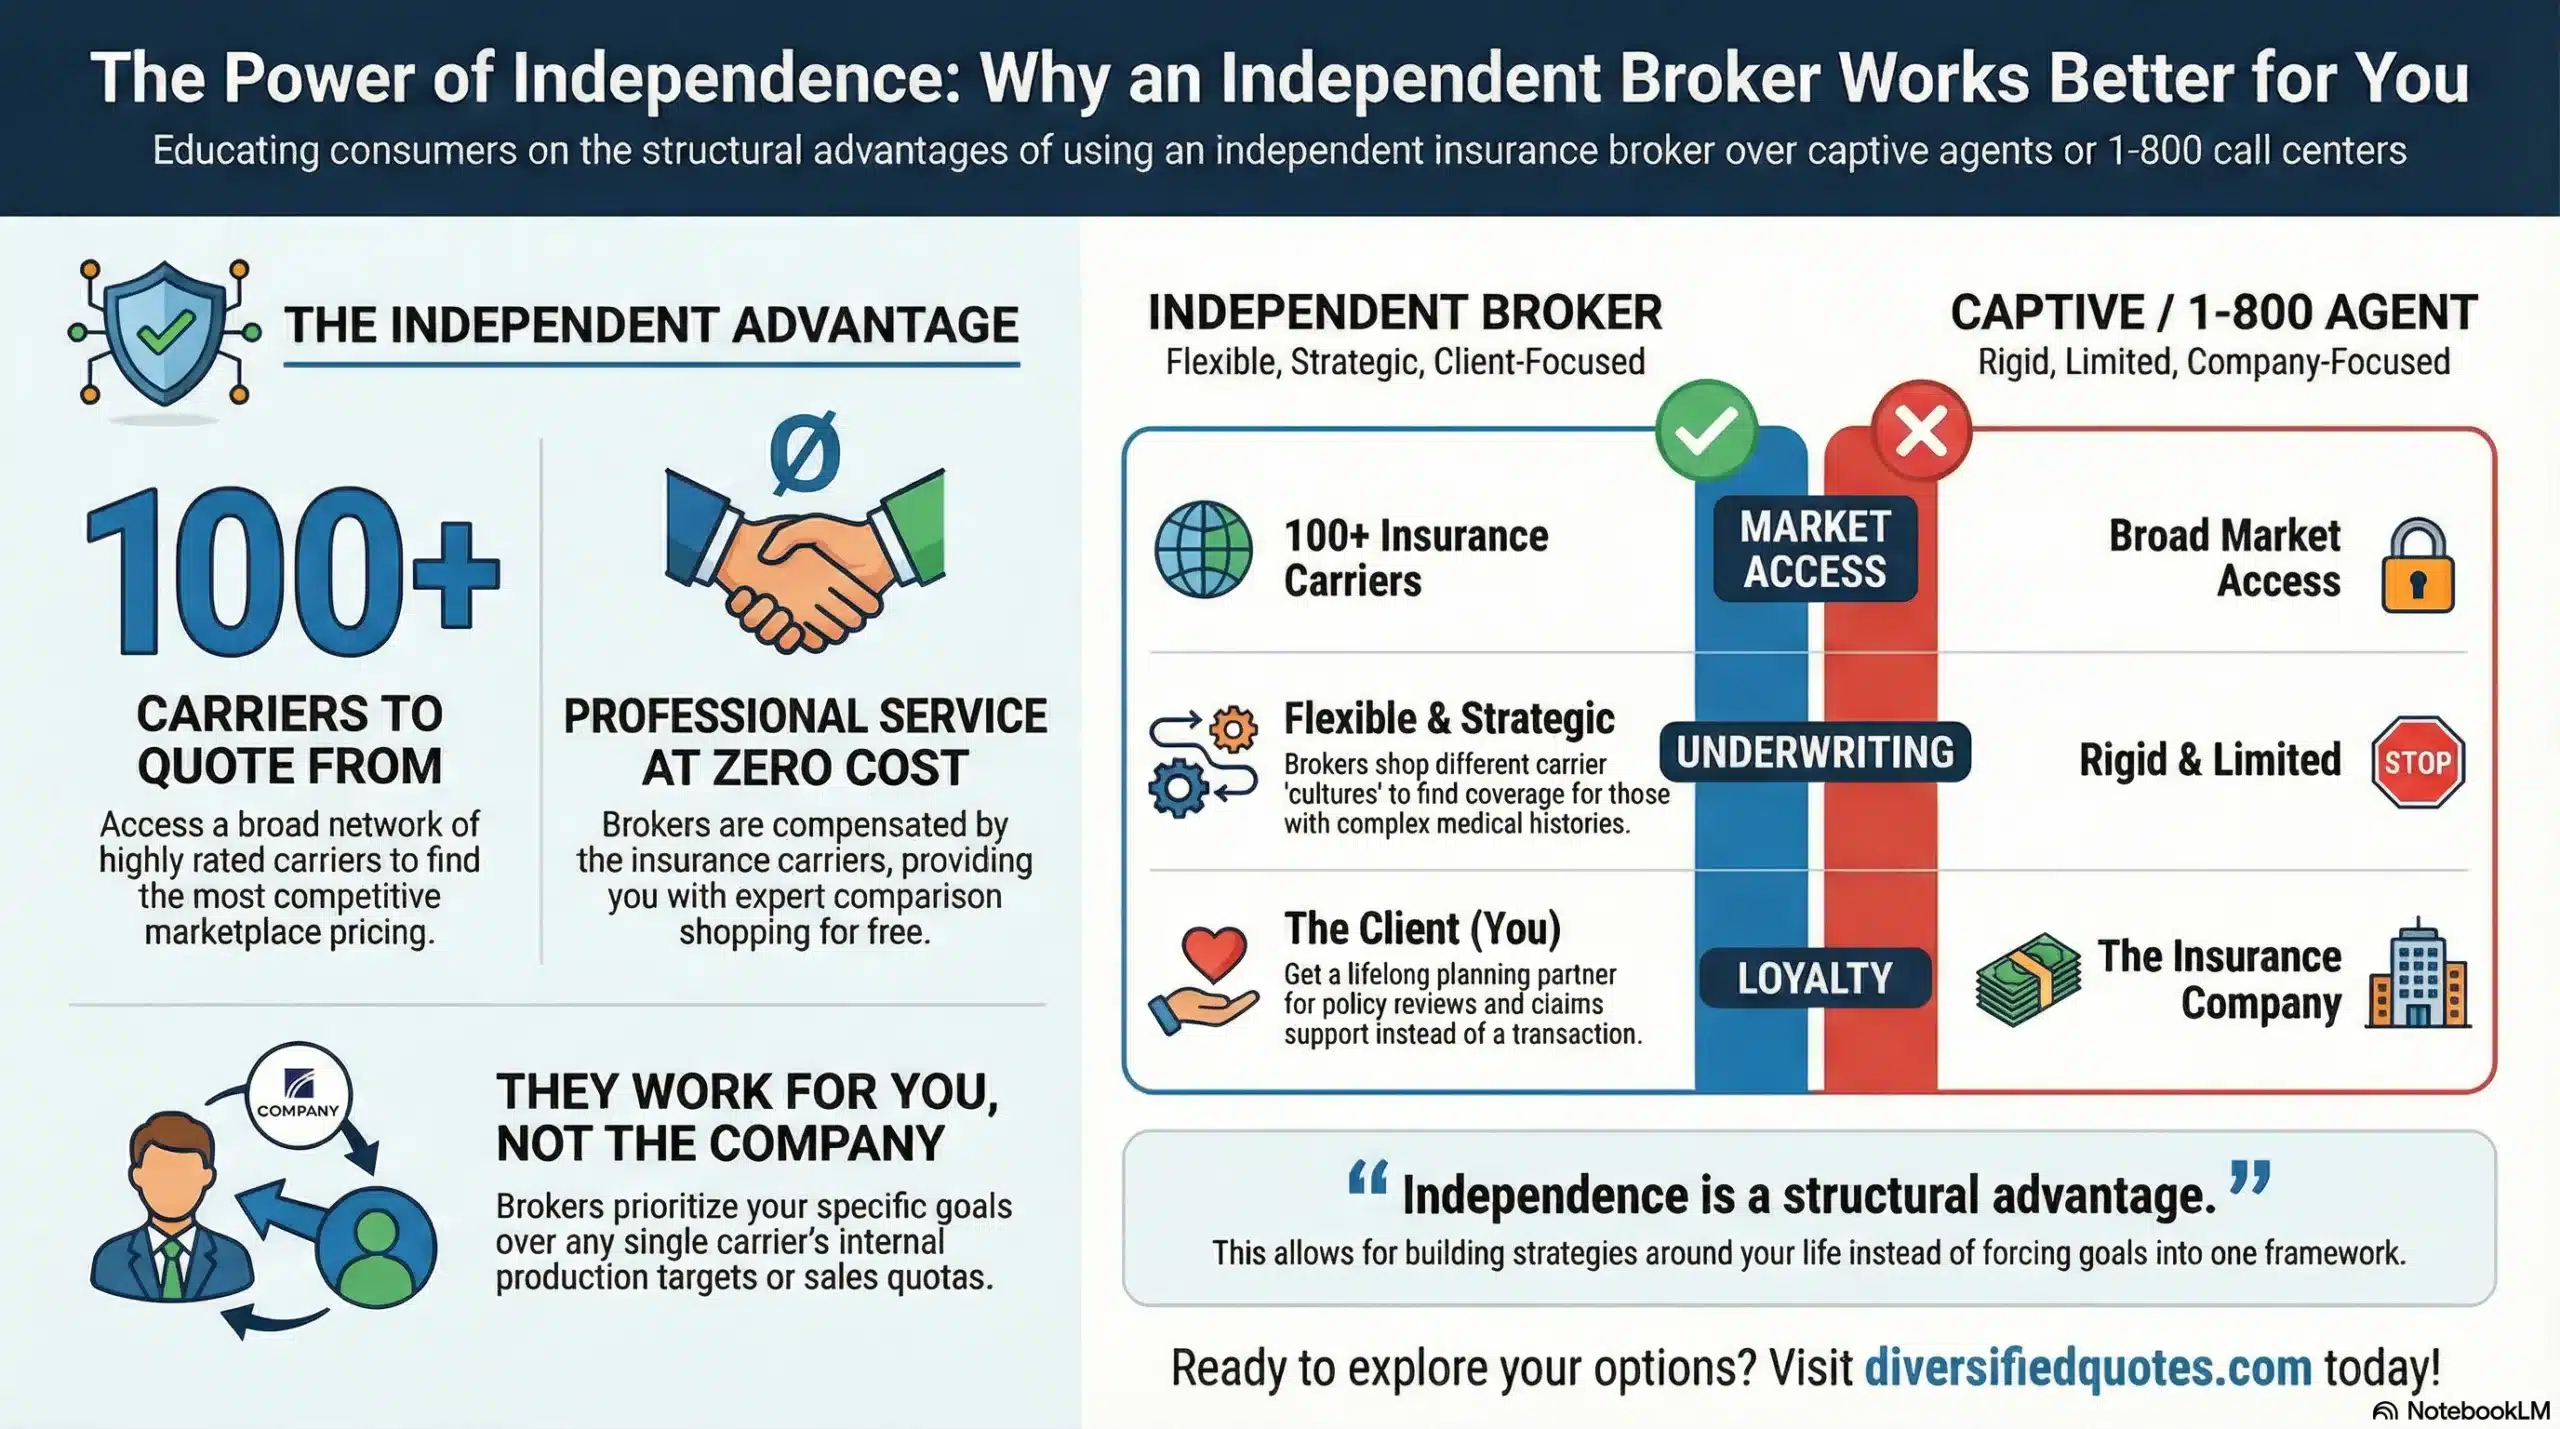
As an Independent Life Insurance Broker, we compare rates across 100+ carriers and prescreen every application before submission.
Life Insurance on Suboxone
Jason Stolz CLTC, CRPC, DIA, CAA
Suboxone is one of the most difficult histories to place with a traditional life insurance carrier, and there’s no honest way to soften that. Suboxone, the brand name for buprenorphine combined with naloxone, is the standard of care for treating opioid use disorder — a genuinely effective, medically respected treatment. But most fully underwritten carriers classify it as active treatment for a substance use disorder, which typically means an automatic decline while you’re taking it, followed by a required waiting period of roughly three years after treatment ends before standard underwriting will even reconsider the application. After the postpone period, our 25 Years of underwriting experience shows that a Table 6 rate class is an estimated final rating. That’s the reality most people run into first. It is not, however, the end of the conversation.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this is a case type our office handles directly and regularly, with two real, specific paths to real coverage while that three-year window is still running. As an independent broker working across dozens of carriers, we know precisely which companies will consider a Suboxone history today, on what terms, and how to structure an application correctly the first time.
Currently on Suboxone or a similar medication and need real coverage options? Let’s talk directly and confidentially.
Talk to a Life Insurance Specialist
| Path | Carrier | Key Condition |
|---|---|---|
| Standard fully underwritten carriers | Most carriers | Active use is typically declined; roughly a 3-year wait after discontinuation before reconsideration |
| Personal term or whole life while on Suboxone | Assurity Life (A Rated) | Must be working at least 20 hours per week at the time of application |
| No face amount limit, employer-structured Key Person coverage | Petersen International (A+ Rated) | Structured as Key Person coverage, with a separate agreement directing proceeds to your chosen beneficiary |
Outcomes above reflect our firm’s direct placement experience with these specific carriers and are not a quote or a guarantee; actual results depend on the complete file and current carrier guidelines.
See Real-Term Rates Side by Side
Life Insurance Quoter
What Suboxone Is, and Why Carriers Treat It the Way They Do
Suboxone combines buprenorphine, a partial opioid agonist, with naloxone, an opioid receptor blocker, and it’s the FDA-approved standard of care for medication-assisted treatment of opioid use disorder. It works, and it’s helped a great many people rebuild stable, healthy lives. None of that is in question.
What matters for life insurance underwriting is simply how most fully underwritten carriers are built to classify it: not as a resolved, historical condition, but as an indicator of active treatment for a substance use disorder, regardless of how stable or successful that treatment currently is. That classification is why the standard industry pattern involves a decline during active use, followed by a waiting period, commonly cited in the range of one to three years from the point treatment ends, before traditional underwriting will reconsider the case at all. This isn’t a judgment about the person — it’s simply how most standard underwriting guidelines are currently structured around this specific medication class.
Why Most Agents Default Straight to Guaranteed Issue — And What That Actually Costs You
Here’s what typically happens when someone with a Suboxone history goes to an agent who doesn’t specialize in cases like this: rather than knowing which specific carriers will actually consider a real, fully underwritten policy, the agent defaults straight to guaranteed issue whole life. It’s an understandable default — guaranteed issue asks no health questions and accepts nearly everyone automatically, so it feels like the safe, guaranteed answer for anyone who looks hard to place. But it’s rarely the best answer, and most people never find out what it actually costs them until it’s too late to matter.
Guaranteed issue policies almost always come with a graded death benefit, and this is the detail that gets glossed over or missed entirely. If death occurs from natural causes during the graded period, typically the first two to three years the policy is in force, the beneficiary doesn’t receive the full face amount at all. Instead, they generally receive only the premiums that were paid in, sometimes with a modest amount of interest added. The full face amount only becomes payable for a natural-cause death after that graded period has fully elapsed. Accidental death is usually the one exception, typically covered at the full amount from day one — but for the far more common scenario of a natural-cause death, a family relying on a graded policy during those first two or three years may receive only a small fraction of what they were counting on.
This is precisely why the two paths outlined above matter as much as they do. Both Assurity and Petersen International offer real, fully underwritten coverage with an immediate, non-graded death benefit — meaning the full face amount is payable from the day the policy takes effect, for any covered cause of death, not just accidental ones. A family isn’t left exposed during a multi-year grading period simply because the agent they worked with didn’t know these carriers would consider the case. Knowing that these options exist, and knowing how to structure an application correctly for either one, is the difference between a policy that actually protects your family from day one and one that quietly doesn’t, for years, without anyone telling you clearly why.
Option One: Personal Coverage Through Assurity, While You’re Still in Treatment
Assurity Life, rated A by AM Best, is one of the real carriers we work with that will consider both term and whole life coverage for an applicant currently on Suboxone or a similar medication, without waiting for the standard postponement period to run out. The core condition is straightforward: the applicant needs to be working at least 20 hours per week at the time of application. It is critical to understand this is NOT one of Assurity’s “shelf” products. It is a limited distribution policy offered by a select handful of advisors, of which we are part of.
There’s a specific timing mechanic worth understanding clearly before you apply, since it affects exactly when your coverage actually takes effect. Assurity issues this type of case on the second “first of the month” following application, not the first one. In practice, that means an application completed in August is issued effective October 1st. An application completed in September is issued effective November 1st. The pattern continues the same way month to month. This isn’t a delay caused by anything going wrong with your file — it’s simply the standard processing timeline built into how this specific case type is issued.
| Product | Available Terms | Maximum Face Amount |
|---|---|---|
| Term Life | 10-year, 20-year, or to age 70 | $150,000 |
| Whole Life | Permanent, lifetime coverage | $100,000 |
These two products can be combined, giving a maximum combined face amount of $250,000 across both policies — though electing both is entirely optional, not a requirement. A term-only or whole-life-only application is equally valid, depending on what actually fits your goals.
If Assurity looks like the right fit based on what’s outlined here, you can move directly to a quote and application through our dedicated portal for this specific case type.
Quote and Apply for Assurity Coverage
Option Two: Petersen International — No Face Amount Limit, Structured Through Your Employer
For applicants who need coverage well beyond what a standard personal policy can offer, Petersen International, rated A+ by AM Best, will consider Suboxone histories through a genuinely different structure: a Key Person life insurance policy. This structure looks different from a typical personal policy, and it’s worth understanding exactly how it works before assuming it functions the same way.
Under a Key Person arrangement, you are the insured, but your employer is both the owner of the policy and the named beneficiary — not you or your family directly. What makes this genuinely useful for your personal protection goals is a separate agreement that can be put in place alongside the policy: if a claim is ever paid, this agreement obligates the employer to then pay those benefits through to whoever you’ve designated, whether that’s a spouse or another beneficiary of your choosing. The employer isn’t required to establish this kind of pass-through arrangement — it’s not automatic or mandated — but once it’s put in place and signed by an authorized officer of the company, that signed agreement is what creates the obligation to direct the proceeds to your chosen beneficiary rather than simply retaining them as a business asset.
The genuine advantage of this path is capacity: there is no stated face amount limit, and Petersen will consider coverage into the multiple millions for the right case. This is a fundamentally different scale than what a personal policy through most carriers, including Assurity, can offer for this specific medical history.
Because this structure involves real corporate documentation, not just a personal application, it needs to be set up correctly from the start. If you’d like us to work up an actual quote on this option, we’ll need some basic information about your employment situation and the coverage amount you’re considering — reach out directly and we’ll walk through exactly what’s needed.
Interested in exploring the Petersen International Key Person structure for larger coverage amounts?
Request a Petersen International Quote
Choosing Between the Two Paths
These two options serve genuinely different needs, and the right one depends on how much coverage you’re actually looking for and how you want the policy structured. If a face amount in the range of $100,000 to $250,000 meets your needs, and you want a policy you personally own and control from day one, Assurity is generally the more straightforward path, with a clear, known timeline to an issued policy. If your need is significantly larger, or you’re comfortable with the employer-owned structure in exchange for meaningfully higher capacity, Petersen International’s Key Person approach is the path built for that. Some clients pursue Assurity now for a personally owned base amount, and separately look at the Petersen structure to layer on additional coverage beyond what a personal policy could otherwise provide during this window.
After the Three-Year Window Closes
Once roughly three years have passed since Suboxone treatment ended, standard fully underwritten carriers generally become willing to reconsider an application on their normal terms, provided the intervening period shows genuine stability and no relapse or additional treatment. At that point, the options available typically broaden considerably beyond the two paths described here, and a fresh comparison across the standard market becomes worthwhile. Our overview of applying with a pre-existing condition history covers this general pattern in more depth.
How We Help
This is a case type where knowing exactly which carriers will actually consider the file, and under what specific conditions, makes the difference between a wasted application and a placed policy. We’ll help you determine which of these two paths genuinely fits your situation, walk you through the Assurity timing mechanics or the Petersen documentation requirements in detail, and make sure the application is built correctly from the first submission rather than risking a decline that could complicate a future application elsewhere.
Our broader guidance on choosing the right policy and how much coverage you need applies here just as it would to any case — the goal is real, appropriate protection for your family, not simply the first offer that comes back. If you’d like to understand why working with an independent broker matters for a case this specific, that’s worth a direct, confidential conversation.
Ready to find out which path actually fits your situation?
Get Your Life Insurance Review
Financial Protection Essentials
Explore policy types, retirement distribution strategies, and beneficiary planning.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Can I get life insurance while I’m currently taking Suboxone?
Not through most standard, fully underwritten carriers — active Suboxone use is typically treated as an automatic decline while it’s ongoing. However, real options do exist. Assurity Life will consider personal term or whole life coverage for an applicant currently on Suboxone, provided they’re working at least 20 hours per week at the time of application. Petersen International will also consider larger amounts through a Key Person coverage structure. Both are genuine, active options, not workarounds.
Why do most carriers automatically decline Suboxone use?
Most fully underwritten carriers classify Suboxone, which combines buprenorphine and naloxone, as an indicator of active treatment for a substance use disorder, regardless of how stable or successful that treatment currently is. This classification, not a judgment about the individual, is what drives the typical decline during active use, followed by a waiting period commonly cited in the range of one to three years after treatment ends before standard underwriting will reconsider the case.
How long is the waiting period after stopping Suboxone before I can apply normally?
Most standard carriers require roughly three years from the end of treatment before reconsidering a fully underwritten application, though the exact timeline can vary by carrier. Coverage doesn’t need to wait for that window to close, though — Assurity and Petersen International both offer real paths to coverage during that period.
Why does my Assurity policy get issued on the first of a future month instead of right away?
Assurity issues this specific case type effective on the second “first of the month” following your application date, not the first one. An application completed in August is issued effective October 1st; one completed in September is issued effective November 1st, and the pattern continues the same way each month. This is a standard processing timeline for this case type, not a sign that anything is wrong with your application.
How much coverage can I actually get through Assurity with a Suboxone history?
Up to $150,000 in term coverage, available in 10-year, 20-year, or to-age-70 terms, and up to $100,000 in whole life coverage. Both can be combined for a maximum of $250,000 total, though taking both products is entirely optional depending on what fits your specific needs.
How does the Petersen International Key Person structure actually work?
You are the insured, but your employer owns the policy and is named as the beneficiary, not you or your family directly. A separate agreement can be put in place obligating the employer to pass the benefit through to a beneficiary of your choosing, such as a spouse, if a claim is ever paid. The employer isn’t required to establish this arrangement, but once it’s signed by an authorized officer of the company, that agreement creates the obligation. This structure allows for significantly higher coverage amounts, with no stated face amount limit, than a personal policy typically permits for this medical history.
Which option is better for me, Assurity or Petersen International?
It depends on how much coverage you need and how you want it structured. If $100,000 to $250,000 meets your needs and you want a policy you personally own from day one, Assurity is generally the more straightforward path. If you need significantly more coverage and you’re comfortable with an employer-owned structure in exchange for that higher capacity, Petersen International’s Key Person approach is built for that. Some applicants pursue both, using Assurity for a personally owned base amount and Petersen to layer on additional coverage.
What happens once the standard three-year waiting period is over?
Standard fully underwritten carriers generally become willing to reconsider an application on their normal terms at that point, provided the intervening years show genuine stability with no relapse or additional treatment. At that stage, the range of available options typically broadens considerably beyond the two specific paths described here, and a fresh comparison across the standard market becomes worthwhile.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for Mental Health & Substance Use — covering depression, PTSD, ADHD, bi-polar disorder, and substance use from 100+ carriers.
Last Reviewed: September 15, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
