
Life Insurance for Ewings Sarcoma
Life Insurance for Ewings Sarcoma
Jason Stolz CLTC, CRPC, DIA, CAA
Ewing sarcoma is overwhelmingly a diagnosis of childhood and adolescence, which means something important: the person reading it is far more likely to be an adult who survived this cancer decades ago than someone currently navigating active treatment. That distinction changes the entire underwriting conversation. For most cancers we cover on this site, the central question is how recently someone was treated. For Ewing sarcoma, once enough time has passed, the more decision-relevant question often becomes something almost nobody expects: not whether the cancer came back, but what the treatment that cured it may have left behind.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers and has placed coverage for adult survivors of childhood cancers regularly enough to know that a Ewing sarcoma history from twenty or thirty years ago requires a genuinely different conversation than a recent diagnosis does. As an independent broker working across dozens of carriers, our office knows which survivorship records actually move a long-term Ewing sarcoma case toward favorable rates, and we can run a confidential prescreen across multiple carriers before any formal application puts a decision on your record.
A Ewing sarcoma survivor navigating life insurance and want an honest read on your options? Let’s talk.
Talk to a Life Insurance Specialist
| Your Situation | What It Typically Means | What Helps Right Now |
|---|---|---|
| Recently diagnosed, in active treatment | Fully underwritten coverage is not realistic yet — this is standard for any active cancer treatment, not specific to Ewing sarcoma | Guaranteed issue coverage is available immediately as a bridge |
| Treatment completed, 2–5 years out, clean surveillance imaging | Recurrence risk is falling but still the dominant concern at this stage — most relapses occur within this window | Gather oncology follow-up notes and imaging reports showing continued remission |
| 5–10 years since treatment, no recurrence | A genuinely strong file at many carriers — this is often where standard or near-standard rates become realistic | Add survivorship care records: echocardiogram results, any secondary-cancer screening |
| 10–25+ years since treatment, adult survivor, no recurrence | Recurrence risk is now low, but treatment late effects — not the original cancer — become the more relevant underwriting question | Documentation of ongoing cardiac monitoring and secondary-malignancy screening carries real weight |
| Treatment included radiation therapy | A distinct, separately evaluated long-term consideration due to radiation-associated secondary malignancy risk | Confirm whether radiation was part of your specific treatment plan and document ongoing screening |
| Diagnosed and treated under an older treatment protocol (pre-2000s) | Modern protocols were refined partly because of what was learned about late effects in earlier treatment eras | Obtaining your original treatment summary, not just a diagnosis label, matters more here than for a recently treated case |
Outcomes above reflect general, well-documented underwriting patterns and are not a quote or a guarantee; actual results depend on the complete file and the specific carrier.
See Real-Term Rates Side by Side
Life Insurance Quoter
What Ewing Sarcoma Actually Is
Ewing sarcoma is a malignant tumor arising in bone or soft tissue, most commonly diagnosed in children, adolescents, and young adults, typically between the ages of 10 and 20, though it can occur in adults as well. It’s genetically distinctive in a way that matters for accurate diagnosis: the large majority of cases carry a specific chromosomal translocation, most often between chromosomes 11 and 22, producing a fusion gene called EWSR1-FLI1. This molecular signature is what confirms the diagnosis definitively, distinguishing it from other bone and soft tissue tumors that can look similar under a microscope alone.
Why “Years Since Diagnosis” Means Something Different Here
For most cancers, the underwriting conversation is straightforward in structure even when the medicine is complex: the longer someone has gone without recurrence, the more favorably they’re viewed, and eventually the diagnosis stops meaningfully affecting the case at all. Long-term outcome data on Ewing sarcoma survivors, gathered through the Childhood Cancer Survivor Study, a large research effort following people treated for cancer as children, tells a more layered story, and it’s worth understanding clearly rather than assuming it works the same way as other conditions.
Among people who survived at least five years past their Ewing sarcoma diagnosis, researchers found that roughly 60% of deaths occurring after that five-year mark were still attributable to the original cancer recurring or progressing. But the remaining 40% were not related to the original cancer coming back at all — they were attributable to other causes, most notably second cancers, accounting for about 14% of these deaths, and cardiac disease, accounting for about 6%. This is the single most important thing to understand about long-term Ewing sarcoma survivorship from an underwriting standpoint: past a certain point, the treatment that cured the disease becomes its own independent, separately relevant factor.
Late Effects: The Part of This Story Most People Never Hear
Ewing sarcoma treatment has historically involved a combination of surgery, chemotherapy, and, in many cases, radiation therapy, and each of these carries its own long-term considerations well beyond the original tumor. Chemotherapy regimens for Ewing sarcoma have commonly included anthracycline drugs, which are genuinely effective against the cancer but carry a recognized long-term cardiac risk — the same research found cardiac-related mortality substantially elevated among survivors compared to the general population, tied specifically to this treatment exposure.
Radiation therapy, when used for local tumor control, carries its own distinct long-term consideration: an elevated risk of a second, treatment-related cancer developing years or decades later within or near the treated area, including secondary bone or soft tissue sarcomas. Across the full survivor population studied, the cumulative likelihood of developing a second cancer, not counting common non-melanoma skin cancers, reached roughly 9% by twenty-five years after the original diagnosis. This is precisely why confirming whether radiation was part of a specific treatment plan, and what ongoing screening has looked like since, is genuinely important information for a long-term survivor’s file — it’s a different risk category entirely from the original cancer, and it deserves to be evaluated as its own line item rather than assumed away simply because the original tumor never returned.
Why Treatment Era and Protocol Genuinely Matter
Two people can both be twenty-year Ewing sarcoma survivors and be carrying meaningfully different long-term risk profiles, depending on exactly how they were treated. Treatment protocols have evolved substantially over the decades, partly in direct response to what long-term follow-up studies revealed about late effects in earlier treatment eras — modern chemotherapy dosing, radiation planning, and cardiac monitoring practices generally reflect lessons learned from exactly the kind of survivor data described above. A survivor treated under a more contemporary protocol may carry a different, sometimes more favorable, late-effect risk profile than someone treated decades earlier under an older regimen, even with an identical original diagnosis and an identical number of years in remission.
This is exactly why the original treatment summary, not just the diagnosis and the fact of long-term survival, is worth having in hand. Which specific chemotherapy agents were used, whether radiation was part of the plan, and what the total treatment exposure looked like are all genuinely relevant details that a bare “Ewing sarcoma, cancer-free since [year]” statement doesn’t capture.
Have your original treatment summary and recent survivorship follow-up records? Let’s see what they mean for your application.
Get a Confidential Case Review
Putting the Numbers in Honest Context
It’s worth being direct about what these statistics do and don’t mean, because relative risk figures like these can sound more alarming out of context than they should. Researchers describe long-term Ewing sarcoma survivors as having meaningfully elevated mortality compared to the general population when measured as a ratio — but a ratio applied to the very low baseline mortality risk of someone in their twenties, thirties, or forties still generally translates to a low absolute annual risk in most individual cases, particularly for a survivor with clean, well-documented follow-up care and no evidence of recurrence or emerging late effects. The honest takeaway isn’t “elevated risk forever regardless of anything else” — it’s that ongoing survivorship monitoring is genuinely valuable, both for your health and for how a well-documented file gets evaluated, and that the risk profile continues to depend on individual factors like treatment history and follow-up care quality rather than settling into a single fixed number for everyone who shares the same original diagnosis.
It’s also worth knowing honestly that long-term follow-up research on this population has found that risk for late mortality and new health conditions doesn’t simply flatten out at some fixed point decades out — continued monitoring remains medically appropriate throughout a survivor’s life, which is exactly why an underwriter reviewing a long-term case will generally want to see evidence that this monitoring has actually continued, not just that a long time has passed since treatment ended.
Building the Strongest Possible File
A handful of specific records make a disproportionate difference in how a Ewing sarcoma survivorship case gets evaluated. First, the original treatment summary: diagnosis details, the specific chemotherapy regimen used, and whether radiation therapy was part of local tumor control. Second, recent survivorship care documentation — an echocardiogram or other cardiac function assessment, particularly for anyone treated with anthracycline chemotherapy, and any secondary-cancer screening that’s been performed, especially for anyone whose treatment included radiation. Third, current oncology or survivorship clinic follow-up notes confirming ongoing monitoring and no evidence of recurrence or new concerns. A file built on these specifics gives an underwriter a genuinely complete picture, rather than asking them to make assumptions from a diagnosis code and a number of years.
Realistic Rate Class Expectations
For an adult survivor five to ten years past treatment with clean follow-up imaging and no recurrence, standard rates or a modest table rating are a realistic outcome at many carriers. Survivors well beyond ten years out, with documented ongoing cardiac and secondary-malignancy screening showing no concerns, frequently see even more favorable consideration, since the strongest evidence available — sustained, monitored, clean survivorship — is exactly what a well-documented long-term file can demonstrate. A more recent diagnosis, or a case where treatment records or follow-up screening are incomplete, is more likely to see a table rating or a request for additional documentation, which is a request for more information, not a decline. Our broader overview of how rate classes work and what actually drives your premium cover this system in more depth.
Coverage Available While You Build That File
If you’re newly diagnosed, still in treatment, or simply haven’t gathered your full survivorship record yet, you don’t need to go without protection in the meantime. Simplified underwriting and guaranteed issue coverage remain available immediately regardless of where your case currently stands, and many long-term survivors use exactly this kind of coverage as a bridge while assembling treatment records and pursuing a fully underwritten application in parallel.
If You’ve Already Been Rated or Declined Elsewhere
Carriers vary meaningfully in how current their underwriting guidelines are on long-term childhood cancer survivorship, and a decline or unfavorable rating from one company is genuinely not the final word, particularly for a case involving a diagnosis from decades ago where the relevant clinical understanding has continued to evolve. Our second-opinion review exists specifically for cases like this, and running a confidential prescreen across several carriers before any formal application is filed can identify which company is actually positioned to evaluate a long-term survivorship case fairly.
How We Help
We know how to read a childhood cancer survivorship file the way an underwriter does — which records actually matter for a case this many years out, which carriers have underwriting guidelines that reflect current survivorship research rather than outdated assumptions, and how to find out how a specific carrier is likely to view your case before a formal application ever puts a decision on your record. Before you apply anywhere, we’ll help you assemble the treatment history and follow-up documentation that makes a long-term Ewing sarcoma case genuinely strong, and we’ll run a prescreen across the carriers most likely to evaluate it favorably.
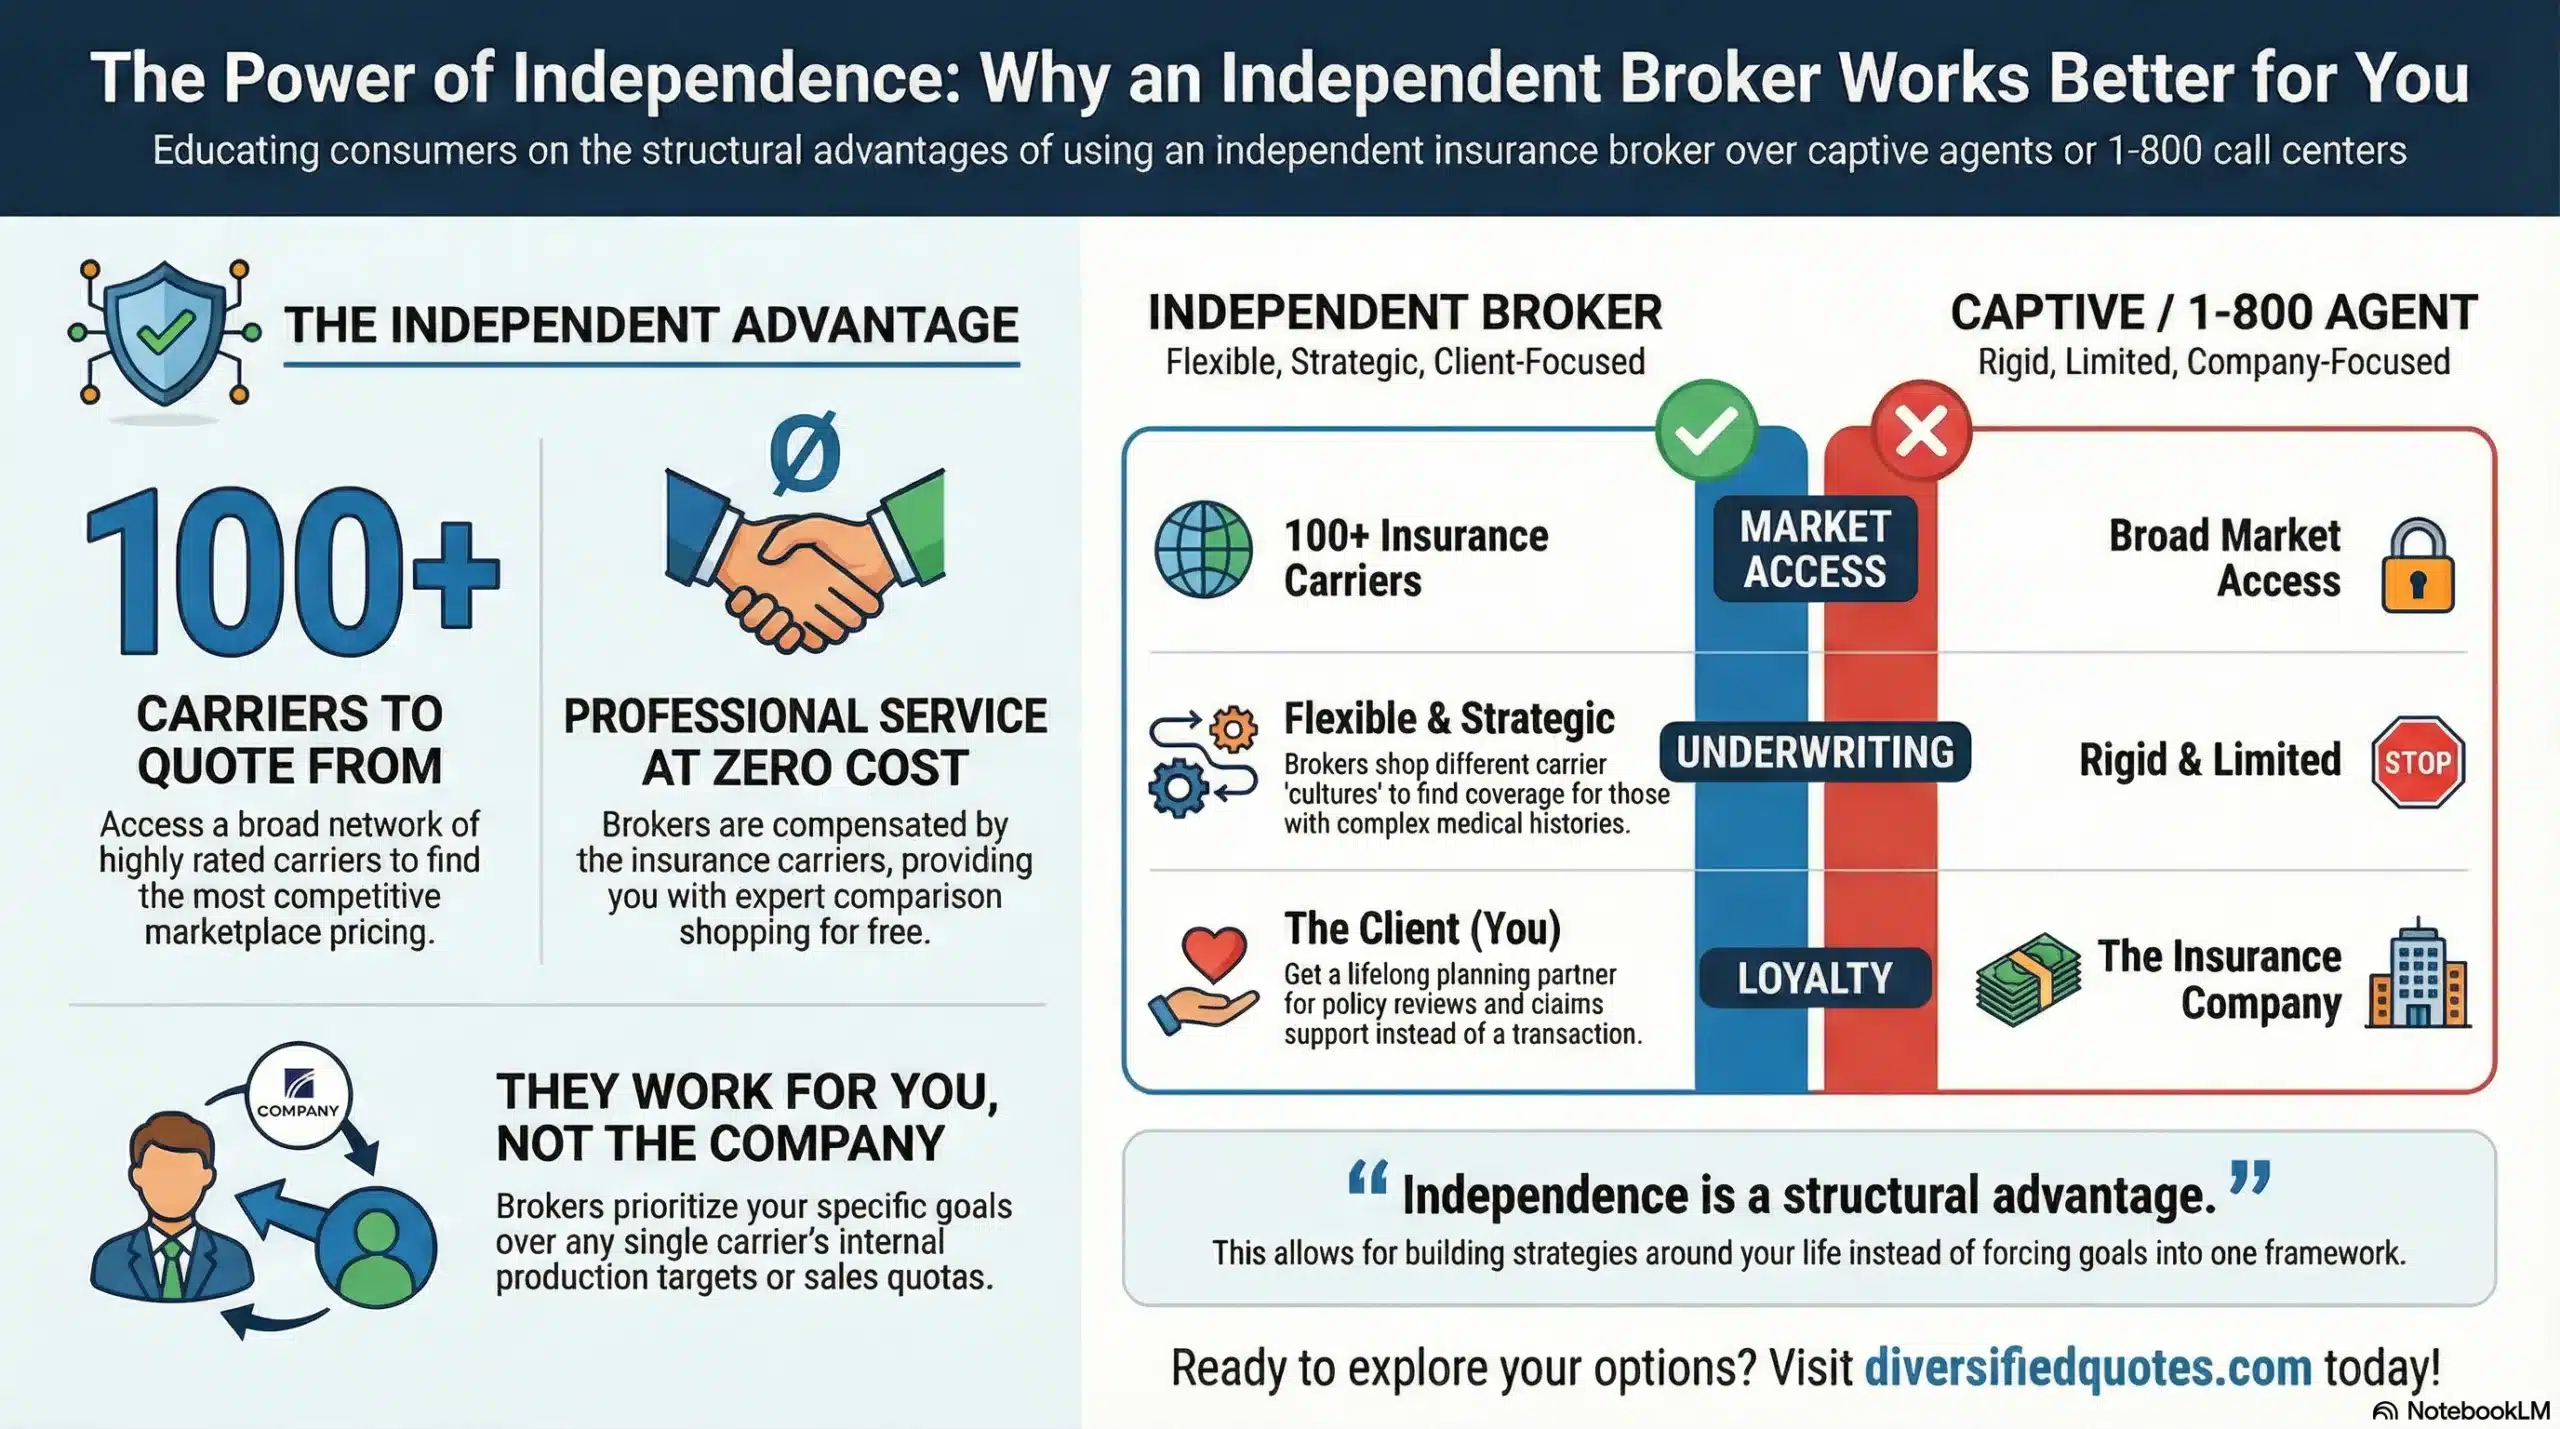
Our guidance on choosing the right policy and how much coverage you need reflects the same principle behind every case we take on: a diagnosis from years or decades ago is one input among several, not the final word on what’s available to you today. If you’d like to understand why working with an independent broker matters for a case like this specifically, that’s worth a direct conversation.
Ready to find out what your survivorship file would look like to an underwriter?
Get Your Life Insurance Review
Financial Protection Essentials
Explore policy types, retirement distribution strategies, and beneficiary planning.
Compare Term Life Insurance Lengths
Explore different term periods to find coverage that best matches your timeline and budget.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Can a Ewing sarcoma survivor get life insurance?
Yes, and for survivors five, ten, or more years removed from treatment with a clean record, often at rates much closer to standard than people expect. Because Ewing sarcoma is overwhelmingly diagnosed in children and teenagers, most people applying for life insurance with this history are adult survivors decades removed from treatment, not people managing an active cancer. Underwriters generally focus on how much time has passed, whether recurrence has occurred, and increasingly, on documented long-term survivorship follow-up care rather than the original diagnosis alone.
Why does the treatment matter as much as the original cancer for a long-term survivor?
Because long-term outcome research shows that past a certain point, treatment-related effects become a significant, independent factor separate from whether the cancer itself returns. Among five-year survivors of Ewing sarcoma studied through the Childhood Cancer Survivor Study, roughly 60% of later deaths were attributable to the original cancer recurring, but the remaining 40% were attributable to other causes, primarily second cancers and cardiac disease linked to the original treatment. This is why a complete survivorship file, not just confirmation that the cancer never returned, matters for long-term cases.
Does chemotherapy for Ewing sarcoma create long-term risks beyond the cancer itself?
Yes. Ewing sarcoma chemotherapy regimens have commonly included anthracycline drugs, which are effective against the cancer but carry a recognized long-term cardiac risk. Research following long-term survivors has found cardiac-related mortality meaningfully elevated compared to the general population, tied specifically to this treatment exposure. This is why an echocardiogram or other cardiac function assessment, particularly for anyone treated with anthracycline-based chemotherapy, is genuinely valuable supporting documentation for a life insurance application.
Does having had radiation therapy affect underwriting differently?
Yes, and it’s evaluated as its own distinct consideration. Radiation therapy used for local tumor control carries a recognized long-term risk of a second, treatment-related cancer developing years or decades later within or near the treated area. Research has found the cumulative likelihood of a second cancer among Ewing sarcoma survivors reaching roughly 9% by twenty-five years after the original diagnosis. Confirming whether radiation was part of a specific treatment plan, and documenting any ongoing secondary-cancer screening, is genuinely important information separate from confirming the original cancer never returned.
Does it matter what specific treatment protocol or era I was treated under?
Genuinely, yes. Ewing sarcoma treatment protocols have evolved substantially over the decades, partly in direct response to what long-term follow-up research revealed about late effects in earlier treatment eras. Two people who are both twenty-year survivors can carry different long-term risk profiles depending on the specific chemotherapy regimen used and whether radiation was part of their treatment plan. This is why obtaining your original treatment summary, not just a diagnosis and a number of years since treatment, is genuinely useful for a long-term survivorship case.
Does the elevated mortality risk for survivors mean my actual chances are poor?
Not necessarily, and it’s worth understanding these figures in context. Researchers describe long-term survivor mortality as elevated relative to the general population using ratios, but a ratio applied to the very low baseline mortality risk of someone in their twenties, thirties, or forties still generally translates to a low absolute annual risk for most individual cases, particularly for a survivor with clean, well-documented follow-up care and no evidence of recurrence or emerging late effects. The relevant factors continue to be individual treatment history and follow-up care quality, not a single fixed outcome that applies identically to everyone who shares the same original diagnosis.
What records should a long-term Ewing sarcoma survivor gather before applying?
Three pieces of documentation make a disproportionate difference: the original treatment summary, including the specific chemotherapy regimen and whether radiation was used; recent survivorship care records, particularly a cardiac function assessment and any secondary-cancer screening performed; and current oncology or survivorship clinic follow-up notes confirming ongoing monitoring and no evidence of recurrence. Together, these give an underwriter a complete picture rather than a diagnosis code and a number of years.
I was declined or rated poorly as a Ewing sarcoma survivor by one carrier. What are my options?
A decline from one company is genuinely not the final word. Carriers vary meaningfully in how current their underwriting guidelines are on long-term childhood cancer survivorship specifically, and a case involving a diagnosis from decades ago is exactly the kind of file where that variation matters most. Running a confidential prescreen across several carriers before a formal application is filed can identify which company is actually positioned to evaluate a long-term survivorship case fairly.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for Cancer — covering breast, colon, cervical, prostate, testicular, skin, and other cancer diagnoses from 100+ carriers.
Last Reviewed: September 5, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
