
Life Insurance with a Defibrillator
As an Independent Life Insurance Broker, we compare rates across 100+ carriers and prescreen every application before submission.
Life Insurance with a Defibrillator
Jason Stolz CLTC, CRPC, DIA, CAA
An implanted defibrillator is an automatic decline with fully underwritten life insurance carriers, no matter how stable your heart is today or how long ago the device was placed. That single fact rules out the traditional term and whole life policies most people shop for. It does not rule out coverage altogether. Two specific paths remain open: a guaranteed issue term policy for people who work at least 20 hours a week, and Failure to Survive coverage through Petersen International Underwriters for key person, business loan, buy-sell, and court-ordered needs. Everything else on this page sits on top of that distinction.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and placing coverage for applicants with defibrillators and other declined cardiac histories is work our office handles regularly. As an independent life insurance broker with access to more than one hundred carriers and specialty markets, our office can tell you quickly which of these options fits your situation, what each one will and will not pay, and how to avoid wasting time on applications that cannot be approved.
Have a defibrillator and need life insurance?
Find My Coverage Options
Life Insurance Options With a Defibrillator
| Option | Who It Fits | Coverage Amounts | Health Review | Who Receives the Benefit |
|---|---|---|---|---|
| Fully Underwritten Term or Whole Life | Not available with a defibrillator | Not applicable | Full medical underwriting; a defibrillator is a decline | Not applicable |
| Guaranteed Issue Term (20 Hours a Week) | Adults through age 70 working at least 20 hours a week | Up to $150,000, with maximums that depend on age | No medical exam or medical underwriting; see how no-exam life insurance works | Your family or other named beneficiaries |
| Guaranteed Issue Whole Life (Same Program) | Working adults who want permanent coverage | Up to $100,000, with maximums that depend on age | No medical exam or medical underwriting | Your family or other named beneficiaries |
| PIU Failure to Survive | Key person, buy-sell, business loan, and court-ordered needs | Based on the documented financial obligation; size the need with our guide on how much life insurance you need | Short application and health questions; no exam; medical exclusions possible | The business, lender, or party owed the obligation |
What a Defibrillator Tells an Underwriter
A defibrillator is a device that delivers an electrical charge to the heart to restore a normal rhythm. According to the National Heart, Lung, and Blood Institute, there are three main types: automated external defibrillators found in public places, implanted cardioverter defibrillators placed in the chest, and wearable cardioverter defibrillators worn as a vest, usually for a short period. When people search for life insurance with a defibrillator, they almost always mean an implanted cardioverter defibrillator, known as an ICD.
An ICD constantly monitors the heart’s rhythm. The American Heart Association describes it as a battery-powered device placed under the skin that tracks heart rate and delivers an electric shock to restore a normal heartbeat when it detects a dangerous rhythm. Many ICDs can also act as pacemakers when the heart beats too slowly.
The reason a device is implanted is what matters to an underwriter. The NHLBI lists the situations in which doctors recommend an ICD, including surviving a cardiac arrest, dangerous arrhythmias found on testing, inherited conditions that cause arrhythmias, arrhythmias that develop during or after treatment for a heart attack, neuromuscular disorders that affect the heart, cardiac sarcoidosis, and poor heart function after a procedure such as bypass surgery. Each of those reasons points to a meaningful risk of sudden cardiac death, and that is the risk life insurance pricing is built around.
Many of the conditions that lead to an ICD have their own underwriting pages on our site, including life insurance for cardiomyopathy, life insurance for sarcoidosis, and life insurance after a heart attack. The difference is that once an ICD is in place, the device itself becomes the deciding factor for fully underwritten carriers, regardless of how the underlying condition might otherwise have been rated.
ICD, Subcutaneous ICD, CRT-D, and Wearable Vests
Several kinds of devices fall under the defibrillator umbrella, and applicants are sometimes unsure which one they have. A traditional ICD is placed in the chest, usually below the collarbone, with wires called leads running through blood vessels to the heart. Mayo Clinic explains that a subcutaneous ICD is placed under the skin at the side of the chest below the armpit instead, and that it is larger than a traditional model. Mayo Clinic also notes the key difference from a pacemaker: a pacemaker prevents dangerously slow heartbeats, while an ICD treats dangerously fast ones.
A CRT-D is a specialized ICD that also coordinates the timing of the heart’s chambers. The NHLBI notes that CRT-Ds are used for people with advanced heart failure, atrioventricular block, or other conditions that require pacing of both lower chambers. A wearable cardioverter defibrillator is different again: it is typically worn for a limited time by people with a short-term high risk of cardiac arrest, such as those recovering from a heart attack or procedure, waiting for an ICD or a heart transplant, recovering from myocarditis, or starting treatment for severe cardiomyopathy.
For life insurance purposes, the label on the device matters less than the reason it was recommended. A pacemaker alone is underwritten very differently, and someone with a pacemaker may still qualify for fully underwritten coverage depending on the underlying condition. If your device both paces and defibrillates, it is a defibrillator for underwriting purposes. If you are unsure which device you have, your device identification card or your cardiologist’s office can confirm it, and that is one of the first things our office will ask.
Why Fully Underwritten Carriers Say No
Most heart conditions are handled through table ratings, where an applicant is approved at a higher premium that reflects the added risk. Our explanation of how life insurance table ratings work covers that system. Applicants seeking life insurance for atrial fibrillation or living with well-managed coronary heart disease, for example, can often be rated rather than declined.
A defibrillator is different. Fully underwritten carriers decline applicants who have an implanted defibrillator, and a better ejection fraction, years without a shock, or a strong cardiologist’s letter does not change that outcome. The device exists because the applicant’s doctors judged the risk of a life-threatening rhythm to be high enough to warrant permanent protection, and carriers price their fully underwritten products on the assumption that the insured does not carry that level of risk.
Applying anyway can make things harder. A decline is recorded and can follow you into later applications, and our guide to getting life insurance after a prior decline explains how that history is handled. Our overview of what disqualifies applicants from life insurance lists other conditions that fall into the same category.
The practical takeaway is simple. With a defibrillator, the most productive use of time is to go straight to the coverage that does not depend on medical approval, and to match each need, whether personal or business, with the product designed for it.
Already been declined because of your ICD?
Show Me What I Qualify For
Information to Gather Before You Apply
Even though the main options for applicants with a defibrillator do not depend on medical approval, a few details make the process faster and help match you to the right coverage. The first is the exact device you have. Your device identification card, issued at implantation, lists the type and manufacturer, and your cardiologist’s office can confirm whether it is a traditional ICD, a subcutaneous ICD, a CRT-D, or a pacemaker without a defibrillator function.
The second is the reason the device was recommended. A device placed after a cardiac arrest, one placed because of a weak heart muscle, and one placed because of an inherited rhythm disorder are all different medical stories, and PIU’s health questions and any exclusion decision may reflect those differences. The third is a short history: when the device was placed, whether it has ever delivered a shock, your current medications, and any hospital stays related to your heart.
For business and court-ordered coverage, the financial documents matter as much as the medical ones. Have a copy of the loan agreement, the buy-sell agreement, the company’s recent financial statements, or the court order ready, since PIU underwrites to the documented obligation. For the 20-hour program, confirm your current work schedule and the coverage amounts and terms you are considering.
Jason reviews all of this with you before anything is submitted. That preparation prevents applications that cannot be approved, shortens the time to coverage, and makes sure each obligation you want to protect is matched with a product that can actually cover it.
Option One: Guaranteed Issue Term for People Working 20 Hours a Week
The first path is a guaranteed issue term life program built around employment rather than health. To qualify, you need to be actively working at least 20 hours per week at the time you apply. There is no medical exam, no blood or urine testing, and no medical underwriting, so a defibrillator, the condition behind it, and the medications you take do not affect approval or price. Our page on guaranteed issue term life insurance covers the program in full.
The term coverage is issued by Assurity Life Insurance Company, which AM Best rates A- (Excellent) with a stable outlook. Term coverage is available up to $150,000, with the maximum available amount depending on age, and you can choose a 10-year or 20-year term. Issue ages run up to 70, and spouse and child riders are available. A guaranteed issue whole life option of up to $100,000, also with age-based maximums, is available through the same program for people who want coverage that does not end at a set date.
Enrollment includes a few eligibility questions rather than a health review. Applicants who are currently hospitalized, in hospice care, or living in an assisted living or nursing facility are not eligible, and certain high-risk occupations and activities are excluded. For someone with an ICD who is working and living independently, those eligibility rules are usually the only hurdle.
Two points deserve attention before enrolling. First, term coverage runs for the period you choose and then ends, so the 10-year or 20-year choice should match how long your family would depend on the coverage. Second, some guaranteed issue products pay a reduced benefit for natural-cause deaths during the first years of coverage, so our office confirms how the death benefit applies in your state before you enroll.
Get a Guaranteed Issue Quote Through Live Well USA
No medical exam and no health review. If you work at least 20 hours a week, you can see term coverage up to $150,000 or whole life up to $100,000 based on your age. Live Well USA membership is required and carries a monthly fee.
See My Live Well QuoteThe Live Well USA Membership Requirement
The 20-hour guaranteed issue program is offered through a membership association called Live Well USA, and membership is required both to enroll and to keep coverage in force. The membership carries a monthly fee that is paid in addition to the life insurance premium. That fee is part of the true cost of coverage and should be included when comparing this option with anything else.
Membership also matters for keeping the policy. If the membership lapses, the coverage tied to it can be affected, so the membership dues should be set up with the same automatic payment as the premium. Families sometimes overlook a small monthly charge, and with a guaranteed issue policy that may be impossible to replace, losing coverage over a missed membership payment would be a costly mistake.
The membership is simply the vehicle through which this coverage is offered, and for an applicant with a defibrillator, that arrangement is what makes approval possible without a health review. Our office walks every enrollee through the membership terms, the fee, and the payment setup so that nothing about the arrangement is a surprise later.
Matching the 20-Hour Program to Your Family’s Needs
A guaranteed issue limit of $150,000 will not replace a large income for decades, but it can do a great deal of good. It can pay off a car loan or a meaningful share of a mortgage, cover funeral and final medical costs, replace a year or more of income for a surviving spouse, or fund part of a child’s education. For many families affected by heart disease, having that protection in place matters more than the precise amount.
Choosing between the 10-year and 20-year terms depends on what you are protecting. A 10-year term costs less and suits shorter obligations, such as the remaining years on a loan or the period until children finish school. A 20-year term costs more but protects a family over a longer stretch, which may be important when coverage cannot be bought again later. Because the maximum available amount varies with age, applying sooner may also secure a higher limit.
The whole life option fills a different role. Coverage up to $100,000 that does not end at a set date suits final expenses, a small inheritance, or protection for a spouse later in retirement. Some households combine the two, using term coverage for the years when obligations are highest and whole life for a lasting benefit. Jason can lay out both options at the amounts available for your age so you can see the premium, the membership fee, and the coverage side by side.
Option Two: Petersen International’s Failure to Survive Coverage
The second path serves a different purpose. Petersen International Underwriters, known as PIU, is a Lloyd’s of London coverholder that offers Failure to Survive coverage, a form of contingent insurance that pays a financial obligation if the insured person dies during the coverage period. PIU describes it as designed for key person, buy-sell, contract guarantee, and business loan situations, as well as divorce decrees and alimony or child support court orders.
Failure to Survive coverage is not a substitute for personal life insurance, and PIU says plainly that it cannot be used as an alternative to personal-benefit life insurance. The benefit goes to the business, lender, or other party that has a documented financial interest in your survival, and the amount is tied to that interest. What makes it useful for someone with a defibrillator is the underwriting approach. Applications do not require a medical exam, blood work, or urinalysis, and PIU’s guidelines are more flexible than traditional carriers for medically substandard applicants, including those with cardiac conditions.
Applications are short. They include a brief set of health and lifestyle questions along with financial justification, such as the business’s financial history for key person coverage, a copy of the loan agreement for loan coverage, or the written agreement or court order for contractual coverage. Coverage is generally written for terms of up to five years, with shorter terms available, and renewals can be considered if the need continues. PIU reports that cases are commonly ready to issue within days rather than weeks.
For a business owner, a borrower, or someone under a court order, this can solve a problem that otherwise has no answer. The sections below explain how each type of coverage works.
Key Person and Buy-Sell Protection
Businesses depend on certain people, and lenders, partners, and investors know it. Key person coverage protects a company against the financial loss that follows the death of an owner or employee whose skills, relationships, or knowledge drive revenue. Our guide to key person insurance for business explains how the need is typically measured, and PIU’s key person application asks for the company’s recent revenue and profit history and the insured’s role to justify the amount.
Buy-sell coverage funds an agreement among co-owners. If one owner dies, the business or the surviving owners use the proceeds to buy the deceased owner’s share from their estate at an agreed value, which keeps the company in the hands of the people running it and gives the family fair value. Our overview of buy-sell life insurance covers how these agreements are structured.
For a business owner with a defibrillator, the usual approach of buying fully underwritten term coverage on each owner is closed. A Failure to Survive policy written to the value of the agreement or the key person’s financial contribution can fill that gap. Because coverage is generally limited to five-year terms, it works best alongside a plan to review the agreement and renew coverage as the business changes. Our page on life insurance for business owners covers the broader planning picture.
Bank Loans and Lender Requirements
Lenders frequently require life insurance on the owners or guarantors of a business loan, and the policy is assigned to the lender so the loan is repaid if the borrower dies. For an applicant with an ICD, that requirement can hold up or even derail financing, because the borrower cannot obtain the fully underwritten coverage most lenders expect to see.
PIU’s loan indemnification coverage is designed for exactly this situation. The benefit is limited to the loan balance, the lender is the assignee and policy owner, and the application consists of a short form along with a copy of the loan agreement. No medical exam or medical records are required to apply, although the application asks health questions. Coverage terms run up to five years, with renewal possible if the loan extends beyond that. Our page on business loan life insurance explains how lenders typically structure these requirements.
Timing matters with loans. Closing dates are often fixed, and a borrower who discovers late in the process that traditional coverage is unavailable can lose valuable time. Contacting our office as soon as a lender mentions a life insurance requirement allows us to confirm whether the lender will accept Failure to Survive coverage and to prepare the application while the rest of the closing moves forward.
Divorce Decrees and Court-Ordered Coverage
Divorce settlements often require one former spouse to carry life insurance that protects alimony or child support if the paying spouse dies. A defibrillator can make that requirement impossible to meet through ordinary policies, which can create legal and financial pressure on top of an already difficult situation. Our guide to life insurance required by court order explains how these obligations usually work.
PIU’s Confidential Failure to Survive plan can be written to protect contractual obligations between two parties, and PIU specifically notes that an ex-spouse can be covered to protect alimony or child support payments. A written agreement or court order serves as the core of underwriting, and PIU states that coverage can be issued without a medical exam. Current spouses cannot be insured under this plan because of moral hazard concerns, so the coverage applies once the obligation arises from a divorce or separation agreement.
Because court orders often specify an amount and duration, the details of the order should be reviewed before an application is submitted. Coverage written for five-year terms may need to be renewed to satisfy an order that runs longer, and the parties or their attorneys should confirm that the structure meets the order’s requirements.
Understanding PIU’s Medical Exclusions
The flexibility of Failure to Survive underwriting comes with an important trade-off that every applicant with a heart condition needs to understand. Rather than declining applicants with cardiac, weight, or diabetes histories, PIU’s approach can apply medical exclusions. An exclusion means the policy will not pay if death results from the excluded condition, even though it will pay for other causes of death.
For someone with a defibrillator, a cardiac exclusion would remove coverage for the very risk the device is there to address. Whether an exclusion applies, and how it is worded, depends on the individual application, so the offer should be reviewed carefully before it is accepted. For a lender or court that simply requires coverage to be in place, a policy with an exclusion may still satisfy the requirement, but the parties should understand exactly what is and is not covered.
PIU’s plans also carry standard exclusions that apply to every insured. They include suicide or intentional self-injury, emotional or psychiatric conditions, illegal drug use and alcohol misuse, HIV and sexually transmitted diseases, active participation in war or terrorism, exposure to nuclear, biological, or chemical agents through terrorism or war, death while committing a felony, and infectious disease during a declared public health emergency. Jason reviews the specific offer with you, including any medical exclusion, so you know precisely what the coverage will do before you rely on it.
Need coverage for a business loan, partnership, or court order?
Request a PIU Review
Lloyd’s of London and the Surplus Lines Market
PIU operates as a coverholder for Lloyd’s of London, which means it is authorized to issue coverage on behalf of underwriting syndicates in the Lloyd’s market. That market specializes in risks that standard insurers will not take, which is why it can consider applicants with defibrillators and other conditions that traditional carriers decline.
Coverage placed through Lloyd’s in the United States is typically written on a non-admitted, or surplus lines, basis. That has two practical consequences. First, policy forms and rates are not filed with each state the way they are for admitted carriers, which allows the flexibility that makes this coverage possible. Second, surplus lines policies generally are not protected by state guaranty associations; Lloyd’s has its own financial structure, including a central fund, that stands behind its policies instead.
For most applicants with a defibrillator, those differences matter less than the fact that coverage is available at all. Still, lenders and courts sometimes have specific requirements about the type of insurer, so it is worth confirming that a Lloyd’s policy will satisfy the party requiring coverage before the application is submitted. Our office checks that point at the outset.
Other Paths Worth Checking
Beyond the two main options, a few other sources of coverage are worth reviewing. Life insurance offered through an employer often includes a guaranteed amount for actively working employees without health questions, particularly during initial enrollment. If your employer offers group life coverage, the guaranteed amount may be available to you regardless of your heart history, and it can sit alongside the 20-hour program.
For applicants over 50 who are focused on funeral and final expenses, guaranteed issue final expense coverage is another option. These policies usually provide smaller amounts and often include a waiting period during which natural-cause deaths pay back premiums rather than the full benefit, so they work best as a supplement rather than as primary protection.
Accidental death coverage is available without health questions as well, but it pays only for deaths caused by accidents, not by heart disease or other illnesses. For someone with an ICD, it can add protection for a specific risk, but it should never be mistaken for life insurance that covers death from the underlying condition. Each of these options has a place, and the right combination depends on your age, your work, and what you need the coverage to accomplish.
What Each Option Costs and Why
Price comparisons look different when fully underwritten coverage is off the table. Guaranteed issue coverage generally costs more per thousand dollars of coverage than fully underwritten term life for a healthy applicant, because the carrier accepts every eligible applicant without considering health. For someone with a defibrillator, though, that comparison is not meaningful, since the fully underwritten option does not exist. The real question is how the available options compare with one another and with the cost of leaving a need uncovered.
For the 20-hour program, the total monthly cost is the life insurance premium plus the Live Well USA membership fee. Premiums depend on age, coverage amount, and whether you choose term or whole life, and a 20-year term costs more than a 10-year term for the same amount. For PIU coverage, the premium reflects the amount of the obligation, the length of the term, and the underwriter’s view of the risk, and it is quoted case by case rather than from a published rate table.
Final expense and accidental death policies usually carry lower premiums because they offer smaller amounts or narrower protection, which is exactly why they should be treated as supplements. A policy that costs less but does not cover death from heart disease, or that pays only premiums back during a waiting period, may not meet the need you are trying to protect.
Our office prices each available option for your age and situation and shows the full cost, including membership fees, so you can compare the protection each one actually delivers rather than the premium alone.
Keeping Coverage in Force Over Time
Coverage that is hard to obtain is worth protecting carefully once it is in place. For the 20-hour guaranteed issue program, that means keeping both the premium and the Live Well USA membership current, ideally through automatic payments from the same account. It also means keeping your beneficiary designations up to date as family circumstances change, since a policy that pays the wrong person does not do its job.
For PIU coverage, the key date is the end of each term. Failure to Survive coverage is generally written for up to five years, and renewal is considered if the need continues, which requires a new review at that time. A loan that runs longer than the coverage term, a buy-sell agreement that remains in effect, or a court order that extends for many years can all outlast a single policy period, so renewal should be planned well before the expiration date rather than at the last minute.
Circumstances also change. A new employer may offer group life coverage with a guaranteed amount, a loan may be paid off, or a court order may end. Each of those events is a reason to review what you have and whether it still fits. Jason tracks renewal dates for the PIU coverage our office places and reviews the full picture with you when your situation changes, so protection stays aligned with the obligations it was bought to cover.
Living With an ICD: What Families Should Plan Around
An ICD is a long-term commitment, and the practical realities of living with one affect planning as well as health. The NHLBI’s guidance on living with a defibrillator notes that people with these devices see their doctor at least every six months and that ICD batteries generally last between five and seven years, with replacement done through a minor procedure. Low-energy pacing is usually not felt, while high-energy shocks last less than a second but can be strong or painful.
The NHLBI also notes that many states require people who receive an ICD or wearable defibrillator after a cardiac arrest or dangerous arrhythmia to wait six months before driving. For a working adult, that can affect commuting and income during the first months after implantation, which is one more reason to put whatever coverage is available in place as soon as you are back at work and eligible.
Most people with ICDs return to full lives, including work, travel, and exercise. The NHLBI notes that most can take part in sports and exercise, though full-contact sports may need to be avoided. From an insurance planning standpoint, the goal is to make sure the family is protected while life goes on normally, using the coverage that remains available rather than waiting for an option that fully underwritten carriers will not offer.
Disclosing Your Device Accurately
Some applicants are tempted to leave a defibrillator off an application in the hope of qualifying for fully underwritten coverage. That approach almost always fails and can cause serious harm. Carriers review prescription histories, medical records, and industry databases, and a defibrillator appears clearly in all of them. An application that omits the device is likely to be declined anyway, and a policy issued on incomplete information can be rescinded if the omission is discovered during the contestable period, which generally runs two years after issue.
A rescinded policy is worse than no policy, because the family may believe they are protected when they are not. Honest disclosure also protects you with the options that do work. PIU’s applications ask health questions, and accurate answers ensure the coverage issued, including any exclusion, reflects the real situation and holds up when a claim is made.
The guaranteed issue program removes the temptation entirely, since health does not affect approval. For business, loan, and court-ordered needs, Failure to Survive coverage is built for applicants that traditional carriers decline. Both paths reward complete and accurate information, and our office helps you prepare it.
Choosing Between the Two Options
The two paths are not competitors. They serve different needs, and many applicants with defibrillators can use both. The 20-hour guaranteed issue program protects your family. Failure to Survive coverage protects a business, a lender, or a former spouse who has a financial interest in your survival. A business owner with a family might enroll in the guaranteed issue program for personal protection and use PIU coverage to satisfy a loan or buy-sell agreement.
If your need is personal and you are working at least 20 hours a week, the guaranteed issue program is the place to start, and applying sooner may lock in a higher age-based maximum. If you are not working, other guaranteed issue options, such as final expense coverage, may be the main alternative. If your need comes from a business arrangement, a loan, or a court order, Failure to Survive coverage is designed for it, provided you can document the obligation and you understand any medical exclusion in the offer.
In every case, the starting point is the same: identify each obligation you want to cover, then match it to the product built for it. That approach avoids paying for coverage that does not fit and avoids the setback of applying for coverage that cannot be approved.
Sequencing matters as well. For a working applicant, enrolling in the 20-hour program first secures family protection while eligibility is clear, since a change in work status or health could close that door later. Business, loan, and court-ordered coverage can then be arranged through PIU on the timeline each obligation requires, with any lender or court consulted before the application is submitted. Supplemental coverage, such as an employer’s guaranteed amount or a final expense policy, can be layered on afterward to fill any remaining gap. Handling the pieces in that order puts the most important protection in place first and keeps each application focused on the need it is meant to serve.
How Our Office Helps
Jason and our office start by understanding your situation: what device you have and why, whether you are working, who depends on you, and whether a business, lender, or court requires coverage. From there, we can tell you which options are realistic and which are not, so you do not spend time on applications that are certain to be declined.
For the 20-hour program, we confirm eligibility, explain the Live Well USA membership and its monthly fee, compare term lengths and amounts at your age, and help you set up payments so coverage stays in force. For Failure to Survive coverage, we gather the financial justification PIU requires, confirm the lender or court will accept the coverage, review any medical exclusion with you, and track renewal dates so coverage does not lapse while an obligation remains.
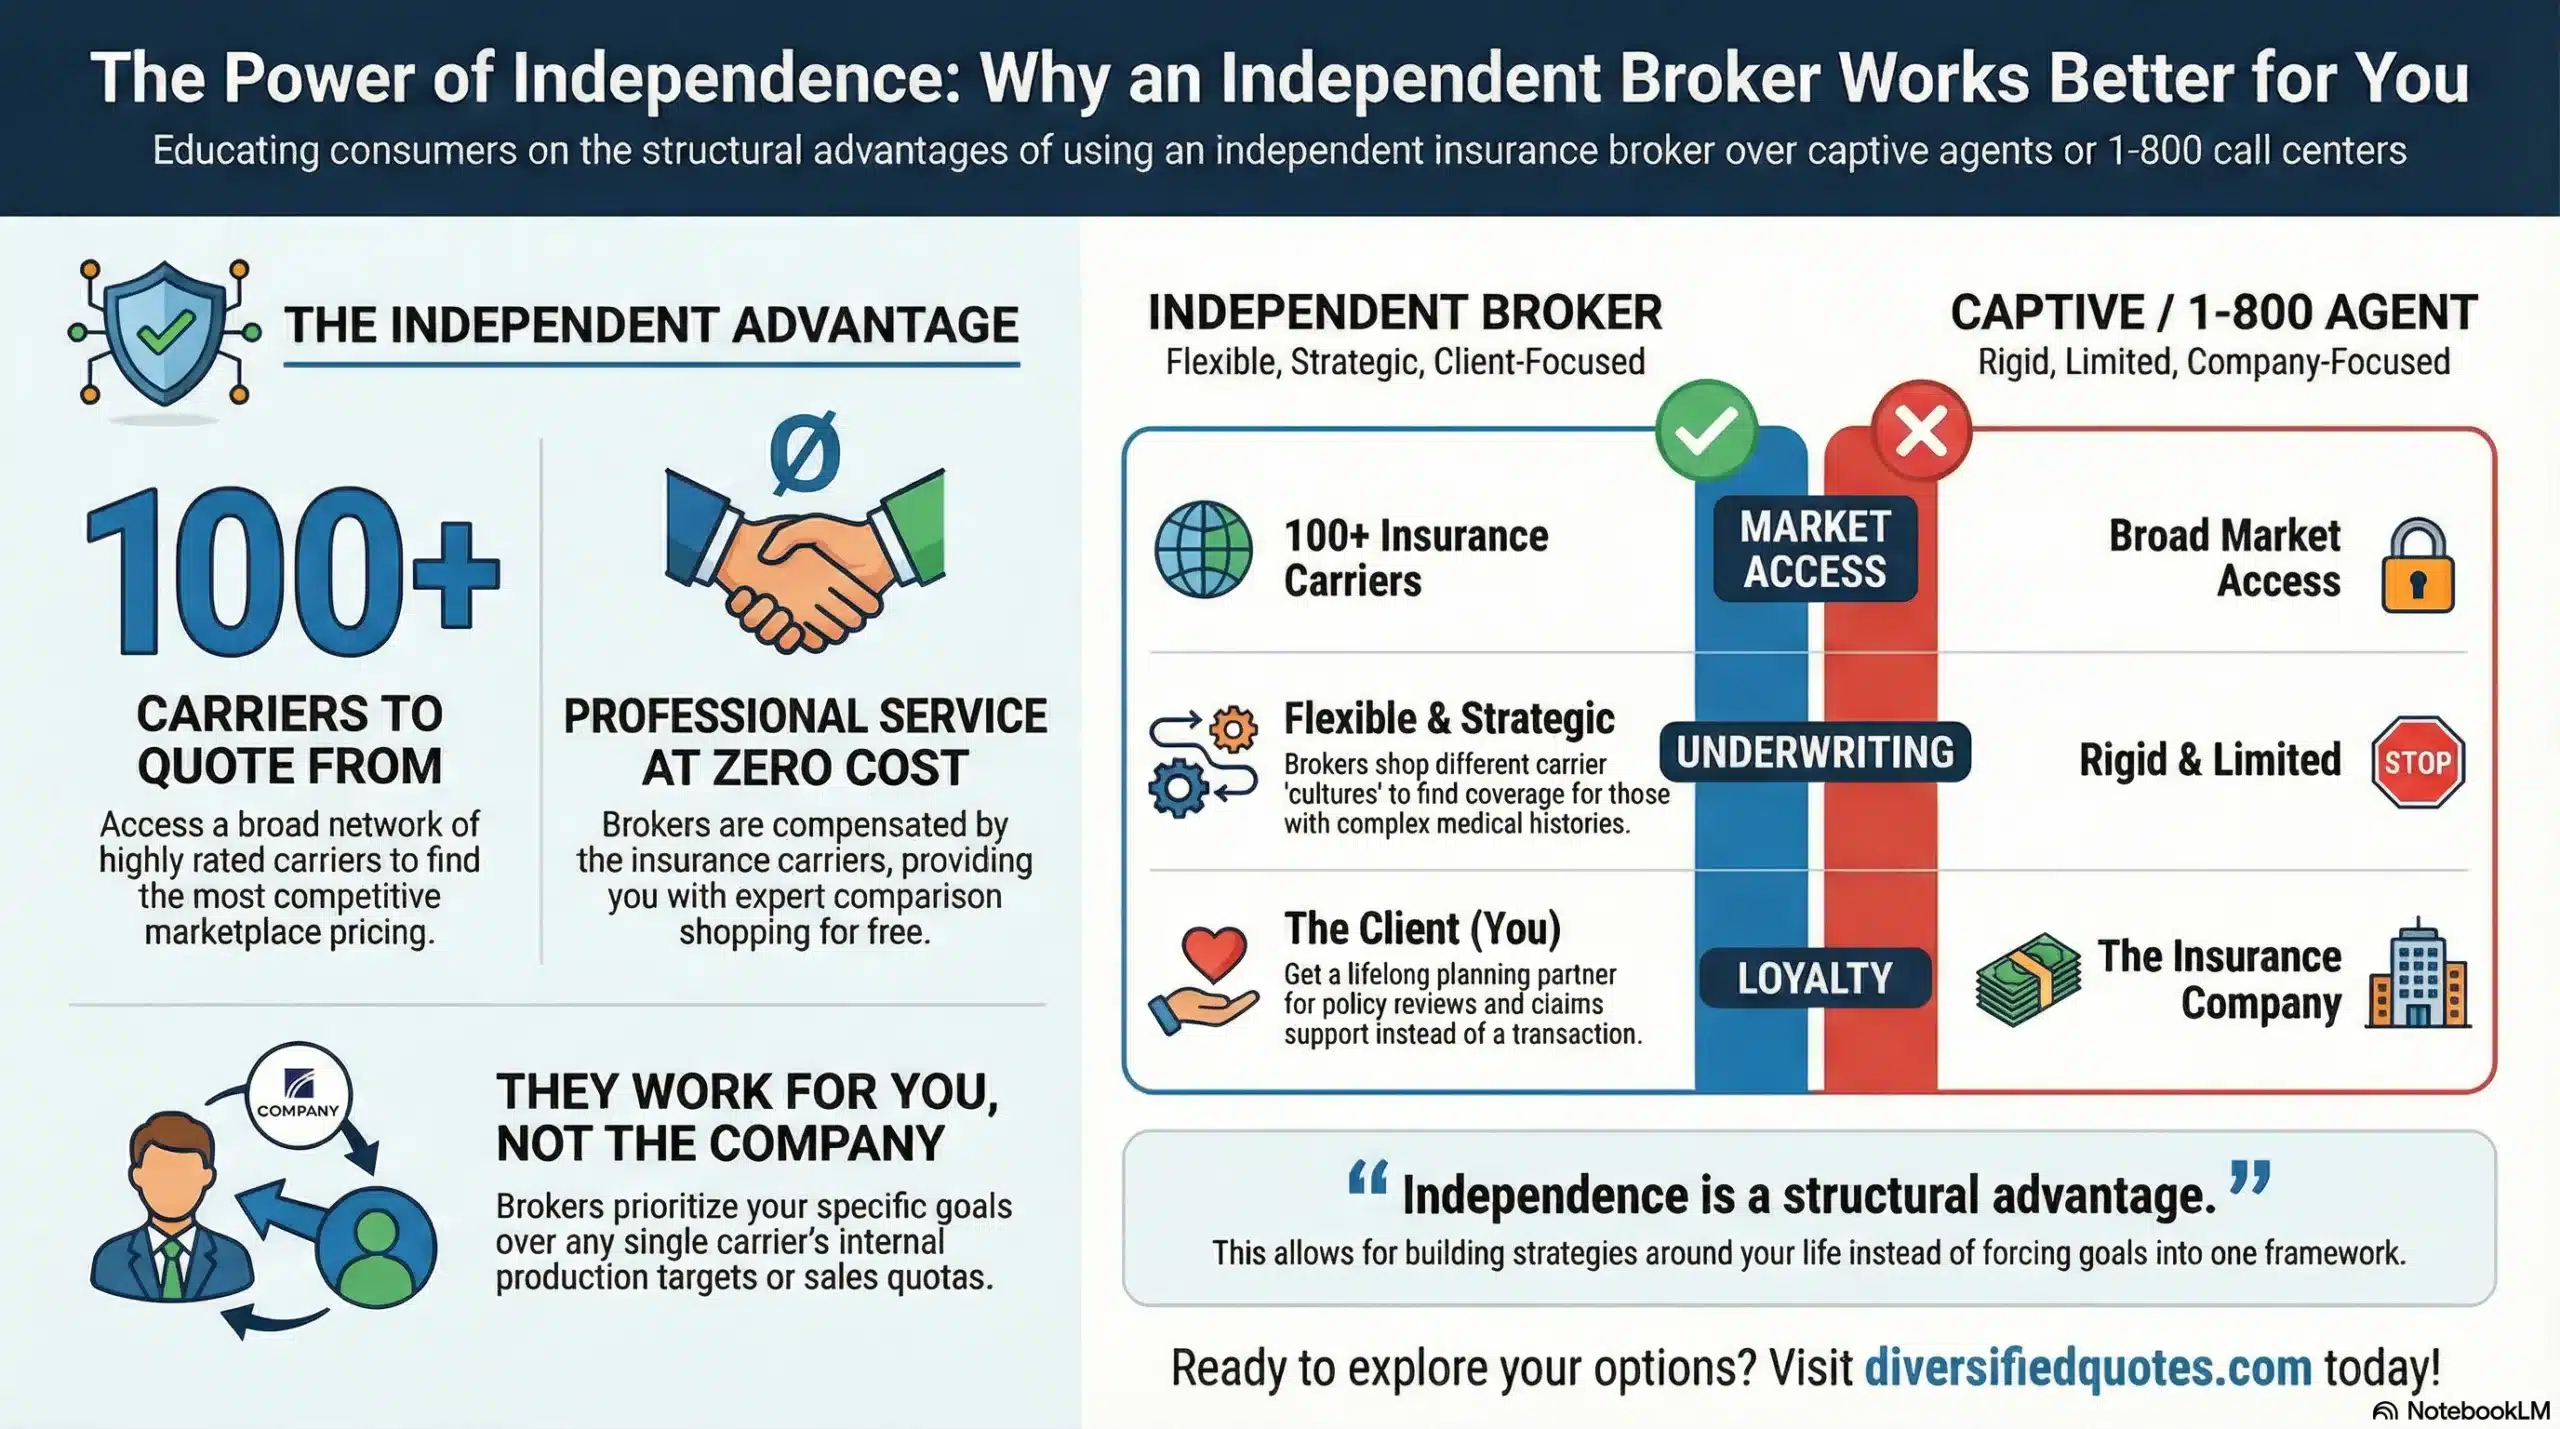
Because we are independent, we are not limited to one carrier or one approach. If another option becomes available, such as group coverage through a new employer, we will help you evaluate it alongside what you already have.
Ready to protect your family or your business despite a defibrillator?
Talk to Our Office
Financial Protection Essentials
More ways to protect your family and business when standard coverage is out of reach.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Can I get traditional life insurance if I have an ICD?
No. Fully underwritten carriers decline applicants with an implanted defibrillator, regardless of how stable the heart is or how long the device has been in place. The realistic options are guaranteed issue coverage, which does not consider health, and specialty coverage such as Failure to Survive policies for business, loan, and court-ordered needs. Our guide to getting life insurance with health issues explains how these paths compare.
Does having a pacemaker count the same as a defibrillator?
No. A pacemaker treats slow heart rhythms, while a defibrillator treats dangerous fast rhythms and signals a higher risk of sudden cardiac arrest. Applicants with a pacemaker alone may still qualify for fully underwritten coverage depending on the underlying condition. If your device both paces and defibrillates, it is treated as a defibrillator. Our page on life insurance with pre-existing conditions covers how other heart conditions are evaluated.
What if I am not working 20 hours a week?
The 20-hour guaranteed issue program requires active work at the time of application, so it is not available if you are retired or not working. Guaranteed issue final expense coverage is often the main alternative for applicants over 50. These policies usually provide smaller amounts and commonly include a waiting period for natural-cause deaths. Our overview of guaranteed issue burial insurance explains how they work.
Can I buy final expense coverage with a defibrillator?
Yes, through guaranteed issue final expense policies that do not ask health questions. Simplified issue final expense policies that do ask health questions may decline or limit coverage for a defibrillator, so the guaranteed issue versions are generally the reliable choice. Expect a smaller benefit and a waiting period before the full benefit applies for natural causes. Our guide to burial insurance for heart conditions covers the options.
My divorce decree requires life insurance. Can I meet it with an ICD?
Often, yes. PIU’s Confidential Failure to Survive plan can cover an ex-spouse to protect alimony or child support, with the written agreement or court order serving as the core of underwriting and no medical exam required. Coverage terms run up to five years and may need renewal for longer orders, and any medical exclusion should be reviewed. Our page on life insurance for divorcees covers related planning.
My lender requires life insurance on my business loan. What can I use?
PIU’s loan indemnification coverage is designed for this. The benefit is limited to the loan balance, the lender is the assignee and owner, and the application requires a short form and a copy of the loan agreement, with no medical exam. Confirm early that your lender will accept the coverage. Our guide on how to collaterally assign a policy to a loan explains how lenders are protected.
Can I get life insurance through my employer with a defibrillator?
Possibly. Many employer group life plans offer a guaranteed amount to actively working employees without health questions, especially during initial enrollment. Amounts above the guaranteed level usually require health questions and may not be available with a defibrillator. Employer coverage can be combined with the 20-hour guaranteed issue program. Our overview of how group life insurance works explains the details.
I was already declined. Can your office still help?
Yes. A decline from a fully underwritten carrier does not affect eligibility for the 20-hour guaranteed issue program, and PIU evaluates business, loan, and court-ordered cases on their own terms. Our office can review what you applied for, why it was declined, and which remaining options fit your needs. You can request a second opinion on your life insurance to get started.
Will a PIU policy pay if I die from my heart condition?
It depends on the offer. For applicants with cardiac histories, PIU may apply a medical exclusion instead of declining, and an exclusion means the policy will not pay if death results from the excluded condition. Whether an exclusion applies, and how it is worded, depends on the individual application, so every offer should be reviewed carefully before it is accepted and relied on.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Life Insurance Options: Browse our complete guide to Life Insurance for Cardiovascular & Respiratory Conditions — covering heart attack, heart disease, stroke, blood clots, COPD, and sleep apnea from 100+ carriers.
Last Reviewed: October 4, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
