Is Malibu Life a Good Insurance Company?
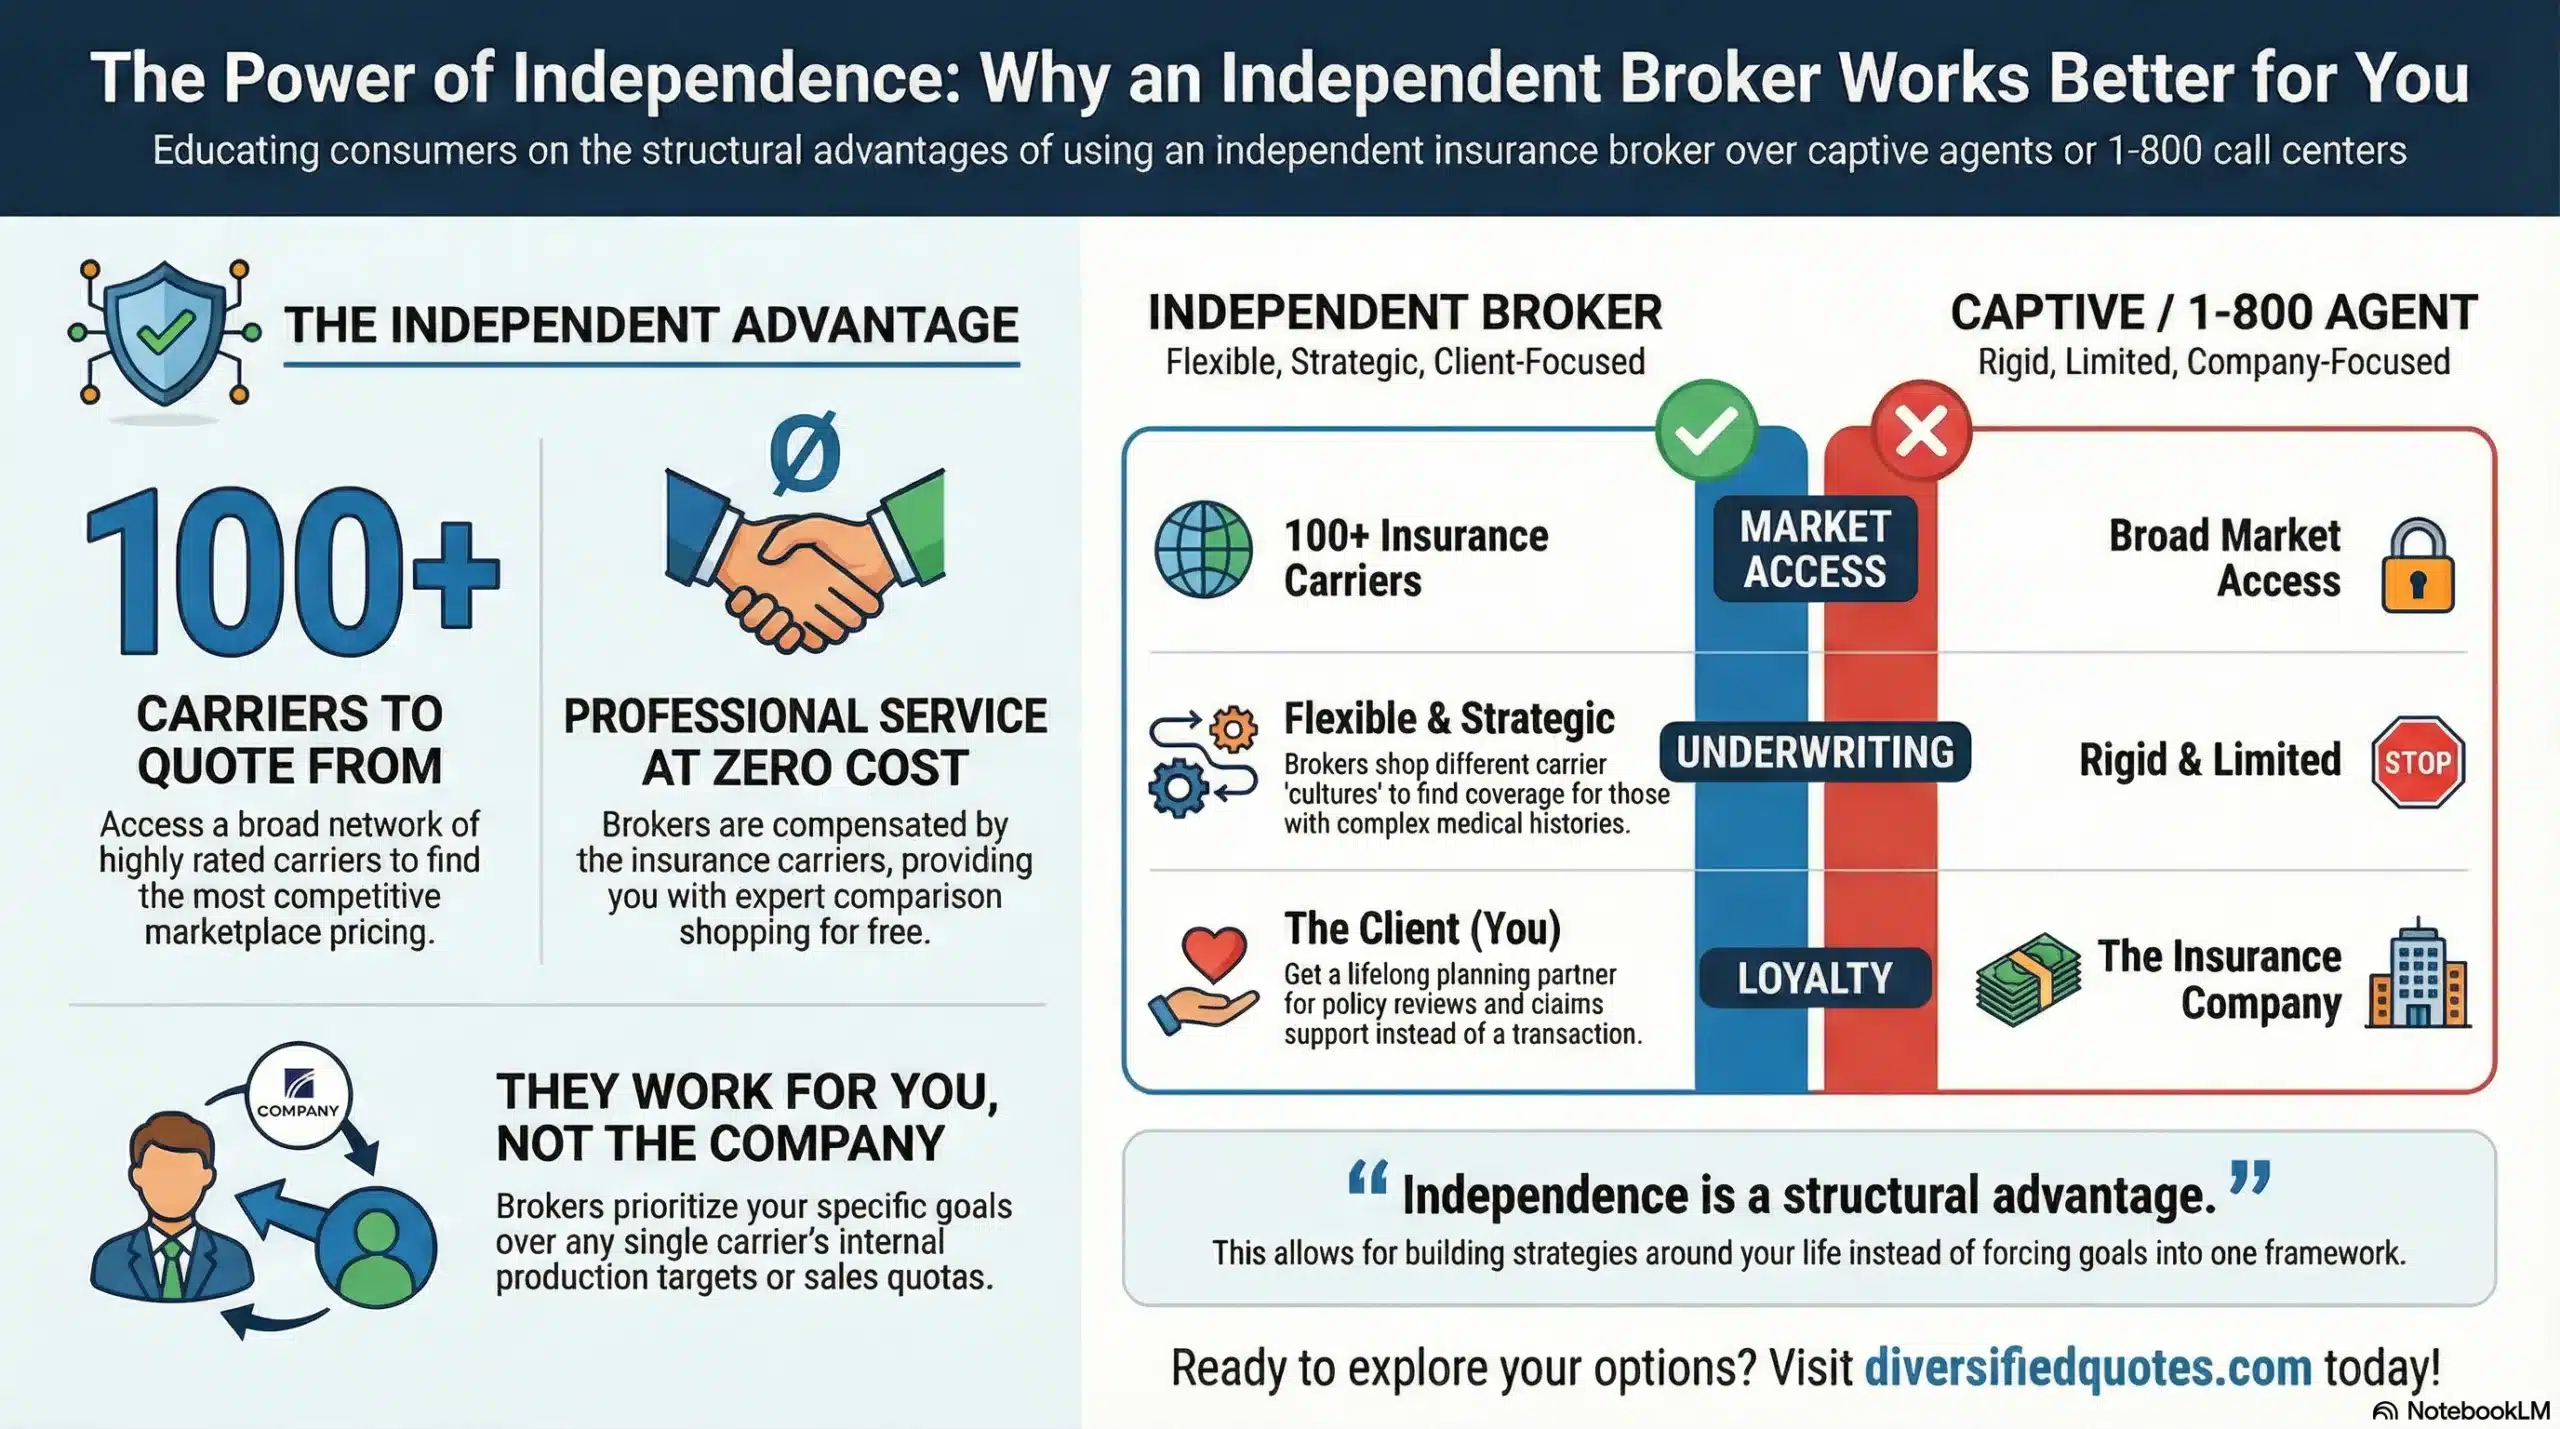
View the table near the end of the page to see why working with an independent insurance broker provides you the best possible rates.
Is Malibu Life a Good Insurance Company?
Jason Stolz CLTC, CRPC, DIA, CAA
AM Best Rating Disclosure
Malibu Life USA annuities are issued by TruSpire Retirement Insurance Company, which holds a B++ (Good) financial strength rating and a bbb+ (Good) issuer credit rating from AM Best, each with a stable outlook in the most recent action we reviewed. On AM Best’s thirteen-level scale B++ ranks fifth, one step below the A- grade that many cautious annuity buyers use as a minimum. Ratings change, so confirm TruSpire’s current rating before you place money with this insurer.
Malibu Life is a new name sitting on an old charter. The annuities sold under the Malibu Life USA brand are issued by TruSpire Retirement Insurance Company, a Texas insurer whose roots go back more than half a century, and TruSpire is now owned by Malibu Life Holdings, a London-listed insurance holding company closely tied to the investment firm Third Point. Rating agencies describe a very strong capital position relative to its small legacy block, an AM Best grade of B++, and a KBRA grade of A-, but its new annuity business has almost no track record yet. For some buyers that adds up to a reasonable home for part of their savings, provided they understand the trade-offs of a young operation. Everything else on this page sits on top of that.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this review reflects how our office weighs a newly launched annuity carrier against more established insurers. Working as an independent annuity broker, we look at who stands behind a contract, how it is capitalized, and what its products promise, then measure those answers against competing contracts so you can see where your money is best placed.
Considering a Malibu Life annuity?
Compare Malibu Life Options
Malibu Life at a Glance
| Item | Details |
|---|---|
| Issuing Insurer | TruSpire Retirement Insurance Company, a Texas-domiciled life and annuity insurer headquartered in Irving, Texas |
| Brand Name | Malibu Life USA, the marketing name for the U.S. retail annuity business of Malibu Life Holdings Limited |
| Parent Company | Malibu Life Holdings Limited, a Cayman Islands holding company listed on the London Stock Exchange |
| AM Best Rating | B++ (Good) financial strength and bbb+ issuer credit, stable outlook |
| KBRA Rating | A- (Strong) insurance financial strength, stable outlook |
| Licensed In | 43 states plus the District of Columbia; excluded states include New York, New Jersey, California, Michigan, Rhode Island, South Carolina, and Wisconsin |
| Products | Fixed indexed annuities with built-in income riders, built around guaranteed lifetime withdrawal benefits |
| Investment Partner | Third Point LLC provides institutional investment expertise to the Malibu Life platform |
| Backstop if the Insurer Fails | Coverage limits set by each state life and health guaranty association |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Malibu Life Is
The name on the brochure and the name on the contract are not the same, and that distinction matters. Malibu Life USA is a marketing name, used for the U.S. retail insurance business of Malibu Life Holdings Limited. The holding company itself does not sell products in the United States. Every annuity marketed under the Malibu Life USA name is issued by TruSpire Retirement Insurance Company, and TruSpire alone carries the financial responsibility for paying what those contracts promise.
When you evaluate Malibu Life, then, you are really evaluating TruSpire. Its ratings, its capital, its investment portfolio, and its claims-paying ability are what stand behind your account value, your income rider, and your death benefit. The parent matters too, because it supplies capital and strategy, but the contractual obligation sits with the Texas insurer.
According to Malibu Life USA’s company information, TruSpire is headquartered in Irving, Texas, and is licensed in 43 states and the District of Columbia. AM Best also notes administrative offices in Stamford, Connecticut. The company describes its goal as creating long-term value for policyholders and distribution partners, and it distributes its annuities through independent agents. For a buyer, that means you will meet Malibu Life through an advisor or broker, and the quality of that advisor’s comparison work becomes part of the decision.
A Decades-Old Texas Charter With a New Purpose
TruSpire did not start life as TruSpire. The company began more than half a century ago as Landmark Life Insurance Company, a Texas life and annuity insurer based in Brownwood, Texas. Before it was sold, Landmark Life was owned by a family partnership and sold life insurance and annuities through independent agents across dozens of states.
Mutual of America, a long-established retirement services company, bought Landmark Life and renamed it TruSpire Retirement Insurance Company. The plan at that time was to use the Texas company to write new individual annuities and pension risk transfer business, and to launch a suite of fixed indexed annuities. AM Best assigned TruSpire an A- rating after that purchase, with the rating supported by explicit capital backing from its parent.
That plan did not unfold as presented. AM Best later reported that TruSpire’s strategic objectives had shifted from the original business plan, and it described the company as largely dormant, managing a run-off block of older life and annuity policies rather than writing significant new business. In practical terms, TruSpire became a licensed, well-capitalized insurer with an approved fixed indexed annuity product and few active sales. That combination is exactly what made it attractive to a buyer looking for a ready-made platform. A dormant insurer with broad licenses can save a new owner years of regulatory work, and that is the role TruSpire now plays for Malibu Life.
The Malibu Life Holdings and Third Point Connection
Malibu Life Holdings is closely tied to Third Point, the investment firm led by Daniel Loeb, who is described in coverage of the TruSpire deal as the founder of Malibu Life and chief executive of Third Point LLC. The listed holding company traces back to Third Point Investors Limited, a London-listed investment company that completed a reverse takeover of Malibu Life Reinsurance SPC and turned itself into an insurance holding company. It now trades on the London Stock Exchange as Malibu Life Holdings.
Before acquiring TruSpire, Malibu Life operated as a Cayman Islands-based reinsurer of annuity business. Reinsurers take on blocks of risk from other insurers but do not sell policies to consumers. Buying TruSpire gave the group its own U.S. retail insurer, so it can originate annuities directly rather than relying only on other companies’ production. The deal also included a Bermuda-regulated reinsurer that Malibu Life said it planned to keep.
The Third Point relationship is central to the strategy. Malibu Life has described its model as combining annuity origination, capital management, and institutional asset management, with Third Point’s credit investment platform as a key partner. This structure, in which an asset manager owns or sponsors an annuity writer, has become common across the industry. It can support competitive crediting rates, but it also places more weight on how carefully the assets backing your annuity are chosen and monitored over time.
How the Acquisition Came Together
Malibu Life announced a definitive agreement to buy TruSpire from its prior owner with a base purchase price of $45 million, a modest figure that is consistent with a small legacy block rather than a large book of business. The transaction required regulatory approval, and while it was pending, AM Best placed TruSpire’s ratings under review with developing implications, meaning the outcome could have moved the ratings in either direction.
Once the deal closed, TruSpire became an indirect subsidiary of Malibu Life Holdings and began operating under the Malibu Life USA brand. Leadership changed at the same time. Todd Shriber succeeded the founding chief executive as CEO of Malibu Life Holdings, and the published Malibu Life USA leadership also includes a chief financial officer, a chief actuary and risk officer, a chief operations officer, a chief product officer, and a general counsel. Two of the directors listed on Malibu Life USA’s site are senior Third Point executives.
The first products followed shortly after closing: two fixed indexed annuities with income riders, designed and marketed by an independent marketing organization and sold through independent agents. Company leadership has also pointed to TruSpire’s membership in the Federal Home Loan Bank system as a source of capital flexibility. Malibu Life has said it intends to add other fixed annuity products, including multi-year guaranteed annuities, over time. For now, the product line is narrow, and the company’s track record with policyholders is still being written.
AM Best Rating: What B++ Means
AM Best is the rating agency most annuity buyers check first, and its view of TruSpire has moved with the company’s ownership. The insurer earned an A- when Mutual of America’s support stood behind it. AM Best later downgraded TruSpire to B++ because it removed the rating lift the parent had provided after the parent’s own ratings were cut, and because TruSpire’s strategy had shifted from the original plan. After the Malibu Life purchase closed, AM Best removed the ratings from review and affirmed the B++ financial strength rating and bbb+ issuer credit rating with stable outlooks.
AM Best breaks its assessment into building blocks. For TruSpire it rates the balance sheet as very strong, operating performance as adequate, business profile as limited, and enterprise risk management as appropriate. The very strong balance sheet reflects capitalization at the strongest level of AM Best’s capital adequacy measure. The limited business profile likely reflects a company with little new business and a narrow product line.
Our page on what an AM Best rating means explains the full scale. B++ is considered a good rating, not a weak one, but it sits below the excellent range. AM Best says it will continue to monitor the company’s results and the execution of its business plan. KBRA is more specific about what could move its own rating: successful execution of the annuity strategy, capital well above target, and broader distribution could support an upgrade, while weaker capital, reduced parent support, or underperformance could lead to a downgrade.
KBRA’s A- Rating and What It Weighs
TruSpire also holds an A- (Strong) insurance financial strength rating from KBRA, with a stable outlook. KBRA’s scale has more steps than AM Best’s, and the company reports A- as the seventh highest of KBRA’s twenty-two levels. Having a second rating from a recognized agency gives buyers another independent view, and in this case the two agencies land in broadly similar territory: solid, but not top tier.
KBRA’s published reasoning is useful because it lists strengths and challenges side by side. On the strength side, KBRA pointed to strong capitalization relative to the legacy run-off block, an unlevered statutory capital base, a conservative and liquid investment portfolio, sound asset adequacy results on the legacy business, defined frameworks for capital, liquidity, and risk governance, and capital support from the parent. It also credited the experienced annuity management team and access to resources through Malibu Life Holdings and Third Point.
On the challenge side, KBRA cited execution risk in building a new U.S. individual annuity business, an unseasoned earnings profile with limited diversification, and initial reliance on a single distribution partner for access to independent marketing organizations and agents. It also described the company’s risk management, hedging, outsourcing, and distribution controls as credible but still developing, and not yet tested through sustained sales or a market shock. Those are fair cautions for any newly launched annuity writer, and they are worth keeping in mind when deciding how much money to place with one carrier.
Capital Strength and the Parent Support Agreement
Capital is the cushion an insurer holds above what it owes policyholders, and it is where TruSpire looks strongest on paper. AM Best places TruSpire’s risk-adjusted capitalization at the strongest level of its capital adequacy measure, and KBRA describes the capital base as strong and unlevered. Those readings are easy to achieve when the business on the books is a small, aging block of older policies, because there is very little risk for the capital to support.
The real test comes as new annuity sales grow. Every dollar of new premium adds obligations, and the capital ratio naturally falls as the business scales. KBRA reports that the company targets a company action level risk-based capital ratio of at least 400 percent as the annuity book grows. A capital support agreement requires Malibu Life Holdings to restore the ratio to at least that level if it falls below it at the end of any quarter, through capital contributions or other capital approved by regulators, subject to the agreement’s terms.
That agreement is a meaningful commitment, but it is only as strong as the parent’s ability and willingness to honor it. Malibu Life Holdings is itself a young operating company, funded in part by its holdings in Third Point’s investment strategies. AM Best has said it expects the parent to contribute the capital needed for growth and liquidity. Buyers should watch how the capital ratio, ratings, and parent support evolve as sales build, because those factors will tell you whether the strong starting position is being maintained.
Where the Money Is Invested
An annuity’s guarantees are only as good as the assets behind them, so the investment portfolio deserves attention. KBRA describes TruSpire’s current portfolio as conservative and liquid, made up primarily of bonds and cash, with limited exposure to complex investments or derivatives. That profile fits a company that has been managing a run-off block rather than chasing yield.
The investment policy allows that mix to change as the new annuity business grows. KBRA reports that the policy permits structured securities, mortgage loans, private assets, alternatives, and other less liquid investments, within defined limits on credit quality, issuer concentration, sector, liquidity, and duration. With Third Point’s credit platform as a key partner, it is reasonable to expect more private and structured credit over time. Many annuity writers backed by asset managers follow a similar path, because those assets can support higher crediting rates.
Private credit is not automatically risky, but it is harder for outsiders to evaluate than publicly traded bonds, and it can be less liquid in a stressed market. The practical takeaway for a buyer is to keep an eye on the rating agencies’ commentary over the life of the contract, and to keep any single insurer’s share of your savings at a level you would be comfortable with if conditions changed. A strong rating agency view of asset quality today is helpful, but it is a snapshot rather than a promise about the future portfolio.
Licensing and Where Malibu Life Sells
TruSpire is licensed in 43 states and the District of Columbia. According to the company, it does not do business in New York, New Jersey, California, Michigan, Rhode Island, South Carolina, or Wisconsin. If you live in one of those states, Malibu Life USA annuities are not available to you, and you will need to look at other carriers for comparable features.
Even within licensed states, product availability is not uniform. The product materials we reviewed list the states where each annuity is approved and note that features, riders, and availability can vary by state. In several states, for example, the enhanced death benefit is calculated differently, and the rider contract governs the details. A product approved in your state may also carry state-specific versions of surrender charges, free withdrawal provisions, or care-related benefits.
Where you live also decides which guaranty association would stand behind your contract if the insurer ever failed, and the protection limits differ from state to state. Before you buy, confirm three things: that the specific product is approved in your state, which state-specific provisions apply to your contract, and what your state’s guaranty association covers for annuities. An advisor should be able to show you the state approval list and the state-specific contract forms rather than relying on a general brochure.
The Product Lineup
Malibu Life USA launched with two fixed indexed annuities, both issued by TruSpire on a ten-year modified single premium deferred annuity chassis and both paired with a guaranteed lifetime withdrawal benefit rider. They share the same issue ages, the same crediting strategies, the same surrender schedule, and the same care-related and death benefit features. The main difference lies in the rider and how quickly income can start, although at launch SpireMark’s caps on several strategies were set slightly lower than PillarMark’s, while participation rates matched.
The Malibu Life SpireMark annuity pairs with a rider that carries an annual charge and allows lifetime income to start as early as 30 days after the contract is issued. It is aimed at people who want income soon, or who want the flexibility to turn it on whenever they choose. The Malibu Life PillarMark annuity pairs with a rider that has no added charge, but income cannot start until ten years after issue or age 85, whichever comes first. It suits people who have time to wait and would rather avoid an ongoing fee.
Both products use a fixed account and a menu of index strategies tied to the S&P 500, a volatility-controlled version of the S&P 500, a Nasdaq-100 based index, a multi-asset index built around Nasdaq-100 stocks, Treasuries, and gold, and a bitcoin-linked index. That last option is unusual in fixed indexed annuities and will appeal to some buyers more than others. Our guide to fixed versus fixed indexed annuities explains how this type of contract differs from a traditional fixed annuity.
Want to see how Malibu Life’s income riders compare with other carriers?
Request an Income Comparison
Income Riders With Care and Legacy Features
The riders on both Malibu Life annuities are built around a single benefit base that drives three kinds of benefits: lifetime income, benefits triggered by a need for care, and an enhanced death benefit. The product materials call this a benefit base trifecta. Because one value supports all three, a decision about one benefit can affect the others, which is a point every buyer should understand before signing.
The care-related benefits become available after a two-year waiting period from issue, when the owner is confined or impaired in two of six activities of daily living. Before income starts, an activities of daily living benefit can pay out a value tied to the benefit base in monthly installments over seven years, although electing it ends the contract’s other benefits. After income starts, an enhanced income benefit can raise the withdrawal amount to 225 percent of the normal amount until the account value is depleted. These features can help fund care, and you can compare them with traditional coverage in our look at annuities as a long-term care alternative.
The enhanced death benefit is available to beneficiaries after the contract has been in force for two years, as long as account value remains. It pays a value tied to the benefit base in monthly installments over five years, rather than as a single lump sum. Heirs can still choose the standard death benefit instead, which pays the greater of the account value or the guaranteed minimum value. Each product page explains these features in more detail.
Liquidity, Surrender Charges, and the MVA
Both Malibu Life annuities carry a ten-year surrender charge schedule that starts at 10 percent and declines each year to zero after the tenth contract year. Our guide to how annuity surrender charges work explains why insurers use these schedules. Withdrawals within the free amount avoid the charge: 10 percent of the contract is available in the first year, and starting in year two the free amount can build up to a maximum of 20 percent if no withdrawals were taken the prior year, or the contract’s required minimum distribution if that is higher.
The market value adjustment deserves special attention. A market value adjustment on annuities can raise or lower the amount you receive on an excess withdrawal or surrender depending on how interest rates have moved. On these contracts, the MVA period lasts ten years from the contract date, and a new ten-year MVA period begins on every tenth contract anniversary. The MVA does not apply during the 30-day window before each new period begins. That design means the MVA can apply to large withdrawals even after the surrender schedule has ended, except during that 30-day window, so timing matters.
Waivers of surrender charges are included for nursing home confinement, terminal illness, and home health care, subject to the contract’s terms. The materials we reviewed did not describe an annuity bail-out provision, so do not assume one exists. Ask how the MVA and waivers would apply to your situation before buying.
Distribution Through Independent Agents
Malibu Life USA sells through independent agents, and its first products were designed and are exclusively marketed by an independent marketing organization that recruits and supports agents across the country. That arrangement is common for new carriers, because it gives them immediate access to a national network of producers without building a sales force from scratch.
It also creates a concentration risk that KBRA flagged directly: early sales depend on a single distribution partner. If that relationship changed, new business could slow, which would affect the company’s growth plans and earnings. That does not change the guarantees in a contract you already own, but it does shape how quickly the company can build scale, diversify its earnings, and improve its business profile in the eyes of rating agencies.
For a buyer, the distribution model has a practical side as well. Because the products are sold only through independent agents, you will typically hear about Malibu Life from an advisor who also has access to other carriers. That is useful, but it also means you should ask why this carrier is being recommended over alternatives. A good advisor should be able to show you comparable income riders from more established insurers, explain the trade-offs in rating and track record, and document why the Malibu Life contract fits your goals better. If the only explanation is a headline bonus or roll-up rate, keep asking questions.
Guaranty Association Protection
Annuities are not bank deposits and are not insured by the FDIC. If an insurer fails, the backstop is the life and health insurance guaranty association in the state where you live. Every state has one, and each sets its own limit on how much annuity value it protects for a given person with a given insurer. Those limits vary, and amounts above the limit are not covered by the association.
Guaranty association protection should never be the main reason for buying an annuity, and reputable agents are generally restricted from using it as a sales point. But knowing your state’s limit is a sensible way to size your allocation to any single carrier, especially a newer one with a B++ AM Best rating. Many buyers choose to keep the amount placed with each insurer at or below their state’s limit, and spread larger sums across several carriers.
Insurer failures are rare, and when they happen, regulators typically arrange for another company to take over the contracts or for the guaranty association to step in. The process can still involve delays and changes to contract terms, and in some cases withdrawals may be restricted while the situation is resolved. A strong capital position, conservative investments, and a supportive parent reduce the chance you will ever need the backstop, but understanding it helps you make a calm, informed decision about how much to place with Malibu Life.
Strengths of Malibu Life
Malibu Life has several real strengths. The first is capital. TruSpire starts its new business from a capital position that both AM Best and KBRA describe in strong terms, and a capital support agreement commits the parent to keep the risk-based capital ratio at or above a stated floor. The second is a clean starting balance sheet. A small legacy block of older policies and a portfolio made up mostly of bonds and cash leave little hidden risk from past business.
The third strength is investment depth. Malibu Life has access to Third Point’s institutional credit platform, which can support competitive crediting rates and rider designs. The fourth is a second, independent rating: KBRA’s A- gives buyers another view, and the reasoning behind it is published and detailed.
Product design is the fifth strength. The two launch annuities combine lifetime income, care-related benefits, and an enhanced death benefit around a single benefit base, plus surrender charge waivers for nursing home, terminal illness, and home health care. The menu of crediting strategies is broader than many launch products, with preset allocation blueprints for buyers who prefer not to choose strategies themselves. Finally, the company’s leadership team includes experienced annuity executives, which matters when a carrier is building administration, hedging, and service from a near-standing start.
Concerns to Weigh
The most important concern is the lack of a track record. Malibu Life’s annuity business is new, so there is no history of how it handles service, claims, renewal rates, or rider benefits over a full market cycle. Renewal rates matter a great deal in fixed indexed annuities, because the caps and participation rates you start with can be changed after the first term, within the contract’s minimums.
The second concern is the AM Best rating. B++ is a good rating, but it is below the A- threshold that many buyers and some advisors use as a minimum. The rating agencies have tied future movement to execution, which means the rating could improve or weaken depending on how the business develops. Third, KBRA has flagged reliance on a single distribution partner and risk controls that have not yet been tested through sustained sales or a market shock.
Fourth, the investment approach will likely shift toward more private and structured credit as the business grows, which is common among asset-manager-backed insurers but is harder for outsiders to evaluate. Fifth, the contracts themselves are complex. They combine a ten-year surrender schedule, a market value adjustment that renews every ten years, benefit base formulas, and care and death benefits that end other benefits once elected. None of these concerns rules Malibu Life out, but together they argue for careful sizing and a clear understanding of the contract.
Not sure how much to place with a newer carrier?
Ask About Allocation
How Malibu Life Compares With Other Newer Annuity Carriers
Malibu Life is part of a broader wave of annuity companies built on older insurance charters by new owners, often with ties to asset managers. Comparing it with similar companies helps put its strengths and risks in context. Our review of whether Ohio State Life is good covers a carrier that also pairs a long corporate history with a recently reinvented annuity business and a rating below the A range.
Other newer entrants have taken their own paths, with different owners, product lines, and ratings. Our reviews of Axonic as an annuity company and Knighthead Life as an insurer walk through how those companies are structured and rated. Reading several reviews side by side makes it easier to see which features are unique to Malibu Life and which are common to this group of carriers.
A few questions sort these companies out quickly. How long has the carrier been writing new annuity business? What do AM Best and any second rating agency say about its balance sheet and business profile? How concentrated is its distribution? How much of its portfolio sits in private or structured credit? And what does its renewal rate history show, if any exists? Malibu Life scores well on capital and has a second rating, but it has the shortest operating history in its current form, which is the main reason to size an allocation with care.
Who Malibu Life May Fit
Malibu Life’s annuities may fit buyers between 50 and 85 who want guaranteed lifetime income from a fixed indexed annuity and value the care-related and enhanced death benefit features built into its riders. Someone who wants income soon and accepts an annual rider charge may lean toward SpireMark, while someone who can wait at least ten years, or until age 85, and prefers to avoid rider fees may lean toward PillarMark.
The company may also fit buyers who are comfortable with a newer carrier because of its strong starting capital, its parent support agreement, and its A- KBRA rating, and who plan to keep their allocation within their state’s guaranty association limit or spread larger sums across several insurers. Buyers who are interested in a bitcoin-linked index option inside a contract that protects principal from index losses may find the crediting menu appealing, provided they understand that index credits are limited by caps and participation rates.
Finally, Malibu Life may fit people who will hold the contract for the full ten-year surrender period or longer and who do not expect to need large withdrawals beyond the free amount. Patience is a requirement with these products. Buyers who are likely to need significant access to their money, or who may want to move it before the surrender schedule ends, should think carefully before committing.
Who Should Look Elsewhere
Some buyers should look elsewhere. If your rule is to place retirement money only with insurers rated A- or higher by AM Best, Malibu Life does not meet that standard today. Plenty of highly rated insurers sell income-focused indexed annuities, and the difference in guarantees may matter more to you than any difference in features.
Buyers who live in New York, New Jersey, California, Michigan, Rhode Island, South Carolina, or Wisconsin cannot buy these contracts. The launch products are also not yet approved in every state where TruSpire holds a license, so confirm approval where you live. People younger than 50 are outside the issue ages. Anyone who expects to need large withdrawals during the first ten years, or who could need to surrender the contract early, should weigh the surrender charges and the market value adjustment carefully, and may be better served by a shorter contract.
Buyers looking for simple, guaranteed growth with no moving parts may prefer a multi-year guaranteed annuity, which Malibu Life does not yet offer. And anyone uncomfortable placing money with a company that has little operating history in its current form should wait. As the business develops, the rating agencies will publish updated views, renewal rate history will build, and it will become easier to judge how Malibu Life treats its policyholders over time. There is no penalty for waiting to see that record develop.
Moving Money to Malibu Life
Most people fund an annuity like this with savings, an IRA or other qualified money, or an existing annuity. Both launch products accept qualified and nonqualified money, with a minimum initial premium of $25,000, additional premiums of at least $2,000 allowed only during the first contract year, and a maximum of $2 million per owner without home office approval.
If you are moving money from another annuity, a 1035 exchange between annuity contracts can transfer the value without triggering current income tax. Before exchanging, compare what you would give up, including any surrender charges, accumulated rider value, or death benefit on the old contract. IRA money can typically be moved by direct transfer to keep its tax-deferred status.
Age matters for access. Withdrawals from an annuity may be subject to income tax, and a 10 percent federal penalty can apply to taxable withdrawals taken before age 59 and a half. Because these contracts can be issued as young as 50, some buyers will own them during that window. For the details, see how the IRS early withdrawal penalty rules work, including the exceptions that may help.
Questions to Ask Before You Buy
Before buying any Malibu Life annuity, ask for the current AM Best and KBRA ratings for TruSpire and any recent rating actions. Ask which product version your state has approved, and get copies of the contract and rider forms that apply where you live. Ask your advisor to show the same premium in at least two comparable fixed indexed annuities from carriers rated A- or higher, so you can see what you gain and what you give up.
On the contract itself, ask how the rider’s benefit base grows, what payout percentages apply at your age when income starts, and how the benefit base cap affects the care and death benefits. Ask how the market value adjustment works over the full life of the contract, not only during the surrender period, and when the 30-day windows fall. Ask what happens to your other benefits if you or your beneficiaries elect the care benefit or the enhanced death benefit.
Finally, ask about renewals. Fixed indexed annuity caps and participation rates can change after each crediting term, so ask what minimums the contract guarantees and how the company plans to set renewal rates. Our list of questions to ask about annuities covers additional points that apply to any carrier. Clear, written answers to these questions are the best protection against surprises later.
How Our Office Helps
We begin by asking what you need the money to do: lifetime income, growth, a legacy for heirs, funds for possible care, or some mix of all four. We also look at how much you plan to place, where it is coming from, and when you might need access. Those answers tell us whether an indexed annuity built for income belongs in your plan at all, and if it does, which design suits you.
If Malibu Life is a candidate, we lay its contracts next to comparable annuities from other carriers, including higher-rated insurers, so you can see the differences in rider benefits, crediting options, surrender terms, and financial strength side by side. We explain the B++ AM Best rating and the A- KBRA rating in plain language, and we help you decide how much, if any, to place with a newer carrier, and, if you wish, with your state’s guaranty association limit in mind.
When you choose a contract, we handle the paperwork, coordinate transfers or exchanges from existing accounts, and confirm that the state-specific version of the product is the one being issued. After the contract is in force, we can review renewal rates and rider values with you each year and keep watch on rating changes. Independence means the advice tracks your goals and the evidence rather than any one company’s product shelf.
Ready to compare Malibu Life with other annuity carriers?
Start My Comparison
Financial Protection Essentials
Background reading for anyone weighing a newer annuity carrier.
Talk With an Advisor Today
Choose how you’d like to connect—call or message us, then book a time that works for you.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Who owns Malibu Life?
Malibu Life USA is the brand used by Malibu Life Holdings Limited, a Cayman Islands holding company listed on the London Stock Exchange and closely tied to the investment firm Third Point. Its annuities are issued by TruSpire Retirement Insurance Company, a Texas insurer that Malibu Life Holdings acquired. TruSpire carries the financial responsibility for every contract sold under the Malibu Life USA name.
Are Malibu Life annuities FDIC insured?
No. An annuity is an insurance contract rather than a bank deposit, so FDIC coverage does not apply. They are backed by the issuing insurer and, if the insurer fails, by your state’s life and health guaranty association up to its limits. Our page on whether annuities are FDIC insured explains the difference.
Is my money safe in a Malibu Life fixed indexed annuity?
Your account value is protected from index losses, and credited interest is locked in once earned. The guarantees depend on TruSpire’s ability to pay, which AM Best rates B++ and KBRA rates A-. Surrender charges, the market value adjustment, and withdrawals can still reduce what you receive. Our guide asking whether an indexed annuity is safe covers these risks.
Does Malibu Life charge for its income riders?
It depends on the product. The rider on SpireMark carries an annual charge based on the benefit base, while the rider on PillarMark has no added charge but requires a longer wait before income can start. Our article on whether income riders have fees explains how rider charges usually work.
What is a benefit base, and how is it different from my account value?
The benefit base is a calculation value used to determine rider income and certain other benefits. It is not cash you can withdraw or surrender. Your account value is the actual money in the contract. Our explanation of how an income rider works shows how the two values interact.
How much can I withdraw without a surrender charge?
Malibu Life’s launch products allow 10 percent in the first contract year. Starting in year two, the free amount can build to a maximum of 20 percent if no withdrawals were taken the prior year, or the required minimum distribution if higher. For background, read about annuity free withdrawal rules and how they typically work.
How are Malibu Life annuities taxed?
Like other deferred annuities, growth is tax deferred until withdrawn. Withdrawals of earnings are taxed as ordinary income, and a 10 percent federal penalty may apply to taxable withdrawals before age 59 and a half. IRA money follows qualified account rules. Our guide to how annuities are taxed covers the details.
What happens to a Malibu Life annuity when the owner dies?
Beneficiaries can receive the standard death benefit, which is the greater of the account value or the guaranteed minimum value. After two years, if account value remains, they may instead elect the enhanced death benefit, paid monthly over five years. Our page on annuity death benefits for beneficiaries explains the options.
How does Malibu Life compare with other income annuities?
Malibu Life’s riders bundle lifetime income, care benefits, and an enhanced death benefit around a single benefit base. Its ratings are lower than those of many established income annuity carriers, and its track record is short. Our list of the best income rider annuities gives useful points of comparison.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Review More Carrier Reviews: Browse our complete Annuity Company Reviews — covering Allianz, Athene, Jackson National, North American, and more annuity carriers.
Last Reviewed: October 21, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
