Malibu Life PillarMark Fixed Indexed Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Malibu Life PillarMark Fixed Indexed Annuity
PillarMark Fixed Indexed Annuity, issued by Malibu Life Insurance Company, asks for patience instead of a fee. Its MultiRider income benefit carries no added charge, starts the benefit base with a 50 percent bonus, and grows that benefit base at 200 percent of the interest the contract earns. The catch is timing: lifetime income cannot begin until ten contract years have passed or you turn 85, whichever happens first. For someone who already has income covered for the next decade and wants a larger, fee-free income source waiting at the end of it, that trade can be attractive. For someone who may need income sooner, it is the wrong tool.
AM Best Rating Disclosure
PillarMark’s guarantees come from TruSpire Retirement Insurance Company, the Malibu Life USA insurer, whose AM Best financial strength grade is B++ (Good). AM Best uses thirteen financial strength grades, and B++ is the fifth, directly beneath the A- many retirees insist on before committing long-term money. Look up TruSpire’s latest rating before you buy, because rating agencies revise their opinions over time.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this page applies the same standards our office uses for any deferred income annuity. As an independent annuity broker, we test PillarMark’s projected income, its care and legacy features, and the strength of its issuer against deferred income options from other insurers, so the decision rests on numbers rather than on a headline bonus.
Curious what PillarMark would pay you in ten years?
See My PillarMark Projection
PillarMark Key Features
| Provision | PillarMark Terms |
|---|---|
| Insurance Company | TruSpire Retirement Insurance Company, marketed as Malibu Life USA |
| Product Design | Modified single premium deferred fixed indexed annuity with a ten-year term |
| Who Can Buy | Ages 50 to 85, using IRA or other qualified funds as well as nonqualified savings |
| Premium Rules | At least $25,000 to open; first-year additions of $2,000 or more; home office approval above $2 million per owner |
| Income Benefit | MultiRider lifetime withdrawal benefit at no additional cost |
| Bonus on the Benefit Base | 50 percent |
| Growth Before Income | Roll-up of 200 percent, linked to credited interest |
| When Income Can Begin | After ten contract years or at age 85, whichever is reached first |
| Growth After Income | Roll-up of 100 percent, which the materials say continues even once account value is exhausted |
| Surrender Schedule | Ten years, starting at 10 percent; see how annuity surrender charges work |
| Death Benefit | Larger of account value or guaranteed minimum value, plus an optional enhanced benefit; see whether annuities have a death benefit |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
The Insurer Behind PillarMark
PillarMark is a TruSpire Retirement Insurance Company contract. TruSpire is a Texas life and annuity company based in Irving that now does business as Malibu Life USA, the American retail brand of Malibu Life Holdings Limited, whose shares trade in London and which works closely with the investment firm Third Point, but the promises inside a PillarMark contract belong to TruSpire and depend on TruSpire’s finances.
Two rating agencies cover the company. AM Best places TruSpire at B++ (Good) with a stable outlook, and KBRA rates it A- (Strong), also stable. Both point to a strong starting capital position measured against a small block of older policies, and KBRA notes the challenge of building a new annuity business with an unseasoned earnings record, while AM Best says it will monitor execution of the business plan. PillarMark and its sister product were among the first contracts launched under the Malibu Life USA name, which means today’s buyers are early customers of this business.
Because PillarMark’s main payoff, lifetime income, arrives a decade or more after purchase for most buyers, the insurer’s long-term strength matters even more here than in a contract you might cash out after a few years. Our full review of Malibu Life as an insurer covers the ownership history, capital support agreement, and investment approach. The Malibu Life USA home page lists the company’s current ratings and the states where it does not do business.
A Rider With No Added Charge
Most income riders on fixed indexed annuities charge an annual fee, often figured on the benefit base and deducted from the account value. PillarMark’s MultiRider is described in the product materials as a no-cost guaranteed lifetime withdrawal benefit. Nothing is deducted from your account value each year to pay for it, so all of the interest your contract earns stays in the contract.
That matters more than it might first appear. Over ten years, an annual rider fee of around one percent of a growing benefit base can add up to a large share of the original premium. Avoiding that cost leaves more cash value available for withdrawals, for a surrender after the penalty period, and for heirs. It also means a string of flat crediting years does not erode your account, because there is no rider deduction to subtract.
A rider without a separate charge is not free in an economic sense. Insurers price these benefits into the contract through the caps and participation rates they offer, the payout percentages they set, and the restrictions they impose, such as PillarMark’s waiting period before income. Still, for a buyer who fits the waiting period, removing the visible fee is a real advantage. Our guide to lifetime withdrawal benefits explained covers how these riders work in general and what to compare between them.
The Ten-Year or Age-85 Income Clock
PillarMark’s defining rule is when income can begin. According to the product materials, lifetime income under the MultiRider can start once ten contract years have passed, or at age 85 if that comes sooner. Until one of those points arrives, the rider simply builds its benefit base, and you cannot turn on guaranteed lifetime withdrawals.
A few examples show how the clock works. A 55-year-old who buys PillarMark could start income at 65, after the tenth contract year. A 70-year-old buyer would reach the ten-year mark at 80. A buyer who is 80 at purchase would hit age 85 after five years, before the ten-year mark, so income could start sooner. Buyers at the very top of the issue age range should ask exactly how the rule applies to them, because the age-85 trigger arrives almost immediately.
This waiting period is the price of the no-cost rider and the larger bonus. It works well for people who see PillarMark as a future income layer, perhaps to start once a pension bridge ends, once Social Security has been claimed at its highest amount, or once other savings have been drawn down. It does not work for anyone who needs dependable lifetime income from this money soon. Be honest about your timeline before committing, because once the contract is issued the clock cannot be shortened, and surrendering early to find income elsewhere would mean paying surrender charges.
How the 50 Percent Bonus Fits In
When the contract is issued, the MultiRider adds 50 percent to PillarMark’s benefit base. That bonus belongs to the income calculation. It is not credited to your account value, so it does not change the cash you could withdraw, the amount you would receive on surrender, or the standard death benefit.
The bonus pairs naturally with the waiting period. Because income cannot start for up to ten years, the benefit base has a long runway, and starting from a figure 50 percent higher than your premium means every later roll-up builds on a larger number. When income finally begins, the payout percentage is applied to that larger benefit base. PillarMark’s bonus is also slightly larger than the 45 percent bonus on SpireMark, its fee-based sibling.
Even so, a bonus figure alone tells you little about the income you would actually receive. The payout percentage at your age, the way roll-ups accumulate, and the crediting results of the strategies you choose all affect the final number. Our page on a bonus annuity with lifetime income explains how bonuses and income riders interact. The fair way to judge PillarMark is to compare its projected and guaranteed income at your planned start age with the same figures from competing products, using the same premium.
Roll-Ups at 200 Percent of Credited Interest
Before income begins, PillarMark’s benefit base grows through a performance-based roll-up. The roll-up rate is 200 percent, and it is tied to the interest your contract earns. The announcement for the product line says the benefit base can grow as interest is credited, with roll-ups that apply both before and after income is turned on.
Here is a rough illustration. Suppose the contract earns a 5 percent credit in a year. Applying a 200 percent roll-up, the benefit base would climb by about 10 percent. If the contract earns 2 percent, the benefit base would rise about 4 percent. A year with no credit means no roll-up at all. The precise method is spelled out in the rider contract, including whether the 200 percent applies to the credited rate or to the dollars credited, so verify the mechanics on an illustration before relying on any projection.
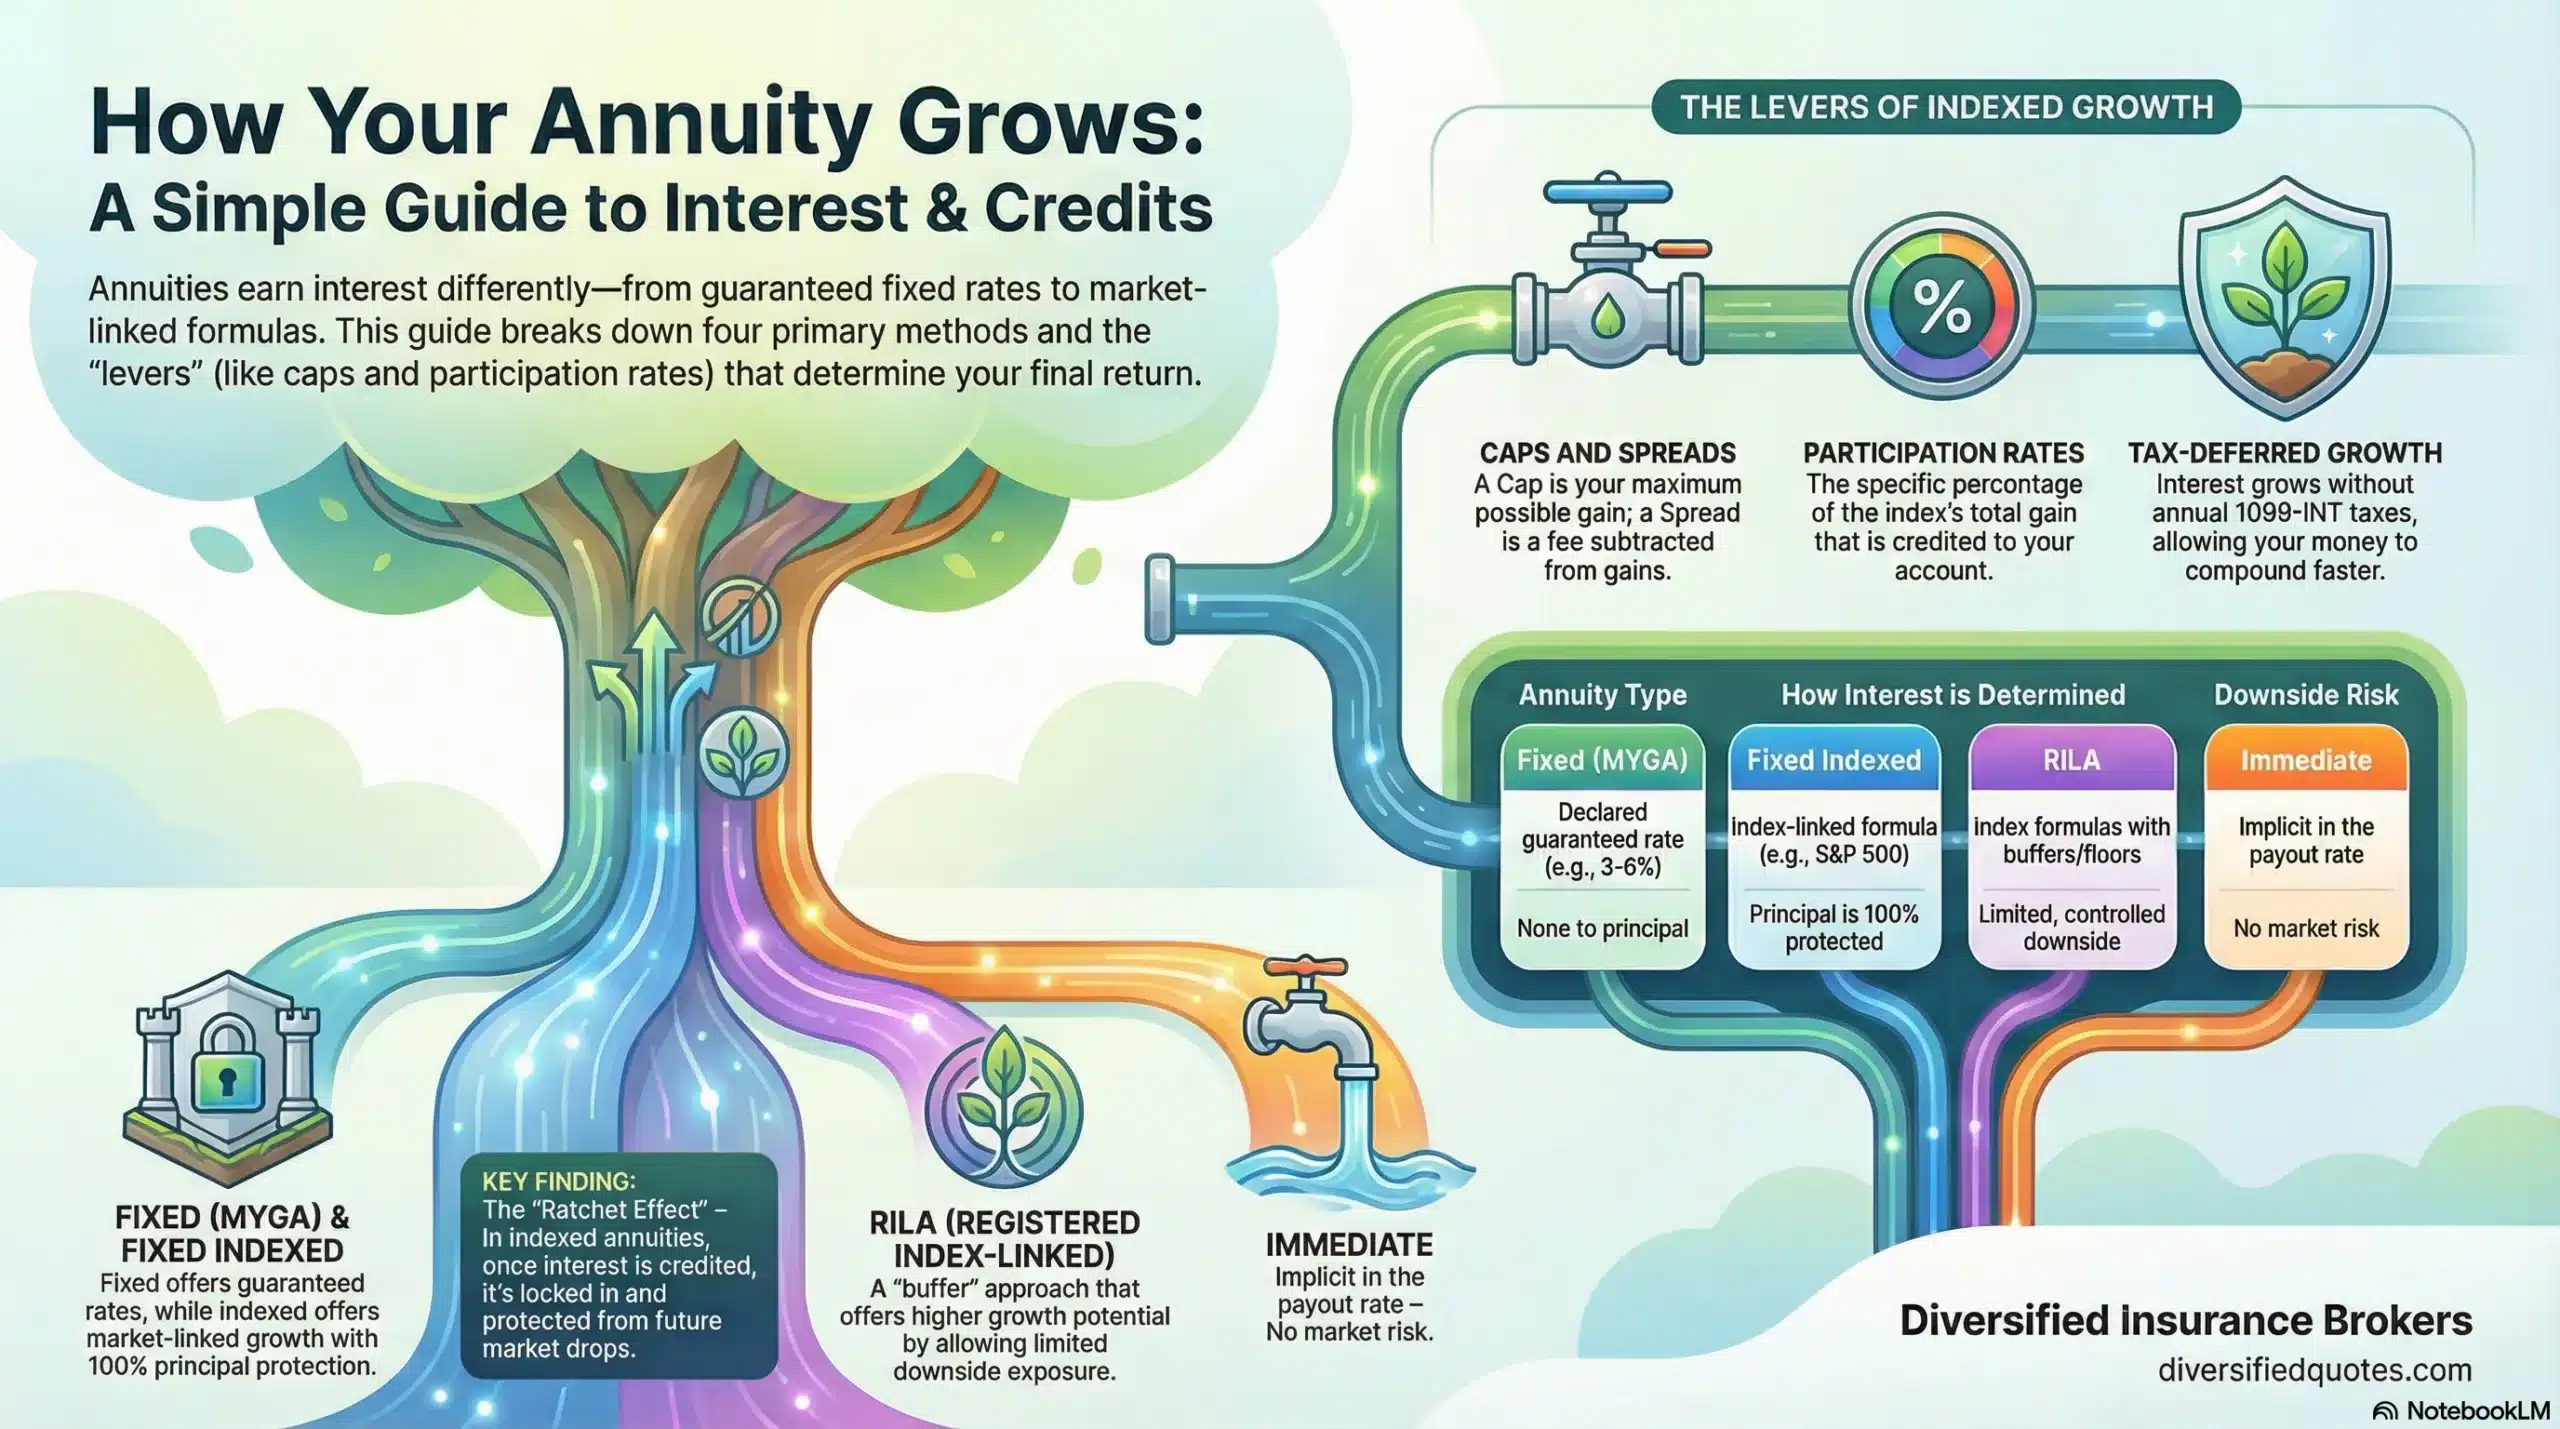
This design ties your future income directly to how well the contract’s crediting strategies perform. Our guide on how annuities earn interest explains caps, participation rates, and fixed rates. Since roll-ups depend on credited interest, the renewal rates the company sets during the waiting period will shape the income you eventually receive. Over a ten-year wait, those renewal decisions add up.
What Happens in a Flat or Down Year
The other side of a performance-based roll-up is what happens when markets disappoint. If the indexes behind your strategies fall or finish flat over a crediting term, those strategies credit zero for that term. Your account value does not drop because of the index loss, which is the core protection of any fixed indexed annuity, but with no credited interest there is nothing for the 200 percent multiple to work on, and the benefit base stands still.
That is a real difference from riders that add a set percentage to the benefit base every year regardless of markets. Those designs give you a predictable income figure years in advance. PillarMark trades that predictability for the chance of faster growth in strong years. Over a ten-year waiting period, a few weak years could leave the benefit base well below what a fixed roll-up would have produced, while a run of strong years could leave it well above.
Because PillarMark has no rider charge, a flat year is less painful than it would be with a fee-based rider. The account value holds steady instead of shrinking by a fee, and the benefit base simply waits for the next credit. Our explanation of how indexed annuities handle downturns covers the zero floor in more detail. When you look at illustrations, ask to see both a strong historical period and a weak one, so you understand the range of incomes the design could produce.
Turning On Income
Once the ten-year mark or age 85 arrives, you can activate lifetime income at any time. From then on, the MultiRider delivers an annual withdrawal benefit for as long as you live, calculated by applying a payout percentage to the benefit base. The product materials we reviewed do not publish those payout percentages, which usually depend on your age when income starts and on whether the payments cover one life or two.
Activation does not require handing your account value to the insurer. Withdrawals come out of the account value first, and you keep access to whatever remains, subject to the contract’s rules. If the account value eventually runs dry, the insurer continues the payments for life from its own resources. That is the core promise of a lifetime withdrawal benefit and the main reason to buy one.
You are not required to start income the moment you become eligible. Waiting longer can raise the payout percentage and give the benefit base more years of roll-ups, although the right choice depends on your other income and your health. Our article on whether to annuitize or use an income rider compares this approach with traditional annuitization. Ask for illustrations showing income at the first eligible date and at a few later dates, for single and joint payments, before deciding when to start.
Payments That Can Grow After Income Begins
Activation does not end the benefit base’s growth. After income starts, PillarMark’s roll-up rate steps down from 200 percent to 100 percent, but it keeps applying to credited interest. In a year when your strategies earn a credit, the benefit base can rise, and so can the income it supports. The product materials describe this as an increasing payout opportunity.
The materials add that this 100 percent roll-up keeps going after the account value has been fully drawn down. Once the account is empty there is no ordinary account value earning interest, so the rider must define how increases are measured from that point. That definition is one of the most important things to read in the rider, and it is fair to ask your advisor to show, in writing, how increases would be calculated in that situation and whether any limits apply.
Income that can step up over time helps address a weakness of most lifetime income products, which is that a fixed payment buys less each year as prices rise. PillarMark does not guarantee increases, and in weak crediting years income would stay level. But for a retiree who may live into their nineties, the possibility of rising payments has real value. Factor in that possibility cautiously, and build your budget on the guaranteed income figure rather than on projected increases.
Want guaranteed and projected PillarMark income side by side?
Request a PillarMark Illustration
Care Benefits Built Into the Rider
PillarMark’s MultiRider includes two benefits for people who later need help with daily life. Eligibility requires either confinement or an impairment covering at least two ADLs out of the six, plus a two-year wait from the issue date. The benefit you can use hinges on whether you have already activated income.
These features are especially relevant to PillarMark buyers. Many of them are planning a decade or more ahead, and the odds of needing care rise with every year of age. A benefit that responds to a care need, without a separate premium, can be a valuable backstop for someone who has no long-term care insurance or who could not qualify for it. Our look at annuities instead of long-term care insurance explains where annuity-based care features fit in a broader plan.
It is important to keep expectations realistic. These are not long-term care insurance policies. They do not reimburse expenses, the pre-income benefit is limited by the benefit base and a cap, and they draw on the one benefit base that also sets your income and the enhanced death benefit. One of them also ends the contract’s other benefits when elected. Study how the rider defines confinement and impairment, and ask how the insurer confirms eligibility, because those details decide whether the benefit pays when you need it.
Using the Care Benefit Before Income Starts
If a qualifying care need arises during the waiting period, before you have activated income, PillarMark offers its activities of daily living benefit. The product materials state that it pays the smaller of two amounts, the benefit base or account value times the benefit base cap, spread over seven years in monthly installments.
This benefit is especially important for PillarMark buyers because of the waiting period. Without it, someone who needed care in year six could not turn on lifetime income for several more years. The care benefit offers a path to payments that are tied to the benefit base during exactly the period when income is locked. The size of the benefit base cap determines how much more than the account value it can pay, and the materials we reviewed do not state that cap, so obtain it from the rider or an illustration.
Choosing this benefit is permanent. According to the product materials, electing it terminates all other contract benefits, including the lifetime income guarantee and the enhanced death benefit. You receive a defined stream of payments over seven years instead. That can be the right decision when care costs are heavy and immediate, but it deserves a careful comparison with the alternatives, including waiting to activate income or using a surrender charge waiver to access account value.
The 225 Percent Income Boost
For buyers who have already activated lifetime income, PillarMark’s enhanced income benefit provides a different kind of help. If you later meet the confinement or impairment conditions, the rider can raise your annual withdrawal benefit amount to 225 percent of its normal level. A buyer receiving a hypothetical $8,000 a year could see that rise to $18,000 a year while the boost applies.
The increase lasts until the account value is used up. After that, the withdrawal benefit drops back to its standard 100 percent level and continues for life. Larger withdrawals drain the account value faster, so the length of the boosted period depends on how much account value is left when the care need begins. Someone who activates income at the first opportunity and draws for many years before needing care may have a shorter boost than someone who needs care soon after activation.
Unlike the pre-income care benefit, the product materials do not describe the 225 percent boost as ending other benefits, although the rider contract governs. Our page explaining a skilled nursing facility rider covers similar confinement features found in other annuities. Ask for an illustration that models the boost at a few ages so you can see how long it might last.
Legacy Planning With the Enhanced Death Benefit
PillarMark also uses its benefit base to offer an enhanced death benefit. If the owner dies after two contract years and account value remains, the beneficiary may elect it. The materials define it as whichever is smaller, the benefit base or account value times a benefit base cap, paid in monthly installments over five years.
The design gives heirs a choice between speed and size. They can accept the contractual death benefit in a single payment or as an annuity, or opt for the enhanced benefit when it is bigger and they are willing to receive it over five years. Hawaii, Minnesota, Ohio, Pennsylvania, and Utah use a different calculation for the enhanced amount, and electing it ends the contract’s other benefits, which mainly affects a spouse who might prefer to continue the contract.
Because this benefit depends on account value remaining, buyers who plan to draw income for many years should not count on it. It suits people for whom leaving money behind is a central goal and who may never fully use the income rider. If part of that legacy is meant for charity, a charitable gift annuity is a different tool worth comparing, since it pairs lifetime payments with a gift to a qualified charity.
The Contractual Death Benefit and Minimum Value Floor
Separate from the rider, every PillarMark contract pays a contractual death benefit equal to the higher of two amounts, namely your account value or your guaranteed minimum value. It requires no waiting period and no election, and heirs may receive it all at once or as a series of annuity payments.
The guaranteed minimum value is a contractual floor calculated from your premium. The product materials describe it as 87.5 percent of premium, reduced by withdrawals and by a $50 annual contract charge, with interest added at the minimum value rates listed in the contract’s schedule. In ordinary circumstances, the account value will be larger, because credited interest builds over time and PillarMark has no rider fee pulling it down.
The floor still deserves a moment of attention. It is not 100 percent of premium, so the contract does not promise a full return of premium in every scenario. Cashing out early can also cost you through surrender charges and MVA changes, separate from the minimum value used for the death benefit. When you review a PillarMark illustration, look at the guaranteed values alongside the projected values, and ask how the floor interacts with surrenders and partial withdrawals so there are no surprises later.
The Allocation Menu
PillarMark lets you divide your premium among ten allocation options. One is a fixed account that credits a declared rate for one-year terms. The other nine are index-linked strategies using point-to-point crediting, where the index level at the start of a term is compared with its level at the end.
Five indexes are available. The S&P 500 appears in a one-year capped strategy. The S&P 500 IQ Index appears in one-year capped and participation rate strategies and a two-year participation rate strategy. Both the Bloomberg Bitcoin US 100 10% Index and the Solactive Nasdaq-100 DART 10% Index come with one-year and two-year participation rate strategies. The Nasdaq-100 HiCap Index appears in a one-year capped strategy.
A cap limits how much of an index gain is credited, while a participation rate passes along a set share of the gain. Two-year strategies measure the gain over a longer stretch and credit it at the end, which usually supports higher participation rates but means nothing is credited at the first anniversary. Because PillarMark’s roll-up feeds on credited interest, a two-year strategy likely means the benefit base waits two years for each roll-up, which is worth confirming in the rider. The company resets caps and participation rates at each term within contractual minimums, so today’s rates are not guaranteed to last for the life of the contract.
Inside the Indexes
The five indexes behind PillarMark’s strategies range from a familiar benchmark to newer, engineered designs. The S&P 500 is the standard gauge of large U.S. company stocks. The S&P 500 IQ Index mixes S&P 500 exposure with cash and adds a 15 percent volatility control overlay, and the words 0.5% Decrement in its formal title signal a built-in annual deduction of half a percent that reduces its return.
Nasdaq’s published methodology for the Nasdaq-100 HiCap Index shows it tracks Nasdaq-100 futures and shifts its exposure daily based on a volatility measure, anywhere from zero to twice the futures exposure. The company describes the Solactive Nasdaq-100 DART 10% Index as a diverse mix of large U.S. stocks, Treasuries, and gold, and the Bloomberg Bitcoin US 100 10% Index as a way to pair traditional equity growth with exposure to bitcoin.
A bitcoin-linked option is uncommon in fixed indexed annuities, and it may draw attention for that reason alone. Inside PillarMark, it carries the same zero floor as every other strategy, so a bitcoin decline cannot reduce your account value, though it can produce a zero credit. Volatility-controlled indexes like these can support higher participation rates, but they often trail their underlying markets in strong rallies, and decrements reduce returns further. Compare strategies on how they might have credited over many years, not on the headline participation rate alone.
Choosing a Blueprint
PillarMark’s Allocation Blueprints are three ready-made mixes for buyers who do not want to build their own allocation. Foundation is labeled conservative, Keystone moderate, and Pinnacle aggressive. Each spreads the premium across several one-year strategies in proportions the company sets.
The main difference among them is how much they rely on the fixed account versus the bitcoin-linked strategy. Based on the materials we reviewed, Foundation held the biggest fixed account slice and no bitcoin-linked strategy, Keystone included a small bitcoin-linked slice and a reduced fixed account, and Pinnacle dropped the fixed account entirely in favor of the largest bitcoin-linked slice. Every blueprint also carries the HiCap and DART strategies along with all three S&P-based strategies.
According to the launch announcement, bundling through a blueprint may earn better rates and caps than picking the same strategies one by one, and the rate materials we reviewed reflected that. The trade-off is less control over the mix. For PillarMark buyers, the blueprint decision has a second effect: because the roll-up depends on credited interest, the blueprint’s results feed directly into the benefit base during the waiting period. Ask how blueprint renewal rates are set over time and whether you can move between blueprints and individual strategies at each anniversary.
Access to Your Money Along the Way
PillarMark is designed to be held for the long haul, but it does provide some access before income starts. Up to 10 percent can be taken penalty-free in year one. After that, the allowance can accumulate to a ceiling of 20 percent when the prior year was withdrawal-free. If the contract has a required minimum distribution, that amount can be taken instead without a surrender charge.
Withdrawals during the waiting period come with a cost beyond any charge. They reduce the account value, and they typically reduce the benefit base as well, which lowers the income the rider will eventually pay. Since PillarMark’s main purpose is future income, taking money out along the way works against it. A separate emergency reserve is a better source for unexpected needs.
Age also matters. Because buyers can be as young as 50 at issue, some owners will hold it before age 59 and a half, when a 10 percent federal tax penalty can apply to taxable withdrawals in addition to ordinary income tax. Our guide to the IRS penalty for early withdrawals explains when it applies and the exceptions. For most PillarMark buyers, planning to leave the money untouched until income starts is the cleanest approach.
The Surrender Schedule and Renewing MVA
PillarMark’s surrender schedule lasts ten years. Per the product materials, the charge is 10 percent in year one, 9.40 in year two, 8.40 in year three, 7.35 in year four, 6.35 in year five, 5.30 in year six, 4.25 in year seven, 3.20 in year eight, 2.15 in year nine, and 1.05 in year ten, with nothing charged from year eleven on. Individual states may require different schedules.
The market value adjustment works alongside that schedule. When you withdraw more than the penalty-free amount or surrender the contract, the MVA moves the payout up or down in response to interest rate shifts since the present MVA period began. PillarMark’s first MVA period covers the initial ten years, a new ten-year period starts with each tenth contract anniversary, and the adjustment is suspended only for the 30 days before each new period begins. See our breakdown of surrender charges and the MVA for more on how they work together.
For PillarMark, the renewing MVA intersects with the income clock, because many buyers become eligible for income at about the time the first MVA period ends. If you are thinking about moving the money rather than taking income, note that the first MVA-free window falls in the 30 days before the tenth anniversary, which is still contract year ten, so the 1.05 percent surrender charge would apply to amounts above the free allowance. Once surrender charges reach zero in year eleven, a new MVA period has already begun, so a large withdrawal can still be adjusted. Confirm the exact window dates and charges in your contract.
Waivers for Serious Health Events
PillarMark includes three surrender charge waivers. One applies to nursing home confinement, one to terminal illness, and one to home health care. Each lets you reach your account value without surrender charges if you meet the waiver’s conditions, which typically include minimum waiting periods and specific medical definitions that can vary by state.
These waivers address a different need than the rider’s care benefits. The rider’s benefits provide payments tied to the benefit base, while the waivers remove the surrender penalty on access to your own account value. In some situations, using a waiver to withdraw account value may be a better choice than electing the pre-income care benefit, because, unlike the pre-income care benefit, the materials do not describe a waiver withdrawal as ending the contract’s other benefits. In others, the care benefit may provide more total value. The right answer depends on the numbers at the time.
Ask several questions before buying. How long after issue does each waiver become available? What documentation does the insurer require? Does the market value adjustment still apply to a waiver withdrawal? How does a waiver withdrawal affect the benefit base and the enhanced death benefit? Getting these answers in writing now is much easier than trying to sort them out during a health crisis, when decisions need to be made quickly.
Tax Deferral and PillarMark
Like other deferred annuities, PillarMark grows tax deferred. Credited interest is not taxed each year, so earnings can compound on themselves until money comes out. Over a ten-year waiting period, that deferral can make a meaningful difference compared with a taxable account, especially for someone in a higher tax bracket during their working years. Our article on how tax deferral helps compounding shows the effect over long periods.
For nonqualified money, withdrawals are generally treated as coming from earnings first, which are taxed as ordinary income, before any return of your original premium. Lifetime income taken through the rider follows the same pattern. Inside an IRA or other qualified account, PillarMark follows the account’s rules, so withdrawals are generally fully taxable and required minimum distributions apply.
Taxes also affect heirs. Beneficiaries generally owe ordinary income tax on the earnings portion of a nonqualified annuity’s death benefit, and on the full amount from a qualified annuity, rather than receiving a step-up in basis. The enhanced death benefit’s five-year payout can spread that tax over several years. Because individual situations vary, coordinate PillarMark with your tax advisor, particularly if you plan to use it for both income and legacy goals.
Not sure whether PillarMark or SpireMark fits your timeline?
Compare the Two Designs
PillarMark or SpireMark
PillarMark and SpireMark are built on the same chassis. They share issue ages, premium limits, crediting strategies, blueprints, the surrender schedule, the renewing MVA, waivers, care benefits, and the enhanced death benefit. What separates them is the rider, and the rider differences all trace back to one question: how soon do you need income?
PillarMark’s MultiRider has no added charge, a 50 percent bonus, and a 200 percent roll-up before income, but income waits for ten years or age 85. When the two products launched, PillarMark’s caps were a bit higher than SpireMark’s on several strategies and participation rates were identical; because both roll-ups depend on credited interest, that difference can reach the benefit base too. The SpireMark income annuity uses the MultiRider Max, which costs 1.25 percent of the benefit base each year and offers a 45 percent bonus with a 250 percent roll-up, but it allows income to start 30 days after issue. Both continue rolling up at 100 percent after income starts.
If you are sure this income can wait at least a decade, PillarMark’s lack of a rider charge is a significant advantage that compounds over time. If there is any real chance you will want income sooner, and you will not reach age 85 first, only SpireMark can provide it, and paying the charge buys that flexibility. Running illustrations of both at the same premium and start age is the clearest way to see which produces more income, more cash value, and more for heirs in your situation.
Matching PillarMark to Your Retirement Timeline
PillarMark works best as one layer in a retirement income plan, not as the whole plan. A common structure uses Social Security, a pension, or other savings to cover the early years of retirement, while PillarMark grows quietly in the background and becomes a dependable income source later. That later income can replace a pension bridge that ends, cover rising health costs, or protect against running short if you live a long time.
Consider a 60-year-old who plans to retire at 62, draw from savings and part-time work, and claim Social Security at 70. PillarMark purchased at 60 could start income at 70, alongside the larger Social Security benefit, giving that person two lifetime income sources in their later years. Someone who is already retired and needs more income now would be better served by a different design.
Our guide on choosing an annuity by your timeline walks through how different annuity types fit different stages. The key is to map out your income needs year by year before buying. If a ten-year gap fits naturally into that map, PillarMark deserves serious consideration. If you would have to stretch your plan to accommodate the waiting period, look at other options first.
Who PillarMark Suits and Who Should Skip It
PillarMark suits buyers aged 50 to 85 who want guaranteed lifetime income in the future, can comfortably wait ten years or until age 85 to start it, and prefer to avoid annual rider fees. It suits people who value care-related benefits built into an income plan, and those who would like the option of an enhanced death benefit for heirs if they never need the income. It also fits people who accept the risks of a young carrier and will size their purchase sensibly, often within their state’s guaranty association limit.
PillarMark does not suit anyone who might need lifetime income from this money within the next ten years, unless they will reach age 85 sooner. It does not suit buyers who insist on an AM Best rating of A- or better, or those in states without a PillarMark approval, which includes every state where TruSpire lacks a license. People who may need large withdrawals during the surrender period should also look elsewhere.
Finally, PillarMark is not ideal for buyers who want predictable growth in their future income. Because the roll-up depends on credited interest, the eventual income is uncertain until you get there. Buyers who want a known income figure years in advance may prefer a rider with a fixed roll-up, or a deferred income annuity that locks in a payment from the start.
How Our Office Helps
Our work begins with your timeline. We map out what Social Security, pensions, savings, and work income will provide year by year, and identify any gap that lifetime income could fill. If that gap begins ten or more years from now, a deferred design like PillarMark may fit. If it begins sooner, we look at alternatives, including SpireMark and income annuities from other carriers.
When PillarMark is a candidate, we run illustrations at your eligible start date and a few later dates, compare guaranteed and projected income with competing products, and review how the care benefits and enhanced death benefit could work for your family. We discuss TruSpire’s ratings and the newness of the Malibu Life business plainly, and help you decide how much to place with it.
If you go ahead, we coordinate the application and any transfers, confirm that you receive the version of the contract approved in your state, and note the key dates, including when income becomes available and when the MVA window opens. During the waiting period, we can review renewal rates and benefit base growth with you each year so there are no surprises when income time arrives. Our recommendation is shaped by your plan, and we will tell you if PillarMark is not the right fit.
Ready to see how PillarMark fits your retirement plan?
Talk Through PillarMark
Financial Protection Essentials
More reading on planning income for the later years of retirement.
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
When can PillarMark start paying lifetime income?
Income under the MultiRider becomes available after ten contract years or at age 85, whichever arrives first. A 60-year-old buyer could start at 70, while an 80-year-old buyer could start at 85. You can also wait beyond the first eligible date, which may raise the income amount.
Can PillarMark lose value?
An index decline cannot lower the account value, and interest is locked in once credited. What you receive can still shrink through withdrawals, surrender penalties, or an MVA, and every guarantee depends on TruSpire’s claims-paying ability. Read more in our guide on whether an indexed annuity is safe.
Is PillarMark backed by the FDIC?
No. PillarMark is an insurance contract issued by TruSpire, and its backstop if the insurer fails is the guaranty association in your state, within its coverage limits. Learn why in our explanation of whether annuities are FDIC insured.
How is PillarMark taxed if I use savings rather than an IRA?
Growth is tax deferred. When you withdraw, earnings are treated as coming out first, and that portion is taxed as ordinary income before your original premium comes back tax free. A 10 percent IRS penalty can also apply to taxable amounts withdrawn under age 59 and a half. See our page on non-qualified annuity taxation for details.
Can I move an existing annuity into PillarMark?
Usually, yes. A tax-free exchange can move value from one annuity to another without current income tax, but compare surrender charges, rider values, and death benefits on the old contract first. Read how 1035 exchanges work before you start one.
How does the market value adjustment affect PillarMark?
The MVA adjusts what you get from a surrender, or from withdrawals above the free amount, up or down as interest rates move. It runs in ten-year periods that renew at each tenth anniversary, with a 30-day window before each new period when it does not apply. Our explainer on the market value adjustment covers the details.
Can PillarMark income be paid monthly?
Most income riders let you choose how often withdrawals are paid, but the materials we reviewed do not list PillarMark’s payment frequencies, so confirm them with the illustration. Our guide to an annuity for monthly retirement income explains how monthly income plans typically work.
How much should I put into PillarMark?
Start with the income gap you expect a decade from now, then size the premium to cover part of it while keeping a liquid reserve elsewhere. Many buyers also stay within their state’s guaranty association limit. Our guide to retirement income needs can help you estimate that gap.
What would my beneficiaries receive from PillarMark?
They can take the contractual death benefit, whichever figure is higher between account value and the guaranteed minimum value, or, after two contract years and if account value remains, choose the enhanced death benefit, which arrives in monthly installments across five years. For more, read about what beneficiaries receive from annuities.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to Best Fixed Indexed Annuity Products — covering individual fixed indexed annuity product reviews from top-rated carriers from 100+ carriers.
Last Reviewed: October 21, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
