Malibu Life SpireMark Fixed Indexed Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Malibu Life SpireMark Fixed Indexed Annuity
SpireMark Fixed Indexed Annuity, issued by Malibu Life Insurance Company, is built for people who want lifetime income they can switch on early and still watch grow. Income can begin as soon as 30 days after the contract is issued, the rider’s benefit base starts with a 45 percent bonus, and before income begins the benefit base rolls up at 250 percent of the interest the contract earns. That design comes with a price: the MultiRider Max rider costs 1.25 percent of the benefit base every year. Whether SpireMark makes sense comes down to one trade-off, how much you value early, flexible income against an ongoing rider charge that its sister product, PillarMark, does not have. Everything else on this page sits on top of that.
AM Best Rating Disclosure
SpireMark is issued by TruSpire Retirement Insurance Company, a Malibu Life USA company, which AM Best rates B++ (Good) for financial strength. That grade is fifth on AM Best’s scale of thirteen and sits just under the A- level that many careful retirement savers treat as a floor. Every guarantee in this annuity, from principal protection to lifetime income, rests on TruSpire’s ability to pay, so check the insurer’s current rating before you buy.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this analysis of SpireMark reflects how our office evaluates income-focused fixed indexed annuities. Working as an independent annuity broker, we set SpireMark’s rider, crediting menu, and contract terms beside competing income annuities, including ones from more highly rated insurers, to show whether its early-income flexibility justifies the cost and the carrier trade-off.
Want current SpireMark rates and an income illustration?
Get a SpireMark Illustration
SpireMark at a Glance
| Feature | How SpireMark Handles It |
|---|---|
| Issuer | TruSpire Retirement Insurance Company, a Malibu Life USA company, Irving, Texas |
| Contract Type | Ten-year modified single premium deferred fixed indexed annuity |
| Issue Ages | 50 through 85, for qualified and nonqualified money |
| Premium | $25,000 minimum; additions of at least $2,000 allowed in the first contract year only; $2 million per owner without home office approval |
| Income Rider | MultiRider Max, a guaranteed lifetime withdrawal benefit; see what an income rider is |
| Rider Charge | 1.25 percent of the benefit base, applied annually at the start of each contract year |
| Benefit Base Bonus | 45 percent |
| Roll-Up Before Income | 250 percent, tied to interest credited to the contract |
| Earliest Income Start | 30 days after the contract is issued |
| Roll-Up After Income Starts | 100 percent, continuing even after the account value reaches zero |
| Care Benefits | Available after a two-year wait, upon confinement or impairment in 2 of 6 ADLs |
| Withdrawal Access | 10 percent in year one, building up to 20 percent from year two, or the contract’s RMD; see annuity free withdrawal rules |
| Surrender Charge Waivers | Nursing home, terminal illness, and home health care |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Issues SpireMark
The insurer behind SpireMark is TruSpire Retirement Insurance Company, domiciled in Texas and headquartered in Irving. TruSpire operates under the Malibu Life USA brand, which is the name used for the American retail annuity operation of Malibu Life Holdings Limited, a London-listed holding company with close ties to the investment firm Third Point. Malibu Life Holdings does not sell products in the United States itself, so TruSpire alone is responsible for the guarantees in your contract.
AM Best grades TruSpire B++ (Good), and KBRA assigns it an A- (Strong). Both agencies point to strong capital relative to the company’s small legacy block and to support from its parent. KBRA flags the execution risk that comes with launching a new annuity business, and AM Best says it will monitor how the business plan is carried out. SpireMark is one of the first two products released under the Malibu Life USA name, so the company does not yet have a long record of setting renewal rates or paying rider benefits on this design.
Our review asking whether Malibu Life is a good company covers the ownership history, ratings, capital support agreement, and investment approach in depth. Malibu Life USA also publishes a short overview of its fixed index annuities. TruSpire holds licenses in 43 states plus D.C., yet SpireMark’s own approval list is shorter, so confirm availability where you live before going further.
How SpireMark Is Put Together
SpireMark has two layers. The base layer is a fixed indexed annuity: your premium goes into an account value that earns interest from a fixed account, from index-linked strategies, or from both. Index credits are never negative, so the account value does not fall when an index declines, although withdrawals, surrender charges, the market value adjustment, and the rider charge can all reduce it. The contract runs on a ten-year surrender schedule.
The second layer is the MultiRider Max rider, a guaranteed lifetime withdrawal benefit. The rider tracks a separate number called the benefit base. The benefit base is not money you can withdraw or surrender. It is a calculation value that the rider uses to set your lifetime income, your care-related benefits, and the enhanced death benefit. Marketing materials label it a trifecta, meaning a single benefit base supporting three separate benefits.
Understanding that split is the key to understanding SpireMark. Bonuses and roll-ups grow the benefit base, not the cash in your account. Your account value is what you would receive if you surrendered, subject to charges, and it, or the guaranteed minimum value if that is higher, sets the standard death benefit. Our explanation of how a GLWB rider works walks through the relationship between the two values in more detail. When you compare SpireMark with other income annuities, compare the income each one would pay at your age and start date, not the size of the benefit base.
What the MultiRider Max Charge Costs
The MultiRider Max rider carries an annual charge of 1.25 percent. According to the product materials, the charge percentage is multiplied by the benefit base and applied at the beginning of each contract year. Because the benefit base is usually larger than the account value, especially once the bonus and roll-ups are added, the dollar cost is higher than 1.25 percent of the money actually in your contract.
A simple hypothetical shows the effect. On a $100,000 premium, a benefit base that starts 45 percent higher would be $145,000, and a 1.25 percent charge on that amount would be $1,812.50 for the year. As the benefit base rolls up over time, the dollar charge grows with it, even in years when the account value earns little or nothing. That charge is generally taken from the account value, which slows the growth of your cash and can reduce what is left for heirs or for a surrender.
A rider charge is not automatically bad. It pays for guarantees the insurer would otherwise not provide, and SpireMark’s charge buys early access to income and a higher roll-up rate than its no-charge sister product offers. The question is whether you will use those features. For more on weighing these costs, see whether income riders have fees and how they are typically calculated. If you are certain you will not need income for ten years or more, PillarMark’s no-charge rider deserves a close look.
The 45 Percent Benefit Base Bonus
When SpireMark is issued, the rider adds a 45 percent bonus to the benefit base. The bonus is a feature of the income calculation, not a deposit into your account value. You cannot withdraw it, it does not increase the cash you would receive on surrender, and it does not raise the standard death benefit. What it does is start the benefit base higher, which in turn raises the lifetime income the rider would pay at any given payout percentage.
Benefit base bonuses are common on income-focused annuities, and their size varies widely between products. A larger bonus is not the same as a better product, because the payout percentages, the roll-up design, and the rider charge all affect how much income you would actually receive. Two contracts with different bonuses can produce very similar income once every factor is included, and occasionally the one with the smaller bonus pays more.
That is why the only meaningful comparison is a side-by-side income illustration for the same premium, the same age, and the same income start date. Our guide to how annuity bonuses work explains the difference between premium bonuses, which add to account value, and benefit base bonuses like SpireMark’s. If an advisor highlights the 45 percent figure without showing the income it produces, ask to see the income numbers before deciding anything.
A Roll-Up Driven by Credited Interest
Many income riders grow the benefit base by a fixed percentage each year until income starts. SpireMark takes a different approach. Its roll-up is tied to performance: before income begins, the benefit base rises based on the interest credited to the contract, at a roll-up rate of 250 percent. The launch announcement for the product line describes the benefit base as able to increase over time based on interest credited, with roll-ups both before and after income activation.
A simplified way to picture it: if the contract earned a 4 percent credit in a given year, a 250 percent roll-up would translate that into roughly a 10 percent increase for the benefit base. If the contract earned nothing because the index fell or stayed flat, the benefit base would not roll up that year. The rider contract defines exactly how the multiple is applied, including whether it works on the credited rate or on the dollars credited, so confirm the method on an illustration before you buy.
This design rewards strong crediting years and gives nothing in weak ones. That makes the crediting strategies you choose, and the caps and participation rates the company sets each year, important to the income you eventually receive. Our comparison of roll-up rates versus payout rates explains why a high roll-up figure alone does not tell you how much income a rider will produce.
Income Starting 30 Days After Issue
The feature that sets SpireMark apart is timing. Under the MultiRider Max rider, you can switch on lifetime income once the contract is 30 days old. That makes SpireMark usable as a near-term income source for someone who is retiring now, while still allowing a later start for someone who wants to wait. You choose when to activate income, within the contract’s rules.
Once income starts, the rider pays a withdrawal benefit amount each year for life, based on the benefit base and a payout percentage. The product materials we reviewed do not list the payout percentages, which typically depend on age at the start of income and on whether the income covers one life or two. Ask for an illustration that shows the exact amount at your age and preferred start date, and for both single and joint income if you are married.
Income taken through the rider is a series of withdrawals from your account value until that value runs out. After that, the insurer keeps paying for life from its own funds. That is different from annuitization, where you hand over the account value in exchange for a stream of payments and give up access to the balance. Our comparison of annuitization versus lifetime withdrawals explains the trade-offs between the two approaches.
When Waiting Still Makes Sense
Being able to start income early does not mean you should. Every year you wait gives the benefit base another chance to roll up at 250 percent of credited interest, and payout percentages on most income riders rise with age at the start of income. Waiting a few years can produce noticeably higher lifetime income than starting right away, especially if the contract enjoys good crediting years in the meantime.
The cost of waiting is the rider charge. Each year before income begins, you pay 1.25 percent of a growing benefit base, and in a flat year you pay it without any roll-up to show for it. So the decision is a balance between the value of earlier income, the potential growth from waiting, and the charges paid in the meantime. Running illustrations for several start dates shows that balance more clearly than any rule of thumb.
It also helps to think about what else will fund your retirement. If Social Security, a pension, or other savings will cover your needs for a few years, SpireMark can sit and grow until you need it. If you need income from this money right away, SpireMark’s early access becomes its main advantage. Either way, the start date is one of the most important decisions you will make with this contract, and it deserves careful thought rather than a default choice.
Income That Can Keep Climbing
Many lifetime income riders pay a level amount once income begins. SpireMark is designed to give that amount room to grow. After income starts, the roll-up rate drops from 250 percent to 100 percent, but it keeps working, so the benefit base can continue to rise in years when the contract earns credited interest. A higher benefit base means a higher withdrawal amount, which is what the product materials call an increasing payout opportunity.
The materials also state that this post-income roll-up continues even after the account value reaches zero. That is an unusual promise, because once the account is depleted there is no account value left to earn interest in the ordinary sense. The rider contract explains how increases are measured at that stage, and that is one of the first details to confirm before relying on rising income in your planning. Do not assume a particular rate of increase; ask how it would have worked in past index environments and what happens in years with no credit.
Rising income is valuable because retirement costs tend to climb over time. A level payment loses purchasing power to inflation year after year, while a payment that can step up in good years helps offset that loss. It is not an inflation guarantee, however. In weak crediting years the income would not increase, and how much it grows depends heavily on the caps and participation rates the company sets on your chosen strategies each year.
Want to see how SpireMark’s income would look at your age?
Request My Income Numbers
Two Care Benefits Triggered by Daily Living Needs
SpireMark includes two benefits tied to health, both triggered by confinement or by an impairment affecting two of the six activities of daily living. Those activities generally include bathing, dressing, eating, toileting, transferring, and continence, and our guide to the activities of daily living explains how insurers assess them. Neither benefit is available during the first two years after the contract is issued.
Which benefit applies depends on whether lifetime income has started. If income has not yet started, the pre-income care benefit turns an amount linked to the benefit base into seven years of monthly installments. Once income is running, the enhanced income benefit can lift yearly income to 225 percent of its usual level. The product materials describe this pair as two benefits for life’s what-ifs, and they are a meaningful part of SpireMark’s value for people worried about future care costs.
These features are not long-term care insurance. They do not reimburse specific care expenses, they come with their own rules and limits, and electing the pre-income benefit ends the contract’s other benefits. They also rely on the same benefit base that drives income and the enhanced death benefit. Still, for someone who could not qualify for traditional long-term care coverage, or who wants some care protection built into a retirement income plan, they may add real value; ask whether any health questions apply when the contract is issued. Read the rider’s definitions of confinement and impairment carefully before counting on them.
The Activities of Daily Living Benefit Before Income
If you qualify for care benefits before you have started lifetime income, SpireMark offers the activities of daily living benefit. According to the product materials, it equals the lower of two figures: the benefit base, or the account value multiplied by a benefit base cap. The amount is paid in monthly installments over seven years.
The benefit base cap is the factor that limits how far this benefit can exceed your actual account value. The quick reference materials we reviewed do not state the cap’s value, so it is a figure to obtain from the rider contract or an illustration. It matters a great deal: if the cap is modest, the benefit may be closer to your account value than the size of the benefit base suggests.
The most important rule is that electing this benefit terminates all other contract benefits. Once you choose it, you give up the lifetime income guarantee, the enhanced income benefit, and the enhanced death benefit, in exchange for a defined payout over seven years. That can be the right choice if care costs are immediate and substantial, but it is a one-way decision. Before electing it, compare the seven-year payout with what lifetime income and the enhanced income benefit would provide, and consider your health outlook, your other resources, and what you want to leave behind.
The Enhanced Income Benefit After Income Starts
If you have already started lifetime income and later qualify through confinement or an impairment in two daily living activities, SpireMark’s enhanced income benefit can boost your yearly withdrawal benefit to 225 percent of what it would normally be. For someone receiving $10,000 a year in rider income, that would mean $22,500 a year while the benefit applies, a hypothetical figure for illustration only.
The enhanced amount continues until the account value reaches zero. At that point, the withdrawal amount returns to 100 percent of the normal amount, and lifetime income continues at that level. Because higher withdrawals draw down the account value faster, the enhanced period may be shorter than people expect, particularly if the account value is modest when the benefit begins. An illustration that models the enhanced benefit at different ages and account values can show how long it might last.
This benefit pairs naturally with SpireMark’s early income design. People who start income soon after buying are the ones most likely to be receiving withdrawals when a care need arises, and the enhanced amount can help cover higher costs without ending the lifetime guarantee. Unlike the pre-income benefit, the materials do not describe the enhanced income benefit as ending other contract benefits, but the rider contract controls. Confirm how it interacts with the death benefit and with the post-income roll-up before relying on it.
The Enhanced Death Benefit
SpireMark also offers an enhanced death benefit built on the same benefit base. Beneficiaries can choose it if the owner dies after the second contract anniversary, provided some account value is left at that point. According to the product materials, it equals the lower of the benefit base or the account value multiplied by a benefit base cap, and it is paid monthly over five years rather than in a lump sum.
That structure gives beneficiaries a choice. They can take the standard death benefit, paid as a lump sum or as annuity payments, or they can elect the enhanced benefit if it is larger and they are comfortable receiving it over five years. Electing the enhanced death benefit ends the contract’s other benefits, which matters mainly for a surviving spouse who might otherwise continue the contract.
Two practical notes are worth keeping in mind. First, because the enhanced benefit requires account value to remain, heavy withdrawals or long periods of rider income can eliminate it. Second, the calculation differs in some states, including Hawaii, Minnesota, Ohio, Pennsylvania, and Utah, according to the product materials. If leaving money to heirs is a priority, ask for an illustration showing how the enhanced death benefit would compare with the standard benefit at several points in time.
The Standard Death Benefit and Guaranteed Minimum Value
Every SpireMark contract carries a contractual death benefit: the larger of two figures, the account value and the guaranteed minimum value. Beneficiaries can take it as a lump sum or as annuity payments. This benefit does not depend on the rider and does not require any waiting period.
The guaranteed minimum value is the contract’s floor. According to the product materials, it equals 87.5 percent of premium, less withdrawals, less a $50 annual contract charge, plus interest credited at the annual guaranteed minimum value rates shown on the contract schedule. In most situations the account value will exceed this floor, because index and fixed credits accumulate over time. The guaranteed minimum value matters mainly in unusual cases, such as several years of zero credits combined with rider charges, where the account value could otherwise drift lower.
The guaranteed minimum value is also a reminder that fixed indexed annuities protect against index losses, not against every possible reduction. The account value can still be pulled down by rider fees, surrender penalties, MVA changes, and withdrawals. The guaranteed minimum value sets a contractual floor beneath those reductions for death benefit and other purposes defined in the contract. When reviewing an illustration, look at both the guaranteed column and the non-guaranteed column so you understand the range of outcomes.
Ten Ways to Credit Interest
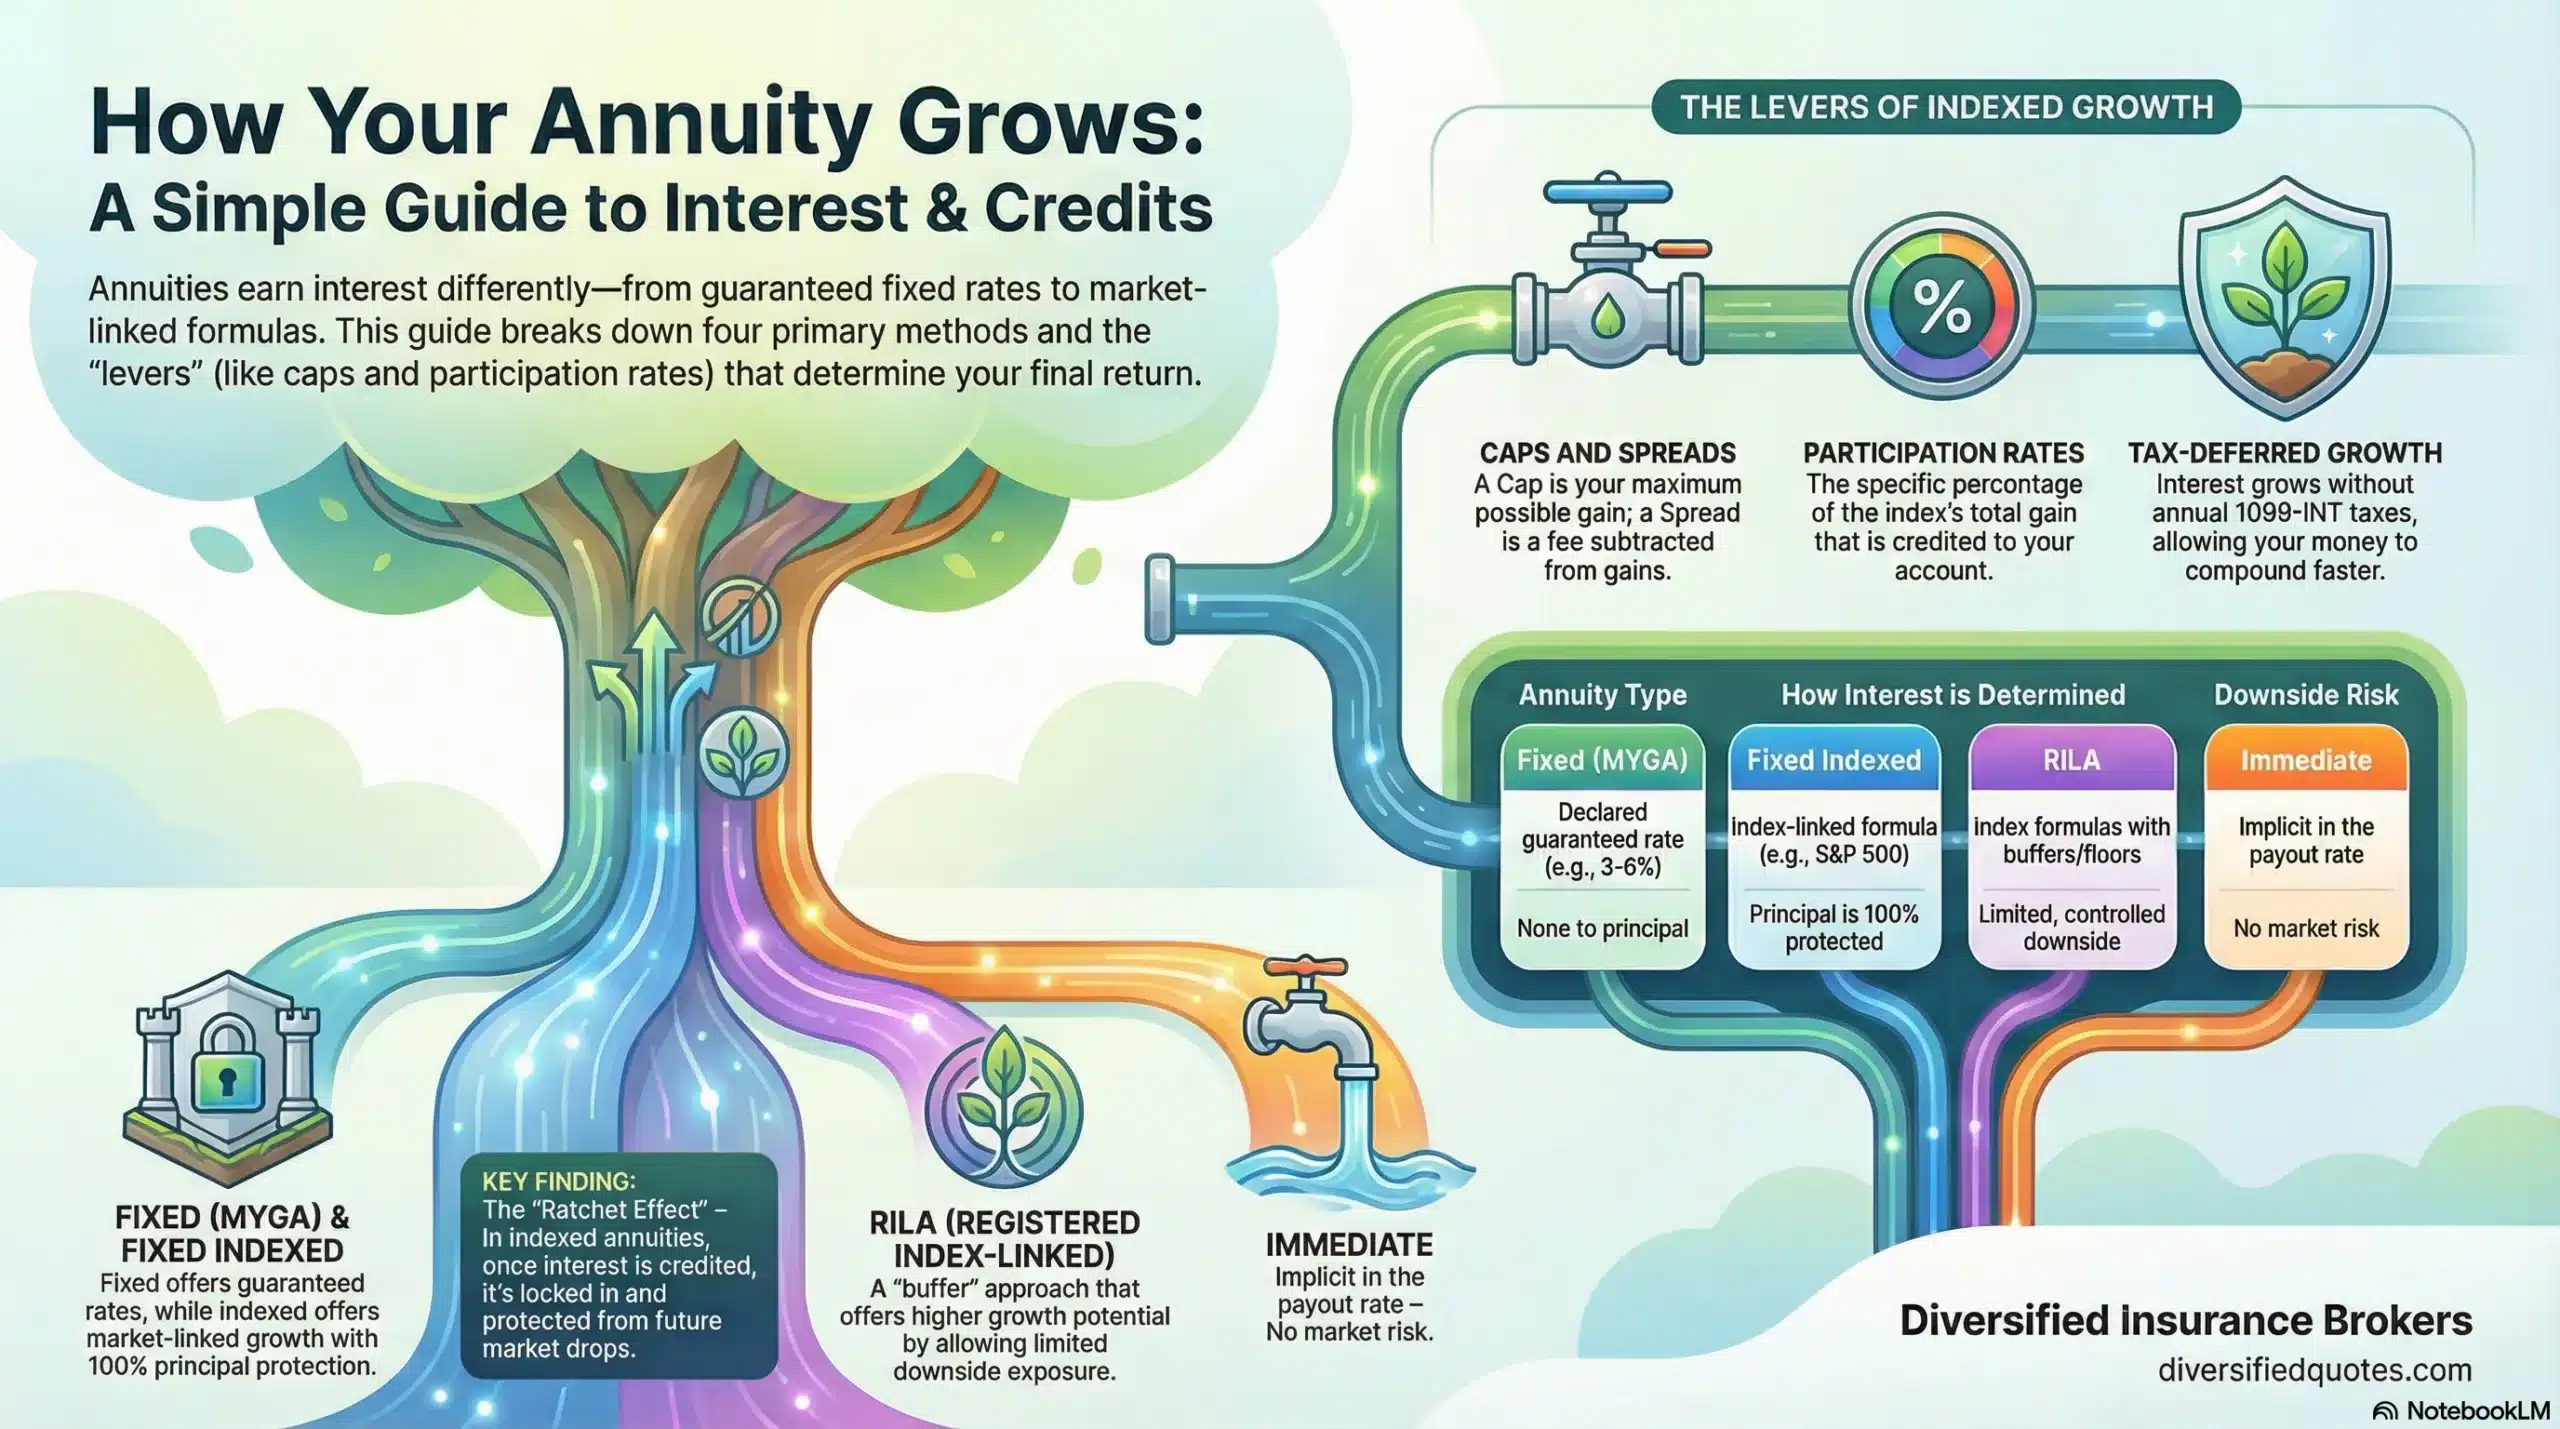
SpireMark offers ten allocation options: a one-year fixed account and nine index-linked strategies. The index strategies use point-to-point crediting, which compares an index value at the start of a term with its value at the end. Some apply a cap, which limits the maximum credit, and others apply a participation rate, which credits a share of the index gain.
The one-year strategies include a capped S&P 500 option, capped and participation rate options on the S&P 500 IQ Index, a participation rate option on the Bloomberg Bitcoin US 100 10% Index, a capped option on the Nasdaq-100 HiCap Index, and a participation rate option on the Solactive Nasdaq-100 DART 10% Index. Two-year participation rate options are available on the S&P 500 IQ Index, the bitcoin-linked index, and the DART index. Two-year terms typically carry higher participation rates, because the gain is measured over a longer period and credited only at the end.
Caps and participation rates can change over the years. The company sets them at the start of each term, subject to contractual minimums, so the rates you see at purchase may change. Our guide to index annuity crediting methods explains how caps, participation rates, and terms interact. Because SpireMark’s roll-up depends on credited interest, these renewal rates matter even more than they would in a growth-only annuity.
The Indexes Behind the Strategies
SpireMark’s index menu mixes familiar benchmarks with newer designs. The S&P 500 tracks large U.S. companies and is the most widely followed measure of the U.S. stock market. The S&P 500 IQ Index (formally named S&P 500 IQ 0.5% Decrement Index) blends the S&P 500 with a cash component and uses a 15 percent volatility control overlay. A decrement is a fixed deduction built into the index calculation, here 0.5 percent a year, which lowers the index’s return compared with an index without one.
The Nasdaq-100 HiCap Index, according to Nasdaq’s published methodology, tracks Nasdaq-100 futures and uses a volatility-tracking mechanism that adjusts its exposure daily, from zero up to twice the underlying exposure. The Solactive Nasdaq-100 DART 10% Index is described by the company as a diverse mix of U.S. large-cap equities, U.S. Treasuries, and gold. The Bloomberg Bitcoin US 100 10% Index is described as combining traditional equity growth with bitcoin exposure.
Volatility-controlled indexes are common in fixed indexed annuities because they allow insurers to offer higher participation rates or caps. Our article on why volatility targeting is popular explains the trade-off. These indexes tend to smooth results, but they can also lag in strong markets, and features like decrements reduce returns. A higher participation rate on a controlled index is not automatically better than a lower cap on the plain S&P 500.
Allocation Blueprints
For buyers who would rather not pick strategies one at a time, SpireMark offers three preset bundles called Allocation Blueprints: Foundation, described as conservative; Keystone, described as moderate; and Pinnacle, described as aggressive. Each blueprint spreads the premium across several strategies in fixed proportions set by the company.
The blueprints differ mainly in how much they place in the fixed account and in the bitcoin-linked strategy. In the materials we reviewed, Foundation included the largest fixed account share and no bitcoin-linked allocation, Keystone added a modest bitcoin-linked share alongside a smaller fixed account share, and Pinnacle eliminated the fixed account and carried the largest bitcoin-linked share. All three included the S&P 500, S&P 500 IQ, Nasdaq-100 HiCap, and DART strategies.
The key selling point of the blueprints is pricing. The launch announcement says the bundled blueprints may provide higher rates and caps than the same strategies selected individually, and the rate sheet we reviewed showed exactly that pattern. In exchange, you give up control over the exact mix. If you choose a blueprint, ask how its renewal rates will be set compared with individual strategies, whether you can switch between blueprints and individual allocations at each anniversary, and how the blueprint’s results would feed into the roll-up.
Liquidity and Required Distributions
In the first contract year, up to 10 percent can come out without a surrender charge. From the second year on, the allowance can stack to as much as 20 percent, but only when the previous contract year had no withdrawals. Alternatively, you can withdraw the required minimum distribution associated with the contract without a surrender charge. Taking more than the allowance during the surrender period can trigger both a surrender charge and an MVA.
If you hold SpireMark in an IRA, the required minimum distribution allowance prevents a conflict between tax rules and contract rules. Our guide to required minimum distributions covers when they begin and how they are calculated. Once lifetime income is active, the rider withdrawals generally count toward the distribution, though you should confirm how the contract coordinates the two.
Keep in mind that withdrawals before income activation reduce both the account value and, typically, the benefit base, which lowers future income. After income starts, withdrawals above the guaranteed amount can reduce future income as well. If you expect to need occasional lump sums, plan for them in advance rather than treating SpireMark as an emergency fund. Keeping a separate, liquid reserve lets the annuity do what it was built for, which is providing lifetime income.
Surrender Charges and the Market Value Adjustment
SpireMark has a ten-year surrender schedule. According to the product materials, the charges by contract year are 10, 9.40, 8.40, 7.35, 6.35, 5.30, 4.25, 3.20, 2.15, and 1.05 percent, falling to zero from year eleven onward. The schedule may differ by state. Surrender charges apply only to amounts withdrawn above the penalty-free allowance or to a full surrender.
The market value adjustment adds another layer, and you can read a fuller walkthrough of what a market value adjustment is. In short, it changes the value of an excess withdrawal or surrender based on interest rate movements since the start of the current MVA period. It can work for you if rates fall or against you if rates rise. On SpireMark, the first MVA period runs ten years from the contract date. Each tenth anniversary then opens a fresh ten-year period, and only the 30 days leading up to each new period are exempt from the adjustment.
That renewing MVA is a detail many buyers miss. It means that even after surrender charges end, a large withdrawal or surrender outside the 30-day window can still be adjusted. If you might want to move money after the tenth year, mark the window dates on your calendar and plan around them.
Surrender Charge Waivers
Three surrender charge waivers come with SpireMark, covering nursing home stays, terminal illness, and care received at home. Each lets you access money without a surrender charge if you meet the rider’s conditions, which typically include a waiting period after issue and specific definitions of confinement or diagnosis. The details are in the waiver riders, which vary by state.
These waivers are separate from the care benefits tied to the income rider. The waivers address access to your account value, while the activities of daily living benefits address income and payouts. Our guide to an annuity with a nursing home rider explains how these provisions usually work and what documentation insurers require.
Together, the waivers and care benefits make SpireMark more flexible in a health crisis than a basic fixed indexed annuity. They do not, however, remove every cost. Depending on the contract terms, the market value adjustment may still apply, and withdrawals still reduce the benefit base and future income. Ask how a waiver withdrawal would affect your rider values, and whether using a waiver would change your eligibility for the enhanced income benefit or the enhanced death benefit. Clear answers in writing are worth requesting before you buy, rather than in the middle of a family emergency.
Want to compare SpireMark with other income annuities?
Compare Income Annuities
SpireMark Versus PillarMark
SpireMark and PillarMark are close relatives. Both are ten-year fixed indexed annuities from TruSpire with the same issue ages, premium rules, crediting strategies, allocation blueprints, surrender schedule, market value adjustment, waivers, care benefits, and enhanced death benefit. The main differences sit in the income rider, although SpireMark launched with caps a little below PillarMark’s on several strategies, with the same participation rates. Because the roll-up feeds on credited interest, that gap can matter, and renewal rates may differ again later.
SpireMark’s MultiRider Max carries a 1.25 percent annual charge on the benefit base, offers a 45 percent benefit base bonus, rolls up at 250 percent of credited interest before income, and allows income as soon as 30 days after issue. The PillarMark fixed indexed annuity pairs with the MultiRider, which has no added charge, offers a 50 percent bonus, rolls up at 200 percent before income, and allows income only after ten years or at age 85, whichever comes first. Both roll up at 100 percent after income starts.
The choice comes down to time and flexibility. If you need income within the next decade, or you want the freedom to start whenever you choose, SpireMark is the only one of the two that allows it, unless you will reach age 85 sooner and become eligible under PillarMark’s age trigger. If you are confident you can wait, PillarMark avoids the rider charge, and that saving compounds over the years. An illustration of both products at your expected start date will show which design produces more income and more value for heirs in your case.
How SpireMark Compares With Other Income Annuities
SpireMark competes in a crowded field of fixed indexed annuities built for lifetime income. Most of those products share the same basic architecture, a benefit base, a roll-up, a payout percentage, and a rider charge, but they combine those pieces in very different ways. Some use fixed roll-ups that grow the benefit base regardless of index results, others use performance-based roll-ups like SpireMark’s, and some skip the roll-up entirely in favor of higher payout percentages.
The Axonic Trailhead income annuity is one example of another newer carrier’s approach to income, and comparing designs like these side by side shows how much the structure of a rider matters. Two products can advertise similar-looking bonuses and roll-ups yet produce noticeably different income for the same person.
What makes SpireMark distinctive is its combination of very early income access, a performance-driven roll-up that continues after income starts, built-in care benefits, an enhanced death benefit, and a bitcoin-linked index option. What weighs against it is the B++ AM Best rating of its issuer and the short track record of the new Malibu Life business. Income annuities from carriers rated A or higher may offer lower roll-up figures but stronger financial backing. The right comparison weighs projected income, guaranteed income, rider costs, and the strength of the company making the promise.
Who SpireMark Fits
SpireMark may fit someone between 50 and 85 who wants an indexed annuity to deliver guaranteed lifetime income and expects to start that income within the next several years, or who wants the option to start it at any time. Retirees bridging the gap before Social Security, or people who want guaranteed income to cover essential expenses soon after retiring, are natural candidates.
It may also fit buyers who value the chance for income to rise over time and who are comfortable with that growth depending on index performance rather than a fixed roll-up. People concerned about future care costs may appreciate the activities of daily living benefits, and those who want something left for heirs may value the enhanced death benefit, provided they understand its five-year payout and the requirement that account value remain.
Finally, SpireMark may also suit someone at ease with a young carrier who will keep their allocation to a size they are at ease with, and who plans to hold the contract through its ten-year surrender period. A buyer who wants some exposure to bitcoin-linked returns without risking principal to index losses may also find the crediting menu appealing, as long as they understand that the participation rate limits how much of any gain is credited.
Who Should Pass on SpireMark
SpireMark is not a fit for everyone. If you are confident you will not need income from this money for at least ten years, PillarMark offers similar features without the rider charge, and a growth-focused annuity without any income rider may be worth considering too. Paying 1.25 percent of the benefit base every year for a feature you will not use for a decade is hard to justify.
Buyers who require an A- or better AM Best rating should look elsewhere, because TruSpire’s B++ does not meet that standard. People who live in states where SpireMark is not approved, including the states where TruSpire is not licensed, cannot buy it. Anyone under 50 cannot buy it.
SpireMark also does not suit anyone who may need large sums from the contract within ten years, given the surrender charges and the renewing market value adjustment. And buyers who prefer simple, predictable growth with no moving parts may be happier with a multi-year guaranteed annuity or a basic fixed annuity. SpireMark rewards people who understand its benefit base, roll-up, care benefits, and death benefit rules, and who will use those features. For anyone who would not, the complexity and cost outweigh the advantages.
How Our Office Helps
We start by mapping your retirement income needs: what Social Security, pensions, and other savings will cover, when you want to start drawing from this money, and what you want to leave behind. That tells us whether an income rider makes sense and, if so, whether an early-income design like SpireMark or a deferred design like PillarMark fits better.
If SpireMark is a candidate, we run illustrations at several income start dates and set them beside competing income products, some from insurers with stronger ratings. We look at guaranteed income, projected income, rider charges, care benefits, and death benefits side by side, and we walk through TruSpire’s ratings from both AM Best and KBRA so you can decide how much to place with it.
When you decide, we handle the application, coordinate transfers or exchanges, and make sure the contract you receive is the version approved for your state. Once SpireMark is issued, we can sit down with you each year to look at renewal rates, how the benefit base has grown, and whether your income start date still makes sense. Our recommendations follow your goals and the numbers, and SpireMark is only one of many options we can compare for you.
Ready to see whether SpireMark fits your income plan?
Start My SpireMark Review
Financial Protection Essentials
Guides for building retirement income that lasts.
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
How soon can SpireMark start paying lifetime income?
The rider permits income to begin once the contract has been in force for 30 days. You can also wait, and each year of waiting gives the benefit base more chances to roll up, while the rider charge continues to apply. An illustration comparing several start dates shows which timing produces the most value for you.
Can I lose money in SpireMark?
Index declines cannot reduce your account value, and credited interest is locked in. The account can still shrink from the rider charge, withdrawals, surrender charges, and the market value adjustment, and the guarantees depend on TruSpire’s ability to pay. Our article asking whether an indexed annuity is safe explains these risks.
Is the 45 percent bonus real money I can withdraw?
No. The bonus is added to the benefit base, which is used to calculate income, care benefits, and the enhanced death benefit. It does not increase your account value or what you would receive on surrender. Our look at bonus annuity pros and cons explains how different bonus types work.
Can I move my IRA or 401(k) into SpireMark?
Yes. SpireMark accepts qualified money, and a direct transfer or direct rollover keeps the money tax deferred. Employer plan rules determine when a 401(k) can be moved. Our guide on how to transfer a retirement account into an annuity walks through the steps.
How is SpireMark taxed inside an IRA?
Inside an IRA, SpireMark follows the IRA’s tax rules. Withdrawals, including rider income, are generally taxed as ordinary income, and required minimum distributions apply. Our page on how qualified annuities are taxed covers the details.
Can SpireMark pay income for both spouses?
Many income riders offer a joint option that continues payments for the surviving spouse, usually at a lower payout percentage. The materials we reviewed do not detail SpireMark’s joint terms, so ask for a joint illustration. See how a joint income annuity for spouses typically works.
Does SpireMark work for someone retiring early?
It can, because income can start soon after issue and the minimum issue age is 50. The IRS can add a 10 percent penalty to taxable withdrawals taken under age 59 and a half unless an exception applies, so timing matters. Our guide to annuity strategies for early retirees covers the planning issues.
Are SpireMark death benefits taxable to my beneficiaries?
Generally, yes, on the portion that represents earnings or untaxed qualified money. Beneficiaries pay ordinary income tax on that portion, whether they take the standard benefit or the enhanced benefit paid over five years. For more, see whether annuity death benefits are taxable in different situations.
What does TruSpire’s B++ rating mean for SpireMark buyers?
B++ is a good rating, fifth of AM Best’s thirteen levels, but it sits below the A range many buyers prefer. KBRA separately rates TruSpire A-. Our guide to AM Best rating meanings explains the full scale and how to use it.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to Best Fixed Indexed Annuity Products — covering individual fixed indexed annuity product reviews from top-rated carriers from 100+ carriers.
Last Reviewed: October 22, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
