
Axonic Trailhead FIA Income Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Axonic Trailhead FIA Income Annuity
Trailhead FIA Income, issued by Axonic Insurance Company, is built around an income base that starts at 125 percent of your premium on the day the contract is issued, grows by 10 percent of your original premium for every year you wait to start income, up to 15 years, and receives a second 25 percent bonus once you have waited ten years. Wait the full 15 years and the income base reaches 300 percent of what you paid in. That income base is not cash you can withdraw, but it is the number your guaranteed lifetime withdrawals are calculated from, which makes the timing of your first withdrawal the most important decision you will make with this contract. Everything else on this page sits on top of that.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and income-focused fixed indexed annuities like Trailhead FIA Income are contracts our office places regularly, particularly when a client’s priority is a retirement paycheck that cannot be outlived. Working as an independent annuity broker, we line up the dollar income this contract produces for your age and start date against other carriers’ income riders, so you are choosing on actual dollars instead of headline bonuses.
Want to see how much lifetime income Trailhead FIA Income could pay you?
Get My Trailhead Income Quote
Trailhead FIA Income at a Glance
| Feature | Details |
|---|---|
| Issuer | AmFirst Insurance Company, Oklahoma City, Oklahoma; designed and serviced by Axonic Insurance; AM Best A- (Excellent) |
| Product Type | Fixed indexed annuity, single premium deferred, with a market value adjustment and a guaranteed lifetime withdrawal benefit rider |
| Issue Ages | 55 to 80 |
| Premium | $20,000 minimum; $1,000,000 maximum without company approval |
| Surrender Period | 10 years: 9%, 9%, 8%, 7%, 6%, 5%, 4%, 3%, 2%, 1% |
| Market Value Adjustment | Applies to excess withdrawals and surrenders during the surrender period; see what a market value adjustment is |
| Annual Withdrawal Allowance | 10% of prior-anniversary contract value (10% of premium in year one); see annuity withdrawal allowance rules |
| Income Base Roll-Up | 10% simple interest on premium each year until income starts, for up to 15 years |
| Income Base Bonuses | 25% upfront bonus at issue, plus a 25% deferral bonus after ten years of waiting |
| Annual Rider Fee | 0.95% |
| Crediting Options | Fixed rate, participation rate, and cap rate strategies on several indexes |
| Waivers | Nursing home confinement and terminal illness, for owners under 80 at issue |
| Availability | Not available in California, Connecticut, Minnesota, New Jersey, New York, North Carolina, Rhode Island, or Wisconsin |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Issues Trailhead FIA Income
Trailhead FIA Income is designed and serviced by Axonic Insurance, but the contract itself is issued by AmFirst Insurance Company, an Oklahoma-domiciled life insurer with its home office in Oklahoma City. That distinction matters, because the guarantees in any annuity, including the lifetime withdrawals promised by the income rider, rest on the financial strength and claims-paying ability of the issuing insurer. When you evaluate Trailhead FIA Income, the company whose balance sheet you are relying on is AmFirst.
AmFirst currently holds a Financial Strength Rating of A- (Excellent) from AM Best, which falls within AM Best’s second-highest rating category and is the fourth-highest of its thirteen possible ratings. AmFirst has held that A- rating for a number of years, after earlier upgrades from lower ratings. Ratings can change, so it is worth confirming the current rating before you apply. Our guide to what an AM Best rating means explains how the scale works and what each grade signals.
Axonic’s role is to design the product, distribute it through licensed financial professionals, and handle the day-to-day servicing of contracts. According to its product disclosures, Axonic also has ownership interests in segregated reinsurance accounts that provide reinsurance coverage to AmFirst and to other insurers. For a closer look at the company behind the product line, including its other annuities, see our review asking is Axonic a good company. As with any carrier, the right question is not only whether the company is sound but whether its contract fits your income goals better than the alternatives.
How the Income Base Is Built
Every income rider works from two separate numbers, and understanding the difference is the key to understanding Trailhead FIA Income. The first is the contract value, which is your actual money: premium plus interest credits, minus withdrawals and charges. The second is the income base, a separate accounting value used only to calculate how much you can withdraw each year for life under the guaranteed lifetime withdrawal benefit rider. Our explainer on how a GLWB works covers the mechanics that are common to riders like this one.
On Trailhead FIA Income, the income base starts with your premium and grows from three sources. A 25 percent upfront bonus is added on the issue date. A roll-up credit equal to 10 percent of your original premium is added for each year you defer income, for up to 15 years. And if you wait at least ten years before activating income, a second 25 percent bonus is added. None of these increases depend on how the stock market or any index performs, which gives the income base a predictable path that you can plan around.
What the income base cannot do is leave the contract as a lump sum. It is not part of the contract value or the cash surrender value, and it is not paid to your beneficiaries as a death benefit. Its only job is to set the size of your guaranteed lifetime withdrawals. Our article on the income annuity benefit base explains why this value is sometimes called a benefit base or income account value and why it should never be confused with money you can spend.
The 10 Percent Simple Roll-Up
The roll-up is the engine of the income base. For each year you defer lifetime withdrawals, Trailhead FIA Income adds 10 percent of your original premium to the income base, for up to 15 years or until you activate income, whichever comes first. On a $100,000 premium, that is a $10,000 credit each year, regardless of index performance. Our guide to the income annuity roll-up rate explains how roll-ups differ from the interest credited to your contract value.
The word simple matters. A simple roll-up is calculated on the original premium every year, so the dollar amount of each credit stays the same. A compound roll-up is calculated on the growing income base, so each year’s credit is larger than the last. Over long deferral periods, a compound roll-up at the same rate would grow faster, which is why a 10 percent simple rate and a 10 percent compound rate are not the same promise.
The roll-up stops at 15 years. After that, the income base no longer grows from roll-up credits, although the lifetime withdrawal percentage applied to it generally continues to rise with additional years of deferral, up to the ceiling on Axonic’s chart. Because the credits stop when you start income, every year of waiting during the first 15 years increases the income base by a fixed amount, which is why the timing of activation has such a large effect on the income you receive.
A roll-up rate also says nothing on its own about how much income you will receive. Two riders with the same roll-up can pay very different amounts because their withdrawal percentages differ, and a rider with a lower roll-up can pay more than one with a higher roll-up. The only reliable comparison is the guaranteed dollar income at your age and start date.
Two Income Base Bonuses
Trailhead FIA Income adds two bonuses to the income base, and both are worth understanding before you compare it with other income annuities. The first is a 25 percent upfront income base bonus, credited on the issue date. On a $100,000 premium, the income base starts at $125,000 before any roll-up credits are added. Because it is credited at issue, the upfront bonus is part of the income base even if you activate income in the first year.
The second is a 25 percent deferral bonus that applies if you wait at least ten years before taking lifetime withdrawals. On the same $100,000 premium, that adds another $25,000 to the income base. The deferral bonus rewards patience, and it creates a meaningful jump for anyone who was planning to start income somewhere near the ten-year mark.
Both bonuses apply to the income base, not the contract value, so neither one increases the money you can withdraw as a lump sum or the amount your beneficiaries receive. That is the standard trade-off with income base bonuses. Our article on the annuity income bonus explains how these bonuses differ from premium bonuses, which are credited to the contract value and are usually subject to a vesting schedule.
How the Income Base Grows on $100,000
The table below shows how the income base builds on a hypothetical $100,000 premium, using the roll-up and bonuses described above and assuming no withdrawals before income starts. The income base figures follow directly from the contract’s stated formula and do not depend on index performance. Your actual results would depend on your premium, the rider terms in your contract, and whether any withdrawals were taken. Because the roll-up is simple, each row adds the same $10,000 per year of waiting until the 15-year limit is reached.
| Years Before Income Starts | Upfront Bonus | Roll-Up Credits | Deferral Bonus | Income Base |
|---|---|---|---|---|
| 0 | $25,000 | $0 | $0 | $125,000 |
| 5 | $25,000 | $50,000 | $0 | $175,000 |
| 10 | $25,000 | $100,000 | $25,000 | $250,000 |
| 15 | $25,000 | $150,000 | $25,000 | $300,000 |
| 20 | $25,000 | $150,000 | $25,000 | $300,000 |
Notice what happens between year nine and year ten. A ninth year of waiting adds only the $10,000 roll-up credit, but the tenth year adds both the roll-up credit and the $25,000 deferral bonus, so the income base jumps by $35,000 in a single year. Anyone planning to start income around the nine-year mark should look closely at whether waiting one more year makes sense. After year 15 the income base stops growing, but as the next section shows, the withdrawal percentage generally keeps rising with further deferral until it reaches the chart’s maximum.
Lifetime Withdrawal Percentages: A Handful of Examples
When you activate income, Axonic multiplies your income base by a lifetime withdrawal percentage to set your guaranteed annual maximum withdrawal. That percentage depends on two things: your age when the contract was issued, or the younger spouse’s issue age for joint coverage, and the number of years you deferred. Axonic publishes a full chart covering issue ages 55 to 80, with longer deferral periods available at younger issue ages, and the highest percentages on the current chart are 10.84 percent for single life and 10.34 percent for joint life. Rather than reproduce it, the table below shows a few representative examples. Our guide to the income annuity payout rate explains how these percentages compare across products.
| Issue Age | Years Deferred | Single Life | Joint Life | Income Base on $100,000 | Single-Life Annual Income |
|---|---|---|---|---|---|
| 60 | 0 | 6.05% | 5.55% | $125,000 | $7,563 |
| 65 | 0 | 6.40% | 5.90% | $125,000 | $8,000 |
| 70 | 5 | 7.50% | 7.00% | $175,000 | $13,125 |
| 55 | 10 | 7.00% | 6.50% | $250,000 | $17,500 |
| 65 | 10 | 8.00% | 7.50% | $250,000 | $20,000 |
| 60 | 15 | 7.66% | 7.16% | $300,000 | $22,980 |
These percentages come from the chart Axonic currently publishes for new contracts, and the carrier can change them at any time, so treat them as examples rather than a quote. Income figures are hypothetical, assume no withdrawals before activation, and are rounded to the nearest dollar. Once a contract is issued, the rider terms in that contract govern your withdrawals, which is why it pays to confirm the chart in effect before you apply.
Want your exact Trailhead income at your age and start date?
Request My Income Illustration
From Percentage to Paycheck
A withdrawal percentage only becomes meaningful when it is applied to the income base. Take a 60-year-old who buys Trailhead FIA Income with $100,000 and starts income right away. The income base is $125,000 after the upfront bonus, and the single-life percentage at issue age 60 with no deferral is 6.05 percent, which produces about $7,563 a year for life. That is a reasonable result for someone who needs income immediately, but it is not where this contract is strongest.
Now take the same 60-year-old and have them wait 15 years, starting income at 75. The income base grows to $300,000, the percentage rises to 7.66 percent, and the guaranteed annual income becomes $22,980, or about $1,915 a month. This is the hypothetical example Axonic uses in its own consumer brochure, and it shows how dramatically deferral changes the outcome. The income is roughly three times the immediate-start amount because both the income base and the percentage have grown.
A middle path also stands out. A 65-year-old who waits ten years, collecting the deferral bonus, has a $250,000 income base and an 8.00 percent single-life percentage, for $20,000 a year. Each of these is a hypothetical illustration built from the current chart. Your own figures depend on your premium, your age at issue, whether you choose single or joint coverage, and the chart in effect when you apply, which is why the right next step is an illustration built on your numbers.
Single Life or Joint Life
Trailhead FIA Income lets you base lifetime withdrawals on one covered person or on two spouses. With single-life coverage, guaranteed withdrawals continue for as long as the covered person lives. With joint coverage, they continue as long as either spouse is living, which protects a surviving spouse from losing the income when the first spouse dies. Our guide to a joint income annuity for spouses covers the planning considerations for couples.
The cost of that extra protection is a lower withdrawal percentage. On the chart Axonic currently publishes, every joint-life percentage is exactly half a percentage point below the matching single-life percentage, across every issue age and deferral period. For a 65-year-old couple who waits ten years, that means 7.50 percent instead of 8.00 percent. On a $250,000 income base, joint coverage would pay $18,750 a year instead of $20,000, a difference of $1,250 a year in exchange for income that continues for the second spouse’s lifetime.
For joint coverage, the percentage is based on the issue age of the younger spouse. When spouses are several years apart, that can lower the percentage more than the half-point difference alone suggests, because the younger spouse’s age sets the starting point on the chart. Couples weighing single against joint coverage should compare both options at their actual ages, and should consider how a survivor would replace the income if single-life coverage were chosen and the covered spouse died first.
Why Issue Age Matters as Much as Start Date
One of the most important details on the Trailhead chart is easy to miss: the percentage is based on your age when the contract is issued, not your age when income starts. Combined with the deferral credits, that structure strongly rewards buying earlier and waiting rather than buying at the moment you need income.
Consider two people who both want income to begin at 75. The first buys at 65 and waits ten years, reaching a $250,000 income base on a $100,000 premium and an 8.00 percent single-life percentage, for $20,000 a year. The second waits until 75 to buy and starts income immediately, which gives a $125,000 income base and a 7.55 percent percentage, for about $9,438 a year. The first buyer receives more than twice as much income from the same premium, because the money spent ten years earning roll-up credits and the deferral bonus.
That comparison is not entirely apples to apples, because the first buyer committed the money ten years earlier and gave up access to it beyond the annual withdrawal allowance during that time. But it illustrates why Trailhead FIA Income is fundamentally a planning tool for people in their late fifties and sixties who can identify a future income start date. For people who need income now, an immediate annuity or a different income rider may produce more income from day one, and our office compares those options side by side.
Contract Value Versus Income Base
Once lifetime withdrawals begin, it helps to picture the contract value and income base moving on separate tracks. Your guaranteed annual withdrawal is calculated from the income base, but the money is actually paid out of your contract value as long as any contract value remains. Every withdrawal, along with the annual rider fee, reduces the contract value, while index credits on the remaining balance can add to it.
That arrangement has two practical consequences. The first is that you keep access to whatever contract value remains. Trailhead FIA Income is not an irrevocable annuitization; you remain the owner of the contract, and the remaining contract value is still yours to withdraw, subject to the contract’s terms, or to pass to beneficiaries. The second is that index performance still matters after income starts, because stronger credits help the contract value last longer, which in turn affects how much is left for liquidity and for your heirs.
What index performance does not affect is the guaranteed income itself. Your annual maximum withdrawal is set by the income base and the withdrawal percentage, so a poor year for the index does not reduce your income. That is the essential promise of a guaranteed lifetime withdrawal benefit: market-linked growth potential on your actual money, paired with an income floor that does not move with the market.
It also explains why two contracts with similar guaranteed income can look very different on a statement years later. A contract with higher income guarantees but weaker crediting may show a smaller contract value over time, while one with more modest guarantees but stronger crediting may preserve more. Reviewing both values in an illustration, rather than just the income, gives the full picture.
When the Contract Value Reaches Zero
The central guarantee of the rider is what happens if you live long enough to exhaust the contract value. If withdrawals within the rider’s limits, along with fees, eventually reduce the contract value to zero, your guaranteed lifetime withdrawals continue for the rest of your life, or the joint lifetime of you and your spouse with joint coverage. At that point the insurer is paying income from its own resources rather than from your money.
This is the longevity protection that people buy an income rider for. A retiree who draws the same amount from an ordinary investment account faces the risk of running out, particularly if poor returns arrive early in retirement. With Trailhead FIA Income, as long as you stay within the guaranteed annual maximum each year, the payments continue regardless of how long you live or how the indexes perform.
There is one important exception. The guarantee continues when the contract value reaches zero for reasons other than an excess withdrawal. If you take more than your guaranteed annual maximum in a year, and that excess withdrawal is what depletes the contract value, the lifetime guarantee can be lost. Staying within the annual limit is therefore the single most important rule for protecting the income stream, and it is worth reviewing with our office before income begins.
Taking More Than Your Guaranteed Amount
Life does not always follow a plan, and sometimes a retiree needs more than the scheduled income in a given year. Trailhead FIA Income allows access to the contract value, but withdrawals above the rider’s permitted amount are treated differently from scheduled lifetime withdrawals. According to Axonic’s disclosures, withdrawals in excess of the rider’s permitted amount may reduce future guaranteed benefits, and the exact reduction is defined in the rider.
During the ten-year surrender period, an excess withdrawal may also trigger surrender charges and a market value adjustment on the amount above the annual withdrawal allowance. Withdrawals taken under the guaranteed lifetime withdrawal benefit are exempt from the market value adjustment and from the $500 minimum withdrawal amount, but money taken outside those limits is not.
The practical lesson is to keep separate emergency funds outside the annuity. Pairing an income annuity with a cash reserve or other liquid savings means unexpected expenses never have to force an excess withdrawal. If a large withdrawal does become necessary, contacting our office first lets us estimate the effect on your guaranteed income and on any surrender charges before the money moves, so the trade-off is clear before the decision is made.
What the Rider Fee Costs
The guaranteed lifetime withdrawal benefit rider carries an annual fee of 0.95 percent. That fee is how the insurer pays for the guarantee, and it reduces the contract value each year. Over a long deferral period, the cumulative effect is meaningful, so it belongs in any comparison. Our guide on what an annuity income rider costs shows how fees in this range compare across the market.
One detail worth confirming is the value the fee is calculated on. Some income riders charge their fee as a percentage of the contract value, while others charge it on the income base. Because the Trailhead income base can grow to three times your premium, the difference could be substantial if the fee were based on the income base. The product summaries we reviewed state the fee rate but not its basis, so ask our office to confirm that detail from the contract and to show how the fee affects your contract value over the years you plan to hold it.
The fee should be judged against what it buys. For someone whose priority is guaranteed income that cannot be outlived, a 0.95 percent annual charge may be a reasonable price for income that would otherwise require a much larger amount of savings to produce safely. For someone who mainly wants growth and does not plan to use the income feature, paying for an income guarantee makes little sense, and an accumulation annuity without an income rider would usually be a better fit.
Index Crediting and Contract Value Growth
Trailhead FIA Income is a fixed indexed annuity, so the contract value earns interest through crediting strategies rather than direct market investment. Axonic offers three types: a fixed rate strategy that credits a declared rate, participation rate strategies that credit a percentage of an index’s gain, and cap rate strategies that credit index gains up to a maximum. In years when an index declines, your premium and previously credited interest are protected from the loss. Our overview of index annuity crediting methods explains how each approach works.
The index lineup on Axonic’s Trailhead FIA Income page currently includes the S&P 500, a Nasdaq-100 volatility control index, a Nasdaq-100 index tied to bitcoin trends, and several other rules-based indexes from major index providers. Index menus and the rates attached to them change over time, so the current rate sheet is the only reliable source for what is available when you apply.
On an income-focused contract, the role of index crediting is different from its role on a growth annuity. The roll-up and bonuses that build the income base are guaranteed and do not depend on any index. Index credits affect only the contract value, which in turn determines your liquidity, your death benefit, and how long the contract value lasts once withdrawals begin. Choosing strategies is still worth care, and our guide on how to choose the correct annuity indexes walks through the trade-offs between predictability and growth potential.
Surrender Charges and Liquidity
Trailhead FIA Income has a ten-year surrender period. The surrender charge starts at 9 percent in each of the first two contract years and steps down by one percentage point a year until it reaches 1 percent in year ten, after which it no longer applies. During the surrender period, withdrawals above the annual allowance and full surrenders are also subject to a market value adjustment, which can increase or decrease the amount you receive depending on how interest rates have moved since the contract was issued.
Each contract year, you can take multiple withdrawals totaling as much as 10 percent of the prior-anniversary contract value, or 10 percent of premium during the first year, without surrender charges or a market value adjustment. For contracts funded with an IRA, required minimum distributions are also exempt as long as they stay within that allowance. Each withdrawal must be at least $500 unless it is taken under the income rider, and if withdrawals reduce the contract value below $2,000, the contract may be surrendered automatically, subject to applicable charges, unless the withdrawals were taken under the rider.
Withdrawals taken before income starts also deserve thought because of their effect on the income rider. Taking money out during the deferral period reduces the contract value, and depending on the rider’s terms it can also affect the income base you are building. Anyone who expects to need regular access to this money during the next ten years should discuss that need with our office before applying.
Want to compare Trailhead FIA Income with other income annuities?
Compare Income Annuities
Changing the Covered Person
Retirement plans change, and an income annuity bought ten or fifteen years before income starts has to survive whatever happens in between. Trailhead FIA Income addresses this with some flexibility around the covered person, the individual whose lifetime the guaranteed withdrawals are based on. According to Axonic’s consumer materials, before lifetime income begins the contract may allow you to add, remove, or replace a covered person following certain life events, such as marriage, divorce, or death.
You may also have an opportunity to update your covered person selection when you activate lifetime income, subject to eligibility requirements. That matters for couples who are not sure, years in advance, whether single or joint coverage will make more sense when income begins. A couple’s health, the age gap between spouses, and other sources of survivor income can all look different at 75 than they did at 62.
The details of which events qualify and how a change affects the withdrawal percentage are set by the rider, so this is an area where reading the contract, or having our office walk through it with you, is essential. For buyers who expect their circumstances to change, it is a feature worth weighing alongside the headline income numbers.
Nursing Home and Terminal Illness Waivers
Trailhead FIA Income includes two waivers that give access to the contract value without surrender charges or a market value adjustment when serious health events occur. The nursing home confinement waiver applies if the owner has been confined to an eligible nursing home for at least 90 consecutive days, was not confined to a nursing home before the contract date, has owned the contract continuously since it was issued, and was younger than 80 on the contract date. A written request must generally be made within 90 days after the last day of confinement. Our article on the annuity nursing home care rider explains how these provisions fit into long-term care planning.
The terminal illness waiver applies if a physician certifies that a medical condition has reduced the owner’s life expectancy to 12 months or less. The owner can then take a full surrender or partial withdrawals of at least $500, with surrender charges waived and no market value adjustment, provided the owner has owned the contract continuously and was younger than 80 on the contract date.
Two points deserve emphasis. First, because both waivers require the owner to be under 80 at issue, a buyer who purchases at age 80 would not have them. Second, the waivers provide access to the contract value; they do not convert the income base into cash or increase your lifetime income. They are a safety valve for liquidity rather than a long-term care benefit, which is why buyers concerned about care costs should consider dedicated coverage as well.
The Death Benefit
If the owner dies before annuitization payments begin, Trailhead FIA Income pays the beneficiary the greatest of three values: the contract value, the minimum surrender value, and the net premium, meaning premium paid less any withdrawals. The market value adjustment does not apply at death. The minimum surrender value is a guaranteed floor calculated on 87.5 percent of premium, less net withdrawals, accumulated at the guaranteed rate stated in the contract.
The net premium component is a useful protection for a buyer who dies early. Even if fees and modest index credits had left the contract value slightly below the premium, beneficiaries would receive at least the premium paid, reduced only by withdrawals that had already been taken.
What the death benefit does not include is the income base. All the growth from roll-up credits and bonuses exists only to calculate lifetime withdrawals, and it disappears at death. As lifetime withdrawals continue over many years, the contract value, and with it the death benefit, typically declines. That is the normal trade-off of an income rider: it maximizes guaranteed lifetime income rather than the amount left to heirs. Buyers whose top priority is a legacy should compare Trailhead FIA Income with contracts built around enhanced death benefits, and should coordinate beneficiary designations with their overall estate plan.
Funding, Ownership, and Taxes
Trailhead FIA Income can be funded with non-qualified money, a traditional IRA, a Roth IRA, a SEP IRA, or 401(k) money, with a minimum premium of $20,000 and a maximum of $1,000,000 unless the company approves more. It can be owned individually, jointly by spouses, or by a trust. Joint ownership is limited to spouses, and the contract comes with a free-look period of up to 30 days, or longer where state law requires, during which you can cancel.
The funding source determines how withdrawals are taxed. For a non-qualified contract, interest grows tax-deferred, and withdrawals are generally taxed as ordinary income to the extent they represent gains, with gains generally treated as coming out first. For a traditional IRA, SEP IRA, or 401(k) rollover, every dollar withdrawn is generally taxed as ordinary income. A Roth IRA contract follows Roth rules, so qualified withdrawals are generally tax-free. Because issue ages begin at 55, it is also worth remembering that withdrawals before age 59 and a half may face a 10 percent IRS penalty in addition to income tax.
For IRA-funded contracts, required minimum distributions must still be satisfied. Axonic’s materials state that RMD withdrawals are not subject to surrender charges as long as they fall within the annual withdrawal allowance. How RMDs interact with lifetime withdrawals once income begins should be reviewed in advance, and a tax professional should be part of any decision involving qualified money.
Level Income and Inflation
Once lifetime withdrawals begin, the guaranteed amount is level. Axonic’s materials describe withdrawals continuing at that guaranteed level for life, and the product summaries we reviewed do not describe any built-in increase after income starts. A retiree who begins taking $20,000 a year will still be guaranteed $20,000 a year two decades later, even though the cost of living will almost certainly be higher.
That is a real limitation, and it should be planned for rather than ignored. One approach is to treat Trailhead income as a stable floor that covers essential expenses, alongside Social Security, which is adjusted for inflation, and other savings that remain invested for growth. Another is to stagger income sources, starting one annuity’s income now and another’s later, so that total income steps up over time.
The deferral structure of Trailhead FIA Income itself can help with that strategy. Because waiting generally increases both the income base and the withdrawal percentage, a contract purchased now and activated later can provide a larger income step later in retirement. For buyers who want inflation protection built directly into the payments, our guide to an inflation-protected income annuity covers products designed with increasing income, along with the trade-off of lower starting payments.
Trailhead FIA Income Versus Trailhead for Accumulation
Axonic offers more than one Trailhead fixed indexed annuity, and the names can cause confusion. Trailhead FIA Income is the version built around the guaranteed lifetime withdrawal benefit rider, with its roll-up, bonuses, and withdrawal percentages. Axonic’s accumulation-focused Trailhead contracts are covered in our review of the Axonic Trailhead accumulation annuity, and they are aimed at buyers whose priority is growing the contract value itself.
The choice between them depends on the job you need the money to do. When you want a guaranteed paycheck for life starting at a known future date, the income version is designed for exactly that, and the rider fee is the price of the guarantee. When growth with principal protection, flexibility to change plans, or leaving the full contract value to heirs matters more, an accumulation contract avoids paying for an income guarantee you may never use.
Some buyers split their money between the two approaches, dedicating part of their savings to guaranteed income and keeping the rest in contracts or accounts built for growth and liquidity. Our office can illustrate both options at your age and premium so you can see the dollar income from one and the projected growth from the other before deciding how much belongs in each.
Who Trailhead FIA Income Fits, and Who It Does Not
Trailhead FIA Income tends to fit buyers in their mid-fifties through early seventies who want guaranteed lifetime income and can name a future date for it to begin. The contract rewards waiting: the income base grows by a fixed amount each year for up to 15 years, receives a deferral bonus at ten years, and the withdrawal percentage generally rises with deferral. A 58-year-old planning to retire at 68, or a 62-year-old who wants a larger paycheck at 72, is the kind of buyer the design serves best.
It can also fit couples who want income that continues for the surviving spouse, retirees without a pension who want to build one, and savers who want to lock in a guaranteed income floor regardless of how markets perform during the years before retirement.
It suits several other groups less well. Buyers who need substantial access to their money during the next ten years face surrender charges and a market value adjustment. Buyers whose main goal is leaving money to heirs will find that the income base is not paid at death. Buyers who need income right away may find better immediate income elsewhere. Residents of California, Connecticut, Minnesota, New Jersey, New York, North Carolina, Rhode Island, and Wisconsin cannot buy the contract, and buyers who want payments that rise with inflation will need to plan around a level income.
Questions to Ask Before You Buy
The first question is when you want income to begin. Because the income base and withdrawal percentage both depend on deferral, knowing your target start date is essential to judging whether this contract fits. If the date is uncertain, it helps to look at the income at several start dates and see how much each additional year of waiting adds.
The second is whether you want single or joint coverage. That decision affects the percentage for the life of the contract, and for joint coverage the younger spouse’s issue age sets the starting point. The third is how the rider fee is calculated, whether on the contract value or the income base, and how it will affect the contract value over the years you plan to hold it.
The fourth is what liquidity you will need. The annual withdrawal allowance provides some access, but any withdrawal during the deferral period reduces the contract value and may affect the income base. Emergency savings held outside the annuity protect the income plan.
The last is how this contract compares with alternatives at your age and premium. Other income riders use different roll-ups, bonuses, and percentages, and the only fair comparison is the guaranteed dollar income each one produces at the same start date. Working through these questions before you apply helps make sure the contract you choose matches your retirement plan.
How Our Office Helps
Our work on a Trailhead case begins with your timeline. Jason and our office want to know when you want income to begin, whether a spouse needs to be covered, how much of your savings should stay liquid, and what other income you expect from Social Security, pensions, or investments. Those answers determine whether Trailhead FIA Income belongs on the short list and how it should be structured.
From there, we compare the guaranteed annual income from Trailhead FIA Income at your age, premium, and start date with other carriers’ income riders, using the dollar income rather than headline roll-up rates or bonus percentages. We also review the rider fee, the surrender schedule, the waivers, and how the death benefit would look over time, so you understand what you would gain and what you would give up.
Once you decide to move forward, our office handles the application, the choice between single and joint coverage, beneficiary designations, and any rollover or transfer paperwork. As an independent office, we let your income goals, not a single carrier’s product shelf, drive the recommendation, and we remain available to help you decide when to activate income once the time comes.
Ready to see your guaranteed lifetime income?
Talk to Our Office
Financial Protection Essentials
More resources for turning retirement savings into income you cannot outlive.
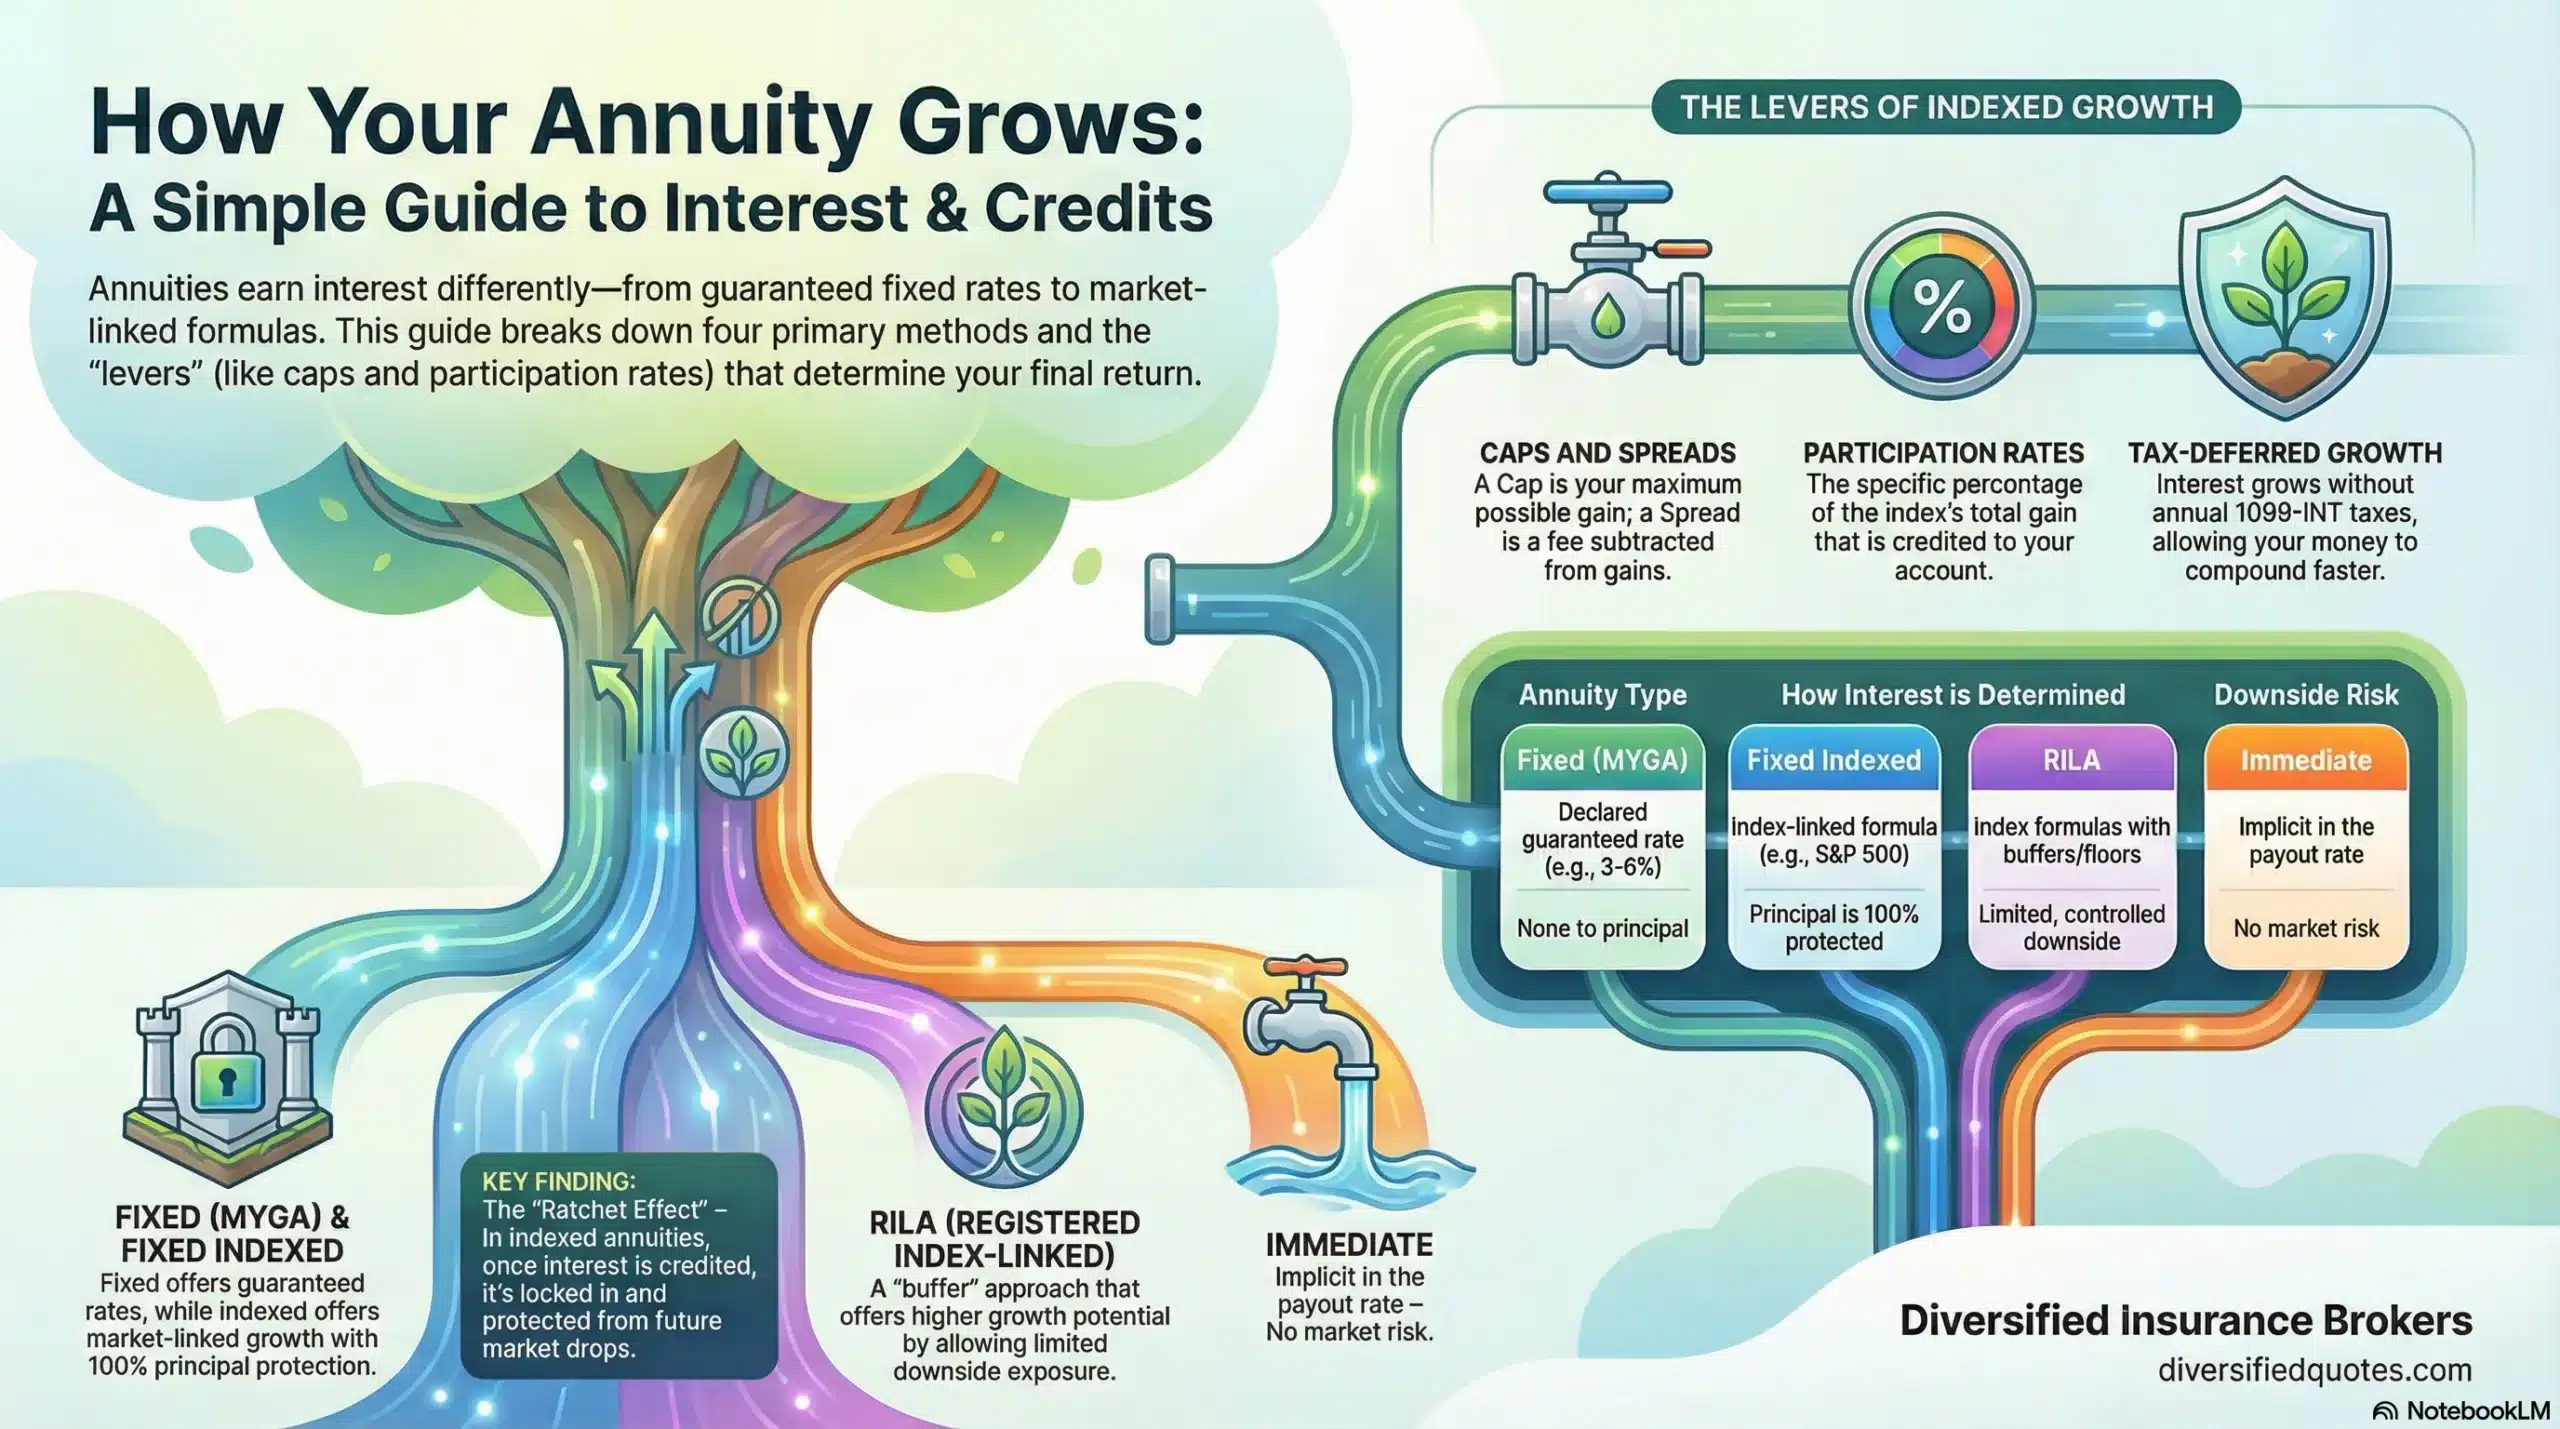
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Is the Trailhead income base paid to my beneficiaries when I die?
No. The income base is used only to calculate lifetime withdrawals and is not part of the death benefit. If you die before annuitization payments begin, your beneficiaries receive the greatest of the contract value, the minimum surrender value, or premium less withdrawals. Our article on what happens to annuities at death covers the options beneficiaries have.
How are Trailhead lifetime withdrawals taxed?
It depends on how the contract was funded. Withdrawals from a non-qualified contract are generally taxed as ordinary income to the extent of gains, traditional IRA contract withdrawals are generally taxed in full, and qualified Roth IRA withdrawals are generally tax-free. Our guide to how annuities are taxed in retirement explains each case.
Can I fund Trailhead FIA Income with money from my 401(k)?
Yes. Axonic lists 401(k) money among the accepted funding sources, along with traditional, Roth, and SEP IRAs. A direct transfer keeps the money tax-deferred and avoids withholding. Our guide to transferring a 401(k) to an annuity walks through each step.
Is an income rider better than annuitizing?
Each has advantages. Annuitization converts the contract into payments and generally gives up access to the balance, while the Trailhead rider pays lifetime withdrawals and lets you keep control of any remaining contract value. The right answer depends on how much you value flexibility versus payment size. Our comparison of annuitizing versus using an income rider explains the trade-offs.
Can I move an existing annuity into Trailhead FIA Income?
Often, yes. A non-qualified annuity can generally be moved through a tax-free exchange, and an IRA annuity through a direct transfer. Check remaining surrender charges and any benefits you would give up in the old contract before moving. Our guide to how 1035 exchanges work covers the rules.
What happens to my Trailhead income if the market falls?
Your guaranteed income does not change. The income base grows through guaranteed roll-up credits and bonuses, and your premium and credited interest are protected from index declines. A weak market can slow growth in the contract value, but it does not reduce the lifetime withdrawals. Our article on indexed annuities in market downturns explains the protection.
How does Trailhead income fit with Social Security?
Annuity income can cover essential expenses alongside Social Security. Because Trailhead rewards deferral, its income start date can be coordinated with your Social Security claiming age, so that total income steps up as each source begins. Our article on how Social Security and annuities work together covers common strategies.
What protection exists if the insurer cannot pay?
Every Trailhead guarantee rests on AmFirst Insurance Company’s ability to pay its claims, which is why the issuer’s financial strength rating matters. Each state also has a guaranty association that provides limited protection to annuity owners if an insurer fails, with coverage limits that vary by state. Our page on state guaranty association coverage explains how it works.
What if Trailhead FIA Income is not available in my state?
The contract is not offered in California, Connecticut, Minnesota, New Jersey, New York, North Carolina, Rhode Island, or Wisconsin. Residents of those states still have options, because other carriers offer fixed indexed annuities with lifetime income riders there. Our office can compare the guaranteed income from contracts available where you live.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to Best Fixed Indexed Annuity Products — covering individual fixed indexed annuity product reviews from top-rated carriers from 100+ carriers.
Last Reviewed: October 16, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
