Axonic Waypoint Multi Year Guarantee Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Axonic Waypoint Multi Year Guarantee Annuity
Waypoint MYGA, issued by Axonic Insurance, locks in a guaranteed fixed rate for the term you choose, two, three, five, seven, or ten years, and then gives you a 30-day window at the end of every term in which you can take your money out with no surrender charge and no market value adjustment. Between those windows, the rules are firm: there are no penalty-free withdrawals during the first contract year, and withdrawals above the annual allowance face surrender charges that start at 9 percent or more outside California. Choosing the right term, and knowing exactly when your window opens, is what makes this contract work.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and multi-year guaranteed annuities like Waypoint are contracts our office places regularly when savers want a predictable rate without market exposure. Acting as an independent annuity broker, we set Waypoint’s current rate for your chosen term beside competing MYGAs and CDs, so you can see whether its rate, liquidity rules, and issuer fit your money before you commit.
Want today’s Waypoint rate for the term you have in mind?
Get My Waypoint Rate
Waypoint MYGA at a Glance
| Feature | Details |
|---|---|
| Issuer | Issued by AmFirst Insurance Company, statutory office in Oklahoma City, and powered by Axonic Insurance; rated A- (Excellent) by AM Best |
| Contract Type | Multi-year guaranteed annuity; single premium deferred annuity with a market value adjustment |
| Guarantee Periods | 2, 3, 5, 7, or 10 years |
| Issue Ages | Through age 89 |
| Premium | $20,000 minimum; amounts above $1,000,000 require approval |
| Funding Sources | Non-qualified, traditional IRA, Roth IRA, 401(k), SEP IRA, and inherited IRA; see moving an inherited IRA into an annuity |
| Annual Withdrawal Allowance | None in year one; afterward, 10% of the prior-anniversary contract value each year, $500 minimum per withdrawal |
| Surrender Charges | Start at 9% (9.2% on the 10-year term) and decline each year; California schedules differ |
| Market Value Adjustment | Applies with surrender charges to excess withdrawals and surrenders; see surrender charges and the MVA |
| Review Period | Up to 30 days to cancel after purchase, or longer where state law requires |
| Renewal Window | 30 days before each term ends, with access to the full value at no charge |
| Waivers | Nursing home and terminal illness waivers when the owner was under age 80 at issue; not offered in California |
| Ownership | Individual or joint; a joint owner must be a spouse |
| Availability | Sold in 43 states and the District of Columbia; not offered in New York, New Jersey, Connecticut, Rhode Island, North Carolina, Minnesota, or Wisconsin |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Issues Waypoint MYGA
Axonic Insurance designed Waypoint MYGA and services it, but the insurer that issues the contract, and stands behind its guarantees, is AmFirst Insurance Company, whose statutory office is in Oklahoma City, Oklahoma. AmFirst is licensed in 47 states, the District of Columbia, Puerto Rico, and the British Virgin Islands, and it operates under the name AmFirst Life Insurance Company in California. Axonic Insurance Services acts as the general distributor and service provider, handling the day-to-day administration that policyholders deal with.
The issuer matters more on a MYGA than on almost any other financial product, because the entire value of the contract is a promise from the insurer to pay a stated rate and return your money. Waypoint is not a bank product and is not insured by the FDIC; its guarantees rest on the claims-paying ability of AmFirst. AM Best has affirmed AmFirst’s Financial Strength Rating of A- (Excellent) and its long-term issuer credit rating, also at A-. For context on where an A- sits among AM Best’s grades, see our explainer on what an AM Best rating means.
Axonic describes the product on its own Waypoint MYGA product page, which also hosts the brochure and specification sheet. Our company review, is Axonic a good company, looks more broadly at the firm, its reinsurance relationships, and its other annuities. Because ratings are reviewed periodically, confirm AmFirst’s rating at the time you apply.
How a Multi-Year Guaranteed Annuity Works
A multi-year guaranteed annuity is the simplest kind of deferred annuity. You make a single premium payment, the insurer guarantees a fixed interest rate for a set number of years, and your money grows at that rate regardless of what happens in the stock or bond markets. There are no index options to choose and no caps or participation rates to monitor. Our overview of multi-year guaranteed annuities covers how the product category works in general.
Waypoint follows that design. Axonic’s materials describe a guaranteed rate of return for the duration of the guarantee period you choose, along with full protection of principal from market fluctuations. Interest grows tax-deferred, so you pay no income tax on it until you withdraw it, which allows the full credited interest to keep compounding inside the contract.
In exchange for the guarantee, you agree to leave the money in place. That is the defining trade-off of every MYGA. Insurers typically invest MYGA premiums in assets matched to the length of the guarantee, and surrender charges and a market value adjustment protect the insurer if you leave early. Waypoint’s rules for access, described below, are designed around that bargain, and the guarantee is only as useful as your ability to keep the money in the contract for the full term you select.
Five Guarantee Periods
Waypoint offers guarantee periods of two, three, five, seven, and ten years, which covers nearly every planning horizon a fixed annuity buyer is likely to have. Shorter terms suit savers who want CD-like timing and expect to need the money, or to want a fresh rate decision, relatively soon. Longer terms suit savers who are confident the money can stay put and who want to lock a rate for as long as possible.
The right term usually depends on three questions: when you might need the money, how the rates on different terms compare, and how you feel about rates changing in the future. If longer terms pay noticeably more, locking in can make sense. If the rate difference between terms is small, a shorter term preserves flexibility at little cost. Because MYGA rates change with the interest rate environment, the comparison has to be made using the rates in effect when you apply.
The choice of terms also makes Waypoint a candidate for a ladder, in which money is split across several contracts that mature in different years. A ladder gives you a renewal window more often, spreads interest rate risk across time, and creates predictable points at which money becomes available without penalty. Our guide to laddering fixed annuities for retirement shows how the strategy is built.
Building a Ladder With Waypoint Terms
A simple hypothetical shows how the term choices can work together. Suppose a retiree has $200,000 to place and splits it into four Waypoint contracts of $50,000 each, with 2-, 3-, 5-, and 7-year guarantee periods. Each contract meets the $20,000 minimum and earns the rate available for its own term at issue. Instead of one renewal window, the retiree now has windows in years two, three, five, and seven.
At each of those windows, that contract’s money can be reached with no surrender charge and no MVA. The retiree can spend it, renew it, or move it into a longer term at whatever rates prevail at the time, gradually building a ladder in which some money matures every year or two. If rates have risen, the maturing contract captures the higher rates; if they have fallen, the money still in longer terms keeps its original guarantee.
The trade-off is complexity and, sometimes, rate. Longer terms may pay more than shorter ones, so a ladder can earn slightly less than putting everything into the longest term, and it means more contracts to track. For many retirees, the flexibility and the regular access points are worth that cost, particularly when part of the money may be needed within a few years. The rates for each term on the day you apply determine whether a ladder or a single contract makes more sense.
Surrender Charge Schedules by Term
Each Waypoint term has its own surrender charge schedule, applied to any withdrawal above the annual allowance and to a full surrender before the term ends. The charges decline each year and run through the guarantee period, although the California 10-year schedule reaches zero in its final year. The table below shows the schedules that apply outside California. Our explainer on annuity surrender charges explained covers how these charges work across the market.
| Contract Year | 2-Year | 3-Year | 5-Year | 7-Year | 10-Year |
|---|---|---|---|---|---|
| Year 1 | 9.00% | 9.00% | 9.00% | 9.00% | 9.20% |
| Year 2 | 8.00% | 8.00% | 8.00% | 8.00% | 8.30% |
| Year 3 | – | 7.00% | 7.00% | 7.00% | 7.40% |
| Year 4 | – | – | 6.00% | 6.00% | 6.50% |
| Year 5 | – | – | 5.00% | 5.00% | 5.60% |
| Year 6 | – | – | – | 4.00% | 4.70% |
| Year 7 | – | – | – | 3.00% | 3.80% |
| Year 8 | – | – | – | – | 2.80% |
| Year 9 | – | – | – | – | 1.90% |
| Year 10 | – | – | – | – | 0.90% |
Two details stand out. First, the 2-, 3-, 5-, and 7-year schedules all start at 9 percent and drop by one point a year, so a shorter term simply ends the schedule sooner. Second, the 10-year schedule starts slightly higher, at 9.2 percent, and steps down more gradually to 0.9 percent in the final year. Dashes mark years after a term has ended; if the contract renews, a new surrender schedule begins with the new guarantee period. On a $100,000 contract, a full surrender in the first year of a 5-year term would cost about $9,000 in surrender charges before any market value adjustment, which is why the term should never be longer than the time the money can truly stay in place.
California Has Its Own Schedule
Waypoint is available in California, but California residents receive a different surrender charge schedule. The California schedules start at 8.3 percent in the first year and step down to 7.4 percent, 6.5 percent, 5.6 percent, and 4.7 percent in years two through five. The 7-year term continues to 3.75 percent and 2.85 percent in years six and seven, and the 10-year term continues further to 1.9 percent in year eight, 0.95 percent in year nine, and zero in year ten.
Shorter California terms simply stop at the end of their guarantee periods, so a 2-year California contract carries charges of 8.3 and 7.4 percent, and a 3-year contract adds 6.5 percent in year three. Axonic also directs California residents to the market value adjustment rider in their contract for details specific to that state.
Two other California differences deserve attention. The nursing home confinement and terminal illness waivers described later on this page are not available in California, so California owners do not have those exits from surrender charges. And because the contract is issued in California under the name AmFirst Life Insurance Company, the name on a California owner’s paperwork may differ slightly from the one used elsewhere. Anyone buying Waypoint in California should review the California version of the contract rather than relying on the general materials, and our office can walk through the state-specific provisions before you apply.
The Market Value Adjustment
Waypoint includes a market value adjustment, often called an MVA, that applies along with surrender charges when you withdraw more than the annual allowance or surrender the contract during a guarantee period. The MVA adjusts the amount you receive to reflect changes in interest rates since the current guarantee period began, as defined in the contract’s MVA rider. In general, if rates have risen, the adjustment reduces what you receive, and if rates have fallen, it can increase it, subject to the contract’s terms and limits.
The logic becomes clear when you look at it from the insurer’s side. When you buy a MYGA, the insurer invests your premium in bonds and similar assets that match your term. If you leave early after rates have risen, those assets are worth less than when they were bought, and the MVA passes part of that loss to the departing owner. If rates have fallen, the assets are worth more, and the MVA can pass some of that gain back.
What matters most for planning is when the MVA does not apply. It does not apply to withdrawals within the annual allowance, to surrenders or withdrawals during the 30-day window at the end of a guarantee period, or to withdrawals that qualify under the nursing home or terminal illness waivers. Staying within those boundaries means the MVA never touches your money. The exact formula, including any limits on how large the adjustment can be, is set out in the contract’s MVA rider.
Access to Your Money: The First Year and After
Waypoint’s withdrawal rules are tighter in the first contract year than many buyers expect. The materials describe penalty-free withdrawals as beginning after the first contract year, so any withdrawal during year one is subject to surrender charges and the market value adjustment unless it qualifies under the terminal illness waiver. The nursing home waiver cannot help in year one, because it requires that the owner was not confined during the first contract year. Anyone who may need part of the money within the first twelve months should keep that money elsewhere.
From the second contract year on, each contract year you can withdraw an amount equal to one-tenth of the contract value on the most recent anniversary, with no surrender charge and no MVA. You can take that amount in more than one withdrawal, with a $500 minimum for each, and every withdrawal reduces the remaining allowance until the next anniversary. Anything above the allowance in a given contract year is subject to the surrender charge and the MVA.
The allowance resets each anniversary based on the contract value at that time, so it grows as interest is credited. On a contract worth $110,000 at an anniversary, for example, the allowance for the following year would be $11,000. The materials do not say that unused allowance carries forward to later years, so owners who want regular access should plan as if it does not and take what they need within each contract year. Keeping a separate emergency reserve outside the contract is the simplest way to avoid ever needing more than the allowance.
Taking Interest as Income
Many MYGA owners want the contract to pay them something along the way rather than simply accumulate. Waypoint allows that within the annual allowance. According to Axonic’s brochure, after the first contract year owners may elect systematic withdrawals as part of the penalty-free withdrawal provision, including the ability to automatically withdraw earned interest on a quarterly basis.
Taking interest only keeps the principal intact while turning the contract into a source of regular payments, which can work well for retirees who want predictable cash flow from savings without the commitment of annuitization. The trade-off is that interest withdrawn is interest that no longer compounds, so the contract value at the end of the term will be lower than if the interest had stayed in place.
Interest paid out of a non-qualified contract is generally taxable as ordinary income in the year it is received, and an owner younger than 59 and a half can owe an extra IRS penalty on top of that tax. Because the systematic option operates within the 10 percent allowance, owners whose interest exceeds that amount in a given year, or who also want occasional extra withdrawals, should map out the year’s total so it stays within the limit. Axonic’s materials suggest contacting its service team for other withdrawal options, and our office can help arrange the right setup at issue.
Want to see Waypoint side by side with other top MYGAs?
Compare MYGA Rates
The 30-Day Window at Renewal
The most valuable feature of Waypoint may be the one that only appears at the end of each term. Thirty days before the initial guarantee period or any later guarantee period ends, Axonic sends a notice stating when the period is ending, the renewal rate that would apply, and the surrender charges in effect for the next period. That notice opens your decision window, and during it your money can move with no surrender charge and no MVA.
Some fixed annuities offer a bail-out provision, which lets owners leave without penalty if the renewal rate falls below a stated level. Waypoint’s materials do not describe a bail-out provision, and with a rate guaranteed for the entire term, the end-of-term window serves a similar purpose: it is your scheduled opportunity to judge the renewal rate against the market and leave if it falls short. Our explainer on what an annuity bail-out provision is covers how those provisions work on other contracts.
The table below lists the five choices available before the guarantee period ends, as described in Axonic’s materials.
| Your Choice | What Happens |
|---|---|
| Renew for the same term | The contract continues for the same guarantee period at the declared renewal rate, with a new surrender schedule |
| Choose a different term | The contract continues for another guarantee period available at renewal |
| Surrender the contract | You receive the full value with no surrender charge and no market value adjustment |
| Take part, renew the rest | You withdraw part of the value penalty-free and apply the remainder to the same or a different guarantee period |
| Annuitize | You apply the contract value to a settlement option for guaranteed payments |
What Happens If You Do Nothing
If you make no election before the guarantee period ends, Waypoint renews automatically for the same guarantee period at the declared renewal rate. That default protects you from having your money sit idle, but it also starts a new surrender charge period. An owner who misses the window on a 7-year contract, for example, could find the money committed for another seven years at a renewal rate that may be lower than what competing MYGAs pay at that time.
Renewal rates are declared by the insurer when each period ends, and nothing in the materials guarantees how a renewal rate will compare with the original rate or with the market. That is true of MYGAs generally, which is why the end of every term should be treated as a fresh buying decision rather than an automatic continuation.
The practical safeguards are simple. Keep the contract’s issue date and term end date somewhere you will see them, and make sure the address and phone number on file with Axonic stay current so the renewal notice reaches you. Our office can help you keep track of the date and review your options as a window approaches, so the choice is made deliberately. When the notice arrives, compare the renewal rate with current rates for the same and other terms, consider whether your plans for the money have changed, and decide whether renewing, switching terms, splitting the money, or moving it elsewhere fits best.
Waypoint Versus CDs and Savings Accounts
MYGAs are often compared with bank certificates of deposit, and the comparison is useful as long as the differences are clear. Both pay a fixed rate for a set term, both penalize early withdrawals, and both are considered conservative places for money. Our comparison of how MYGAs compare to CDs covers the topic in depth. The table below reflects the comparison Axonic includes in its own brochure, with terms of individual bank accounts varying by institution.
| Feature | Savings Account | Bank CD | Waypoint MYGA |
|---|---|---|---|
| Tax Deferral | No | No | Yes |
| Access Without Penalty | Limited number of withdrawals per month | Generally none before maturity | 10% of value each year after year one |
| Early Access Cost | No fees | Penalty on withdrawals before maturity | Surrender charge and MVA above the allowance |
| Protection | FDIC insured within limits | FDIC insured within limits | Backed by AmFirst Insurance Company |
The tax difference is often the deciding factor for larger balances. Interest on a CD held in a taxable account is generally taxed each year as it is earned, while interest inside a non-qualified MYGA is not taxed until it is withdrawn, so more of it stays invested and compounds. The protection difference cuts the other way: a CD carries FDIC insurance within federal limits, while Waypoint relies on the strength of its issuer, with state guaranty associations providing limited protection that depends on where the owner lives and the limits of that state.
Taxes on Waypoint Interest
When Waypoint is bought with after-tax savings, the interest compounds without current tax. When you withdraw, the IRS generally treats the interest as leaving first and taxes it at ordinary income rates; your original premium comes back tax-free only after the interest has been paid out. A full surrender at the end of a term would make all of the accumulated interest taxable in that year, which is one reason some owners prefer to renew or spread withdrawals across several tax years.
The IRS generally adds a 10 percent penalty on the taxable portion of withdrawals taken before age 59 and a half, on top of regular income tax, although exceptions exist. Because Waypoint can be issued at younger ages, anyone under that age should understand the penalty before buying. Our guide to the IRS early withdrawal penalty explains how it works and the strategies that can avoid it.
Annuitization changes the tax picture. If you annuitize a non-qualified Waypoint contract, part of each payment is treated as a return of your premium and is not subject to ordinary income tax, while the rest is taxable; the split is determined when you annuitize. For contracts funded with traditional IRA, SEP IRA, or 401(k) money, withdrawals are generally taxable in full, and holding an annuity inside a tax-qualified plan does not add any extra tax benefit beyond what the plan already provides. Tax rules can change, so it is wise to involve a tax professional whenever significant sums are at stake.
IRA, Roth, and 401(k) Money
Waypoint accepts traditional IRA, Roth IRA, SEP IRA, and 401(k) funding in addition to non-qualified money. Qualified money is typically moved by direct transfer or direct rollover, which keeps it inside its tax-advantaged status and avoids withholding. Inside an IRA, a MYGA works like any other conservative IRA holding: the fixed rate applies, and the account’s own tax rules govern withdrawals.
Required minimum distributions deserve planning. Axonic’s materials describe RMD withdrawals as penalty-free, with no MVA, once the first contract year has passed, as long as they fall within the remaining annual withdrawal allowance. Owners who are already taking RMDs, or who will reach RMD age during the first contract year, should decide in advance how the first year’s distribution will be handled, for example by satisfying it from the IRA before the transfer or from another IRA account, so a surrender charge never applies. Our guide to required minimum distribution rules explains the calculation.
Inside a Roth IRA, the Roth rules govern: qualified withdrawals generally come out tax-free, and the original owner is not subject to lifetime RMDs under current rules. That makes a Roth-funded MYGA a natural fit for money the owner does not expect to touch, since the fixed rate compounds without any tax drag. For SEP IRA and 401(k) money, the same transfer and RMD considerations apply as for a traditional IRA.
Using Waypoint for an Inherited IRA
Waypoint’s materials list inherited IRA money among the accepted funding sources, which makes it a possible home for an IRA you have received from a parent or another family member. A fixed rate can be attractive for inherited money, because many beneficiaries want to preserve the value while they decide how and when to withdraw it.
The key is matching the contract to the withdrawal rules. Under current law, most beneficiaries other than a surviving spouse have to drain an inherited IRA within ten years of the original owner’s death, and some must also take annual distributions during that period. A Waypoint term that ends inside that deadline, and a withdrawal plan that respects the annual allowance, can keep the account growing at a guaranteed rate without forcing a surrender charge. Our explainer on the inherited IRA ten-year rule covers the deadlines in more detail.
The first-year rule matters here too. Because penalty-free withdrawals begin after the first contract year, a beneficiary who must take an annual distribution should time the transfer so that the first year’s required amount is handled before the money moves, or confirm with Axonic how a first-year required distribution would be treated. Spouses who inherit an IRA often have additional choices, including treating it as their own, and those choices should be settled before the transfer because they change which rules apply.
Moving IRA, 401(k), or inherited money into a MYGA?
Start My Transfer Review
Nursing Home and Terminal Illness Waivers
Two waivers can open the contract beyond the annual allowance, with surrender charges set aside and no MVA. To use the nursing home waiver, the owner must have spent 90 or more consecutive days in an eligible nursing home, must not have been in one at any point during the first contract year, must have held the contract without interruption from its start, and must have been under age 80 when it was issued. The waiver works alongside the annual allowance rather than replacing it: it applies once no penalty-free amount remains for the year. Axonic needs proof of the stay along with a written statement, and the request generally has to arrive no later than 90 days after the stay ends.
The terminal illness waiver turns on a physician’s certification that the owner is expected to live 12 months or less. With that certification in hand, the owner may cash in the whole contract or take partial withdrawals of $1,000 or more, with no surrender charge and no MVA, as long as ownership has been continuous and the owner was under 80 at issue.
These waivers are liquidity protections, not care benefits. They make the contract value easier to reach during a health crisis, but they do not add money to pay for care. Neither waiver is available in California, and neither applies to owners who were 80 or older when the contract was issued, even though Waypoint can be issued much later. For buyers whose main concern is paying for long-term care, our guide to annuities as a long-term care alternative covers products built for that purpose.
Death Benefit and Settlement Options
Should the owner die before annuity payments start, Waypoint pays the value of the annuity to the beneficiary in a lump sum. If the owner dies after annuity payments have begun, any remaining payments go to the beneficiary according to the payout option that was chosen. Because a MYGA’s value grows at a fixed rate, the death benefit before annuitization is predictable throughout the term, apart from the effect of any withdrawals.
Beneficiaries of a non-qualified contract generally owe income tax on the interest portion of what they receive, since inherited annuity gains carry no step-up in cost basis. Beneficiary designations should be reviewed when the contract is issued and whenever family circumstances change, because the designation, not a will, generally controls who receives the money.
For owners who want to turn the contract into guaranteed income, Waypoint offers four settlement options: a lump sum, life only, life with a 10-year period certain, and joint and last survivor with a 10-year period certain. A life-only payout pays the most each month but stops at death, while the period certain options guarantee that payments continue for at least ten years even if the annuitant dies early. Our explainer on life with period certain annuities describes how that guarantee works. Annuitization can be elected at the end of a guarantee period without surrender charges, and the payout amount depends on the rates and the annuitant’s age at the time.
Issue Ages Through 89
Waypoint can be issued up to age 89 and 364 days, which makes it available to savers well into their eighties. Retirees at those ages who hold CDs or savings they want to keep safe while earning a guaranteed rate can use a short Waypoint term for that purpose without locking money away for long.
For older buyers, the term choice deserves extra care. A 2- or 3-year term creates frequent windows to reassess, while a 7- or 10-year term ties up money for a longer share of the owner’s remaining years. Since both waivers are limited to owners who bought before turning 80, buyers aged 80 or older would not have those exits, so liquidity planning matters even more at those ages.
Older buyers should also think about how the money will pass to heirs. Naming beneficiaries carefully, considering whether a spouse should be a joint owner, and coordinating the contract with any trust or estate plan can prevent delays later. Suitability rules require that an annuity recommendation fit the buyer’s age, liquidity needs, and financial situation, and a shorter term with a clear plan for the money at maturity is often the most suitable choice for savers in their late eighties.
Waypoint Versus Trailhead
Axonic offers more than one annuity issued by AmFirst, and buyers sometimes compare Waypoint with the Trailhead fixed indexed annuities. The difference is in how growth is earned. Waypoint pays a declared fixed rate that is guaranteed for the full term, so the result is known in advance. Trailhead contracts credit interest based partly on index performance, with protection from market losses, so the result varies from year to year.
The income-focused version, reviewed on our Axonic Trailhead FIA Income annuity page, adds a guaranteed lifetime withdrawal benefit rider with an income base, roll-up credits, bonuses, and an annual rider fee. That design serves buyers who want a guaranteed lifetime paycheck starting at a future date, while Waypoint serves buyers who want a guaranteed rate on savings for a defined period.
The liquidity rules differ as well. Trailhead FIA Income uses a single ten-year surrender schedule, while Waypoint lets you choose a schedule as short as two years. For money that may be needed in the next few years, or for savers who simply want certainty about what their balance will be, Waypoint is usually the better match. For money meant to produce lifetime income, an income rider product may fit better, and some buyers use both for different portions of their savings.
Who Waypoint Fits, and Who It Does Not
Waypoint tends to fit savers who want a guaranteed fixed rate, full protection from market losses, and tax deferral, and who can leave the money in place for the full term they choose. That includes retirees moving maturing CDs, pre-retirees parking money they plan to use at a known date, IRA owners who want a conservative holding, beneficiaries managing an inherited IRA within its deadlines, and anyone building a ladder of fixed contracts with staggered maturities.
It is a weaker fit for money that may be needed within the first contract year, because there are no penalty-free withdrawals in that year. It is also a weaker fit for savers who want growth potential tied to markets, who need guaranteed lifetime income with features such as roll-ups or bonuses, or who live in one of the seven states where it is not sold: New York, New Jersey, Connecticut, Rhode Island, North Carolina, Minnesota, and Wisconsin.
Finally, because a MYGA’s appeal rests almost entirely on its rate, Waypoint fits best when its rate for your chosen term is competitive with other MYGAs from comparably rated insurers. A contract with sound terms but a below-market rate is not a good trade, which is why the comparison should always be made with current rates for the specific term you are considering.
Questions to Ask Before You Buy
Start with how long the money can truly stay untouched. Choose the term to match that horizon, remembering that year one offers no penalty-free withdrawals and that surrender charges apply throughout the term. If the answer is uncertain, a shorter term or a ladder across several terms may be wiser than a single long contract.
The second is how Waypoint’s current rate for your term compares with competing MYGAs and with CDs. The third is how the money is titled and funded, whether non-qualified, IRA, Roth, 401(k), SEP, or inherited IRA, because that determines the tax treatment and any distribution requirements you need to plan around, including in the first year.
The fourth is what you will do at the end of the term. Know the date your renewal window opens, and plan to review the renewal rate against the market rather than letting the contract renew by default. The fifth is whether the waivers matter to you, keeping in mind the under-80 issue-age limit and the California exclusion. Finally, consider who should be named as beneficiary and whether a spouse should be a joint owner. Working through these questions before applying helps you choose the right term and avoid surprises later.
How Our Office Helps
Every Waypoint recommendation from our office begins with your timeline and the purpose of the money. Jason and our office ask when you might need access, what the money is ultimately for, how it is currently held, and whether income, growth, or simple preservation matters most. Those answers decide which term fits and whether Waypoint belongs on the short list at all.
From there, we compare Waypoint’s current rate for the term you choose with competing MYGAs from comparably rated insurers, explain the surrender charges, market value adjustment, and first-year rules in plain terms, and coordinate any CD, IRA, 401(k), inherited IRA, or annuity transfer so the money moves without unnecessary taxes or penalties. People often wonder whether a broker raises the price, and we tackle that in our article asking is it cheaper to use a broker.
Once the contract is issued, we help you plan for the renewal window, review the renewal rate when the notice arrives, and compare it with what the market offers at that time. As an independent office, we can recommend renewing, switching terms, splitting the money, or moving it to another carrier, so each decision is based on your needs rather than a single company’s shelf.
Ready to lock in a guaranteed rate?
Talk to Our Office
Financial Protection Essentials
More resources for earning a guaranteed rate on your savings.
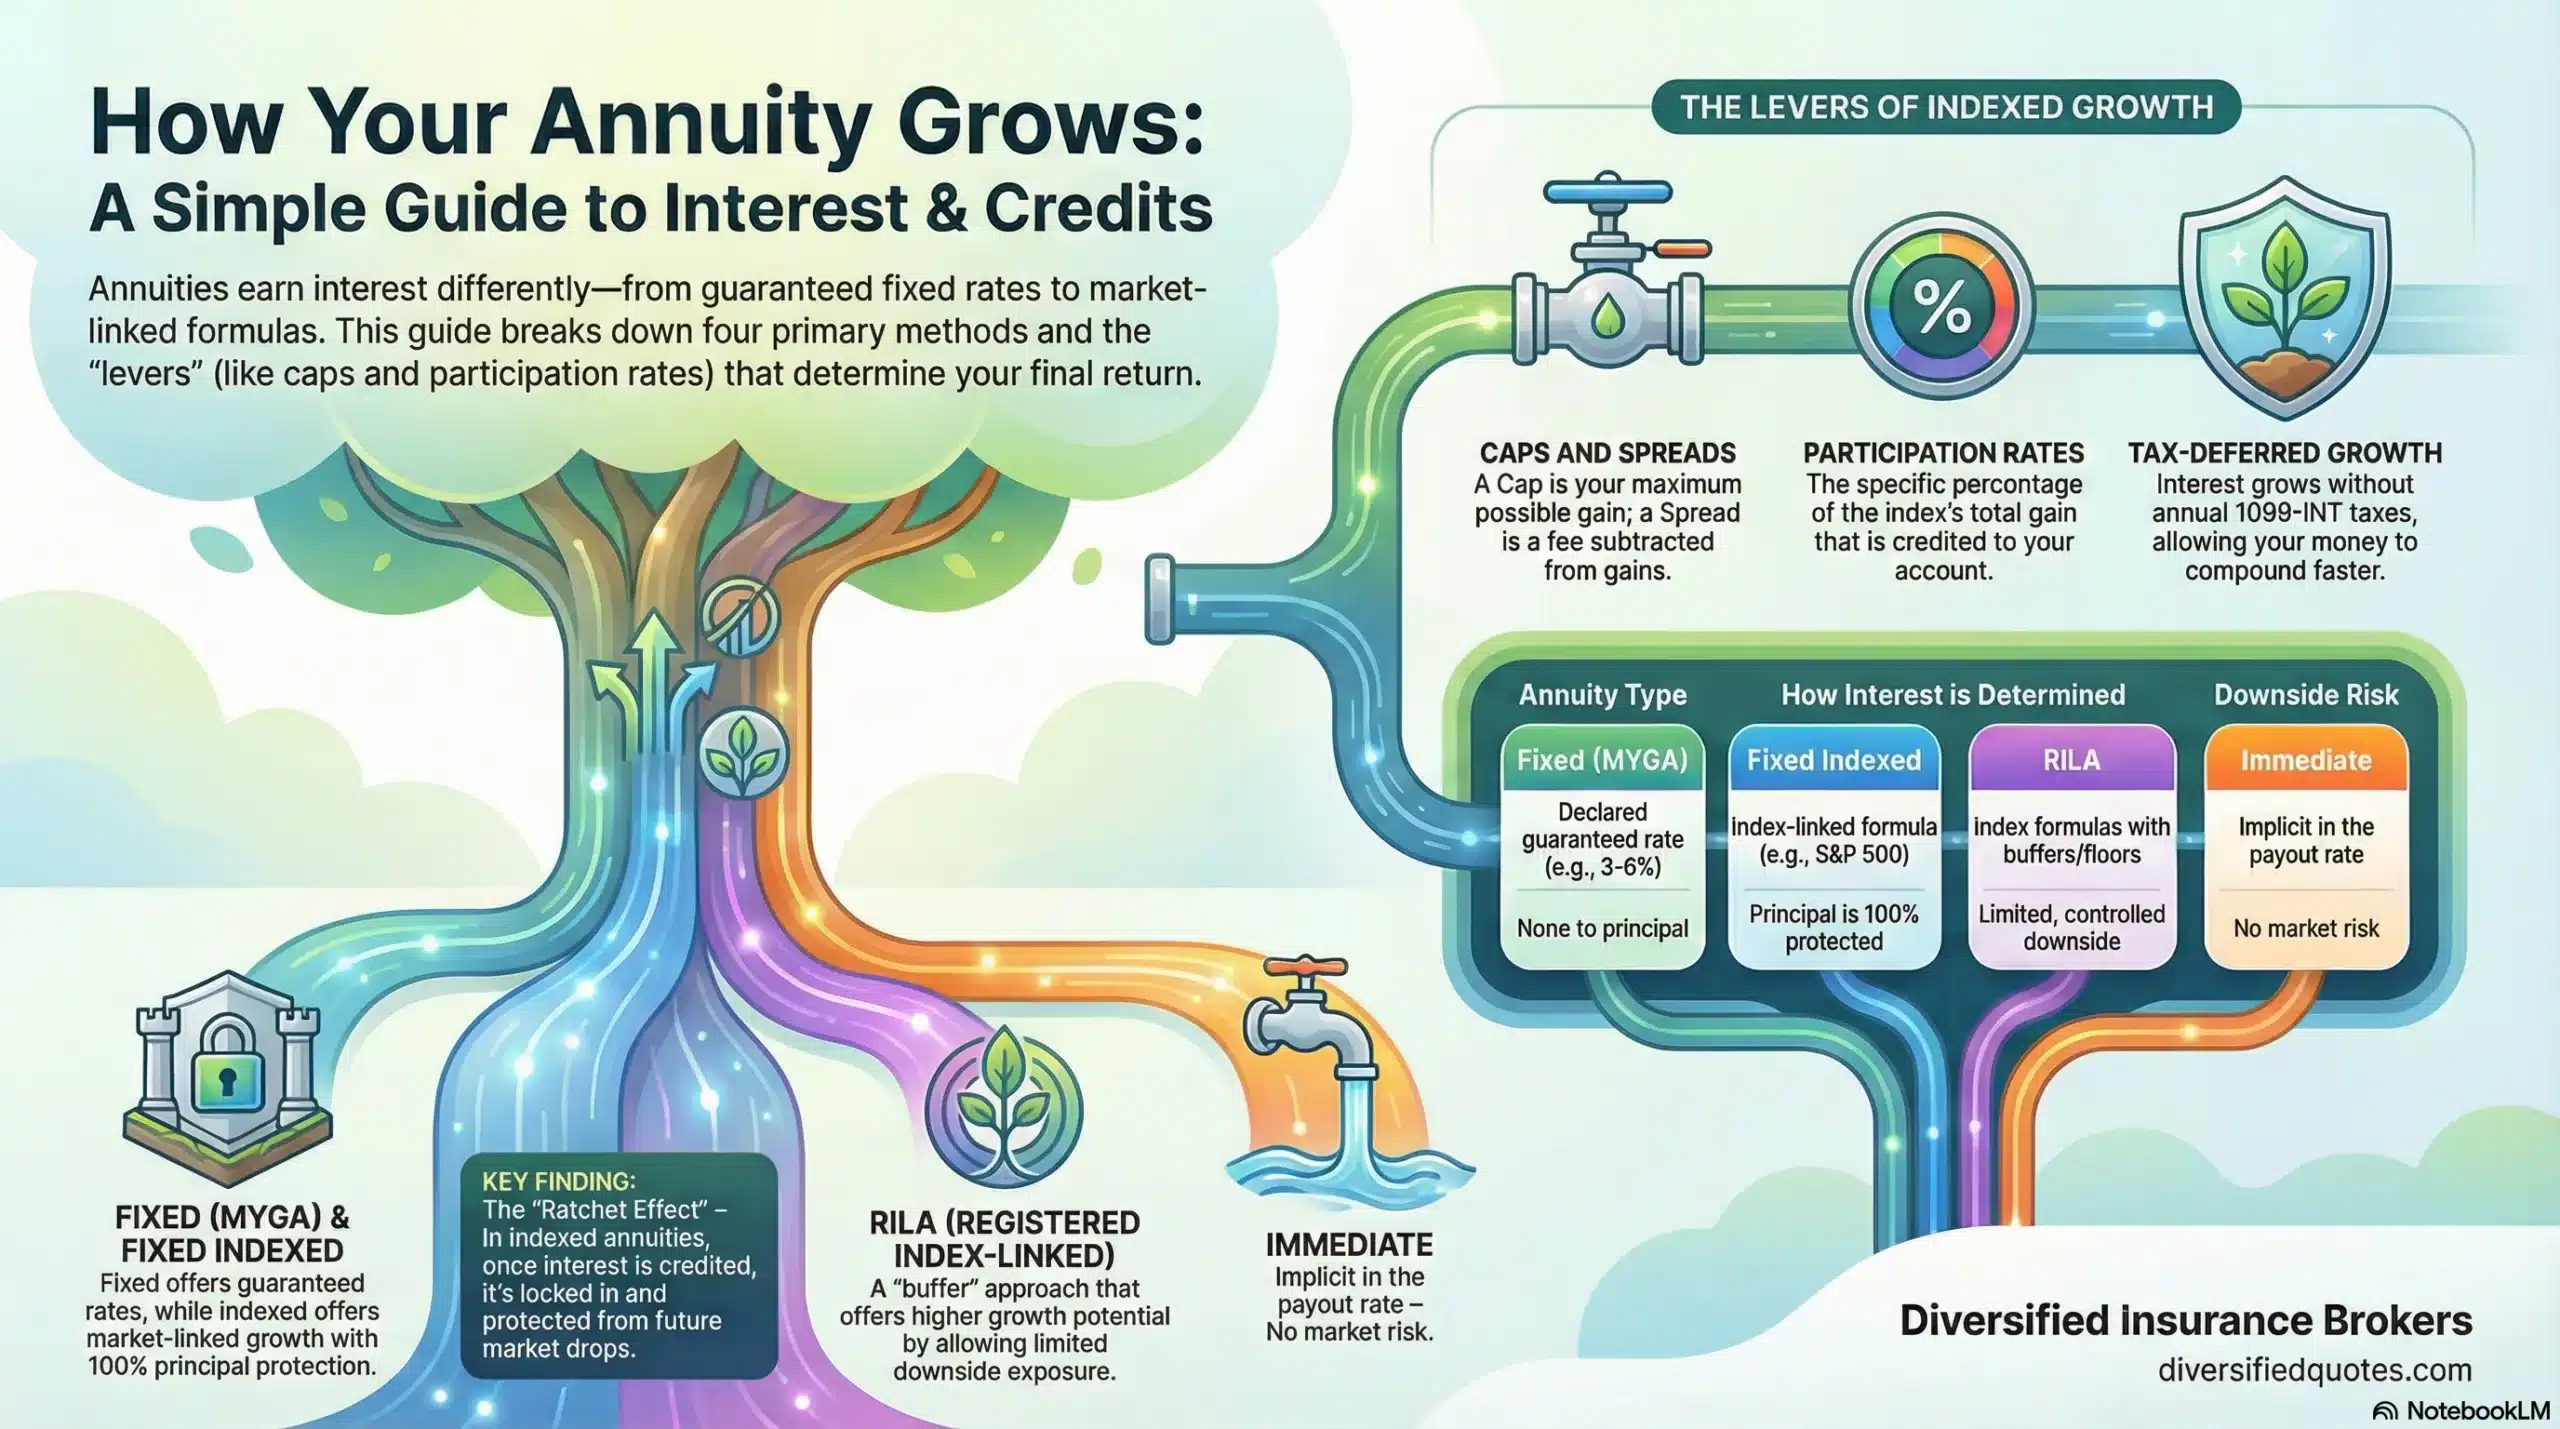
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Can I move a maturing CD into Waypoint MYGA?
Yes. Maturing CDs are a natural source of MYGA money, since both pay a fixed rate for a set term. For a CD that is still mid-term, find out from the bank how large the early withdrawal penalty would be before you move it. The process is laid out in our guide to transferring a CD into an annuity.
How is interest from a non-qualified Waypoint contract taxed?
Interest is not taxed while it stays in the contract. Once withdrawn, it is generally ordinary income, and the IRS treats interest as coming out ahead of your premium. Owners under 59 and a half can also owe a 10 percent IRS penalty on the taxable amount. Our page on non-qualified annuity taxation explains the rules.
Can I move an existing annuity into Waypoint without paying tax?
Generally yes, if the move is set up as a direct exchange or transfer. A non-qualified annuity can usually be exchanged for another annuity tax-free, and an IRA annuity can be moved by direct transfer. Before moving, weigh any surrender charges left on the old contract and any features you would lose. The mechanics are covered in our explainer on how 1035 exchanges work.
What do my beneficiaries receive if I die?
If you die before annuity payments begin, Waypoint pays the value of the annuity to your beneficiary in a lump sum. If payments have begun, any remaining payments follow the payout option you chose. Beneficiary options are explained in our guide to what happens to annuities at death.
Is Waypoint protected if the insurer fails?
No FDIC coverage applies; Waypoint’s promises depend on AmFirst Insurance Company paying its claims. Beyond that, state guaranty associations offer a backstop to annuity owners when an insurer becomes insolvent, up to limits each state sets. Details are in our overview of state guaranty association coverage.
Is a MYGA the same as a charitable gift annuity?
No. A MYGA is a savings contract with an insurer that returns your money with guaranteed interest. A charitable gift annuity is an arrangement with a charity in which you donate assets in exchange for lifetime payments and a potential tax deduction. Our guide to charitable gift annuities explains how they work.
What happens if interest rates rise after I buy?
Your Waypoint rate stays locked for the full guarantee period. If you leave early after rates rise, the market value adjustment would generally reduce what you receive, in addition to surrender charges. Waiting for the renewal window avoids both. Our explainer on how a market value adjustment works covers the details.
How does Waypoint compare with other top MYGAs?
The comparison comes down to rate, issuer rating, surrender schedule, withdrawal rules, and waivers for the term you want. Waypoint’s strengths include five term choices and issue ages through 89, while its lack of penalty-free withdrawals in year one is a limitation. Our ranking of the best MYGA annuity rates shows how leading contracts compare.
Can I add money to my Waypoint contract later?
Waypoint is a single premium deferred annuity, so it is funded once at issue. Adding money later means purchasing a new contract at the rate available at that time, which can also be a simple way to build a ladder of contracts with different maturity dates.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to What Is a Fixed Annuity? — covering fixed annuities, MYGAs, laddering strategies & conservative growth options from 100+ carriers.
Last Reviewed: October 18, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
