
Ameritas RateLock MYGA Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Ameritas RateLock MYGA Annuity
RateLock Annuity, issued by Ameritas Life and Annuity Company, is a single premium multi-year guaranteed annuity that does one job well: it locks a fixed interest rate for a term you choose, three, five, or seven years, and credits that rate for the entire guarantee period regardless of what markets or interest rates do in the meantime. Its namesake feature adds a useful twist. If your money arrives within 60 days of the application, Ameritas compares the rate in effect on the application date with the rate in effect when the funds are received and gives you the higher of the two. The contract is issued by Ameritas Life Insurance Corp., which AM Best rates A (Excellent). The trade-offs are typical of MYGAs: surrender charges that start at 9 percent, a market value adjustment during the surrender period, and limited access beyond the yearly penalty-free amount. Everything else on this page sits on top of that.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this review of RateLock reflects how our office evaluates fixed annuities for clients who want guaranteed growth. Working as an independent annuity broker, we compare RateLock’s current rates, surrender schedule, and contract features against multi-year guaranteed annuities from other carriers so you can see where it fits and where another contract might serve you better.
Want today’s RateLock rates for your term and deposit?
Get RateLock Rates
RateLock MYGA at a Glance
| Feature | RateLock Details |
|---|---|
| Issuing Company | Ameritas Life Insurance Corp., Lincoln, Nebraska |
| Product Type | Single premium multi-year guaranteed fixed annuity |
| Guarantee Periods | 3, 5, or 7 years; compare the shorter term with other short-term MYGA options |
| Issue Ages | 0 through 90, age nearest birthday, for both owner and annuitant |
| Premium | $10,000 minimum single premium; $2 million maximum per owner across all Ameritas policies without home office approval; no additional deposits after issue |
| Rate Bands | Lower band for amounts under $100,000; higher band for $100,000 and above |
| Rate Lock | Funds received within 60 days of application get the higher of the application-date rate or the rate on the date funds arrive |
| Withdrawal Access | Up to 10 percent of the beginning-of-year accumulation value each policy year with no surrender charge or MVA; see annuity free withdrawal rules |
| Surrender Charges | Start at 9 percent in year one and decline to zero when the guarantee period ends |
| Market Value Adjustment | May apply to excess withdrawals during the surrender period; does not apply at death; varies by state |
| Waivers Included | Nursing care confinement, home health care, and terminal illness, at no added cost |
| Death Benefit | Accumulation value, with no surrender charge or MVA |
| End of Guarantee Period | Renew for a new term, move to a one-year declared rate, withdraw, or annuitize |
| Eligible Money | Nonqualified savings, Traditional, Roth, SEP, and SIMPLE IRAs, pension and profit sharing plans, 401(k), and 457 plans |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Issues RateLock
RateLock is issued by Ameritas Life Insurance Corp., based in Lincoln, Nebraska. Ameritas, whose roots go back well over a century, is a marketing name for the subsidiaries of Ameritas Mutual Holding Company, which together offer life insurance, annuities, individual disability income insurance, group dental, vision, and hearing coverage, and retirement plans. Each Ameritas subsidiary is responsible for its own financial condition and contractual obligations, so the guarantees in a RateLock contract rest on Ameritas Life Insurance Corp.
In the most recent AM Best action we reviewed, Ameritas Life Insurance Corp. holds an A (Excellent) financial strength grade and an a+ issuer credit grade, both carrying a stable outlook. AM Best describes the company’s balance sheet strength as very strong, its operating performance as adequate, its business profile as favorable, and its enterprise risk management as appropriate, and it notes risk-adjusted capitalization in the strongest category of its capital adequacy measure. Read how the scale works in what an AM Best rating means.
That background matters for a MYGA, because a guaranteed rate is only as solid as the company promising it. Our full review asking whether Ameritas is a good insurance company covers its history and product lines in more depth. Ameritas also publishes a RateLock MYGA overview and quote tool on its website. Ratings change over time, so it is worth confirming the current rating before you buy.
MYGA Basics
Among deferred fixed annuities, the MYGA has the simplest design. You make one deposit, the insurer promises a declared rate for the length of the term, and interest builds on a tax-deferred basis until it is taken out. There are no index strategies, caps, or participation rates to track. The rate you lock in at the start is the rate you earn for the full guarantee period.
That predictability is the main reason people choose a MYGA. People often compare it with a bank CD, since each locks a rate for a term, yet they work differently underneath. The MYGA’s promise comes from an insurer, with state guaranty associations as a backstop up to their limits, while a CD carries FDIC coverage. MYGA interest waits to be taxed until you withdraw it, and getting out early means surrender charges and possibly an MVA rather than a bank penalty. More detail is in our piece on how MYGAs compare to CDs.
RateLock follows this familiar design closely. Premium is directed to a single guarantee period, and there is no premium load, so the full deposit goes to work from the first day, although premium taxes may apply in some states. The features that set RateLock apart sit around that core: the 60-day rate lock, the rate bands, the waivers, and the choices available when the guarantee period ends.
Choosing a 3-, 5-, or 7-Year Guarantee
RateLock offers three guarantee periods, and the choice shapes nearly everything else about the contract. A three-year term keeps money committed for the shortest time, with surrender charges that end after the third year. A five-year term extends that commitment, and a seven-year term extends it further, with a longer surrender schedule to match.
The longest term is not always the one with the highest rate. Insurers set each guarantee period’s rate based on their investment outlook, and the rate curve for MYGAs does not always rise with term length. In the launch materials we reviewed, the five-year term carried a higher rate than both the three-year and seven-year terms in each premium band, a pattern that can change whenever rates are reset. That is why it pays to compare all three terms at the time you buy rather than assuming the longest term pays the most.
The right term depends on when you expect to need the money and how you view future interest rates. A shorter term gives you a chance to reinvest sooner if rates rise, while a longer term protects you from falling rates for more years. Many buyers also consider age. Because renewal options can be limited at older ages to keep a new guarantee period from extending past the contract’s maturity age, someone buying in their late eighties should confirm which terms will be available at renewal.
The RateLock Feature: How the 60-Day Rate Lock Works
The feature that gives RateLock its name addresses a common problem with fixed annuity purchases: timing. Money often arrives at the insurer days or weeks after the application, especially when it is coming from another annuity, a bank, or a retirement plan. If rates change during that gap, the buyer can end up with a different rate than the one quoted.
According to the product guide, RateLock protects buyers in both directions for up to 60 days. When funds are received within 60 days after the application date, Ameritas compares the rate in effect on the application date with the rate in effect on the day the money arrives and applies the higher of the two. If rates fall while a transfer is in process, you keep the earlier rate. If rates rise, you receive the newer, higher rate. After 60 days, funds receive the current rate on the date they are received.
This is particularly useful for transfers that take time to complete. A 1035 exchange from another annuity, a direct transfer from an IRA custodian, or a rollover from an employer plan can take several weeks. Submitting the application early starts the 60-day window, and the higher-of comparison removes much of the risk of a rate change before the funds arrive. If you are moving money from a contract with its own surrender charges, coordinate the timing so you are not trading one penalty for another.
Rate Bands and Why $100,000 Matters
RateLock uses two rate bands. Premiums up to $99,999.99 fall into the lower band, and premiums of $100,000 or more fall into the higher band, which is designed to credit a higher rate. In the launch rates we reviewed, the higher band paid more on every term, although the gap between bands can change whenever rates are reset.
That threshold can make a real difference for buyers who are close to it. Someone with $95,000 to place may find that adding a small amount from savings to reach $100,000 moves the entire deposit into the higher band. Over a seven-year term, even a small rate difference on the full premium adds up. On the other hand, splitting a large sum between two contracts to build a ladder may drop each piece below the threshold, so the banding rules are worth considering when you plan how to divide your money.
Banding also applies later. According to the product guide, the band at renewal is based on the accumulation value when the contract enters a new guaranteed period. A contract that started below $100,000 but has grown past that level through credited interest may qualify for the higher band at renewal, while one that has been reduced below the threshold by withdrawals may fall into the lower band.
Premium Rules and Who Can Own a Policy
RateLock is a single premium contract. You make one deposit of at least $10,000 at issue, and no additional deposits are allowed afterward. If you expect to add money later, you would need a separate contract, which may land in a different rate band and carry its own surrender schedule. The maximum is $2 million per owner across all Ameritas policies combined, and amounts above that require home office approval.
The product guide lists issue ages from 0 through 90, based on age nearest birthday, and both the owner and the annuitant must fall within that range. RateLock can be bought with nonqualified savings or as a tax-qualified contract, including a Traditional IRA, Roth IRA, SEP IRA, SIMPLE IRA, pension or profit sharing plan, 401(k), or 457 plan. Non-spousal inherited annuities are not available, so a non-spouse beneficiary cannot use RateLock as an inherited, beneficiary-owned contract.
Every state requires a free-look period after the contract is issued, during which the owner can review it and return it for a refund of the premium paid. According to the product guide, the standard free-look period for a purchase that does not replace another contract is 20 days, unless a state requires longer, and replacement purchases can carry different periods. Ameritas reserves the right to reject an application or premium for regulatory reasons or if it does not meet the requirements, and contract features and riders may vary by state. RateLock is issued only in approved states and may not be available everywhere.
Withdrawals Without a Surrender Charge
RateLock allows a modest amount of access during the guarantee period. Each policy year, as much as 10 percent of the value measured at the start of that policy year can come out without a surrender charge or a market value adjustment. The minimum withdrawal is $500.
The beginning-of-year measurement matters. The 10 percent is calculated from the value at the start of the policy year, not from the value on the day you withdraw, so interest credited during the year does not raise that year’s allowance. The product materials we reviewed do not describe any carryforward of unused amounts, so unused penalty-free amounts in one year should not be counted on to increase the next year’s limit. Planning withdrawals around those rules helps you get the most from the provision.
Withdrawals above the penalty-free amount are allowed at any time by written request, but they are subject to the surrender charge for that policy year and any applicable market value adjustment. If a partial withdrawal would leave less than $500 in the contract, the remaining value is paid out and the contract is fully surrendered. Keep in mind that withdrawals are taxable events to the extent they include earnings. For most buyers, the right approach is to treat RateLock as money set aside for the full term, with the 10 percent allowance as a cushion rather than a primary source of cash.
Required Minimum Distributions Inside an IRA
If RateLock is held in a Traditional, SEP, or SIMPLE IRA or an employer plan, required minimum distributions will eventually apply; Roth IRAs are not subject to RMDs during the original owner’s lifetime. The timing and math behind RMDs are covered in our guide to required minimum distributions.
According to the product guide, under current company practice any RMD amount associated with the policy may be withdrawn without penalty, beginning after the first policy year. That is helpful for owners already taking distributions, because it means an RMD larger than the 10 percent allowance does not trigger a surrender charge once the first policy year has passed. Company practices can change, so it is worth confirming how RMDs are handled when you buy.
Two practical points help avoid problems. First, if you are transferring or rolling over money from another IRA or plan, take any RMD due for that year before the transfer, because the guide notes that RMD amounts should be withdrawn prior to the transfer request. Second, distributions from all of your IRAs taken in the same calendar year generally count toward your total RMD, so you may be able to satisfy the requirement from another account and leave RateLock untouched during its first year. Coordinating those details at purchase keeps the RMD rules and the contract rules working together rather than against each other.
Surrender Charges by Guarantee Period
Surrender charges apply during the guarantee period you select and decline each year. According to the product guide, the three-year term charges 9, 8, and 7 percent in policy years one through three. The five-year term charges 9, 8, 7, 6, and 5 percent in years one through five. The seven-year term charges 9, 8, 7, 6, 5, 4, and 3 percent in years one through seven. Once the guarantee period ends, the surrender charge drops to zero. Charges may vary by state.
The charge is applied as a percentage of the accumulation value surrendered; withdrawals within the yearly penalty-free amount are not charged. A full surrender returns the accumulation value, less the applicable surrender charge, plus or minus any market value adjustment, less any applicable premium tax. To understand why insurers use these schedules, see annuity surrender charges explained.
A 9 percent first-year charge is a meaningful penalty, especially on the three-year term, where the schedule stays at 7 percent or more for the full guarantee period. That does not make RateLock a poor choice, but it does mean the contract rewards buyers who are confident the funds can stay put until the term ends. If there is a real chance you will need the funds early, compare RateLock’s schedule with contracts that use lower or faster-declining charges, and weigh the difference in surrender terms against any difference in rate.
How the Market Value Adjustment Works
RateLock includes a market value adjustment during the surrender charge period. The MVA applies to the portion of the accumulation value withdrawn or applied to an annuity option that exceeds the penalty-free amount, in addition to any surrender charge. It ends when the surrender charge period ends, does not apply at death, and may differ by state. For the general concept, see what a market value adjustment is.
The adjustment can work in either direction. Generally, if interest rates have risen since the contract was issued, the MVA reduces the surrender value; if rates have fallen, it increases the surrender value. According to the product guide, an increase from the MVA cannot exceed the amount of the surrender charge, which limits how much an owner can gain from falling rates.
RateLock’s MVA is tied to the yield of Bloomberg’s US Credit Index. The formula compares the index rate on the business day before the issue date with the index rate on the business day before the withdrawal, and it compounds the rate difference over the time remaining in the surrender charge period. A large rate increase early in a long term produces the biggest reduction, while the same change late in the term has less effect. Because the MVA is applied in addition to the surrender charge, an early surrender in a rising rate environment can cost noticeably more than the surrender charge alone.
Want to compare RateLock’s surrender terms with other MYGAs?
Compare MYGA Options
Waivers for Nursing Care, Home Health Care, and Terminal Illness
RateLock includes three waiver of surrender charge riders at no additional cost: one for nursing care confinement, one for home health care, and one for terminal illness. When a waiver applies, both the surrender charge and the applicable market value adjustment may be waived, giving the owner access to the accumulation value during a health crisis without the usual penalties. Waiver riders may vary by state and may not be available everywhere.
The confinement waiver can apply when the owner has been confined to a qualified institution for at least 30 consecutive days at any time after issue. The home health care waiver can apply when the owner requires home health care from a licensed agency because the owner needs help with two or more daily living activities named in the rider: bathing, dressing, transferring, toileting, continence, and eating. The terminal illness waiver can apply when the owner is diagnosed with a terminal illness on or after the policy date that results in a life expectancy of 12 months or less.
These waivers do not turn a MYGA into long-term care insurance. They provide access to your own money rather than an additional benefit. Still, for a retiree concerned about the cost of care, knowing that a qualifying nursing home stay or terminal diagnosis may not trigger a surrender charge on funds held in RateLock adds meaningful flexibility. Using annuities as a long-term care alternative is another way to plan for care costs.
Who Qualifies for the Waivers
Each waiver has conditions, and they are worth reading carefully before you count on them. According to the product guide, to qualify for any waiver the policy owner must be a natural person, not a trust, corporation, or other legal entity, and must have owned the policy continuously since the policy date. The waiver riders end upon policy termination, annuitization, or a change of ownership.
The confinement waiver requires that the owner was not confined within one year before the policy date, and written notice with proof of confinement must reach the home office within one year of the confinement. The home health care waiver requires that services begin at least one year after the policy date, that the owner was not confined or receiving home health care during the year before the policy date, and that notice with proof is received within one year of the services. The terminal illness waiver requires a certificate from the attending physician stating the owner’s life expectancy, and the physician cannot be the owner, a family member, or someone with a financial or business relationship to the owner.
These conditions have practical implications. A trust-owned contract would not qualify, which matters for buyers who plan to hold annuities in a revocable trust. A change of ownership after purchase would end the waivers. And someone already receiving care when they buy would generally not qualify for the related waiver. If the waivers are important to your planning, structure ownership with them in mind from the start.
Death Benefit and Beneficiary Options
If the owner dies before the maturity date and before annuity payments begin, RateLock pays the accumulation value as of the date proof of death is received. Neither the surrender charge nor the MVA applies in that case, so beneficiaries receive the full accumulation value.
Beneficiaries have choices in how they receive the money. According to the product guide, a beneficiary may take the death benefit under an annuity option over a period not exceeding the beneficiary’s life expectancy, or as a lump sum at any time within five years of the owner’s death. A spouse who is the beneficiary may instead continue the policy as the new owner. With joint owners, the first death of a joint owner is treated as the death of the owner. If the owner is a trust or other non-natural person, the death of the primary annuitant triggers the death benefit. Before maturity, if the annuitant dies, the owner may generally name a new annuitant.
Once annuity payments are underway, any remaining benefit at the owner’s death goes to the beneficiary under the annuity option in effect. Tax rules apply to the earnings portion of any death benefit, and inherited annuity distribution rules can be complex, so beneficiaries should review their options carefully. Naming beneficiaries clearly at purchase, and reviewing those designations after major life events, helps ensure the death benefit goes where you intend.
What Happens When the Guarantee Period Ends
RateLock includes a Guaranteed Period Renewal Option Endorsement, which gives you a set of choices each time a guarantee period ends. According to the product guide, you receive a notice about 30 days before the end of the period that outlines the available options and the interest rates attached to them, and you have until the end of the guarantee period to decide.
You can elect a new guaranteed period at the rates then being offered, which starts a new surrender charge schedule and, where applicable, a new MVA period. You can move to a one-year annually declared rate option, which carries no surrender charge or MVA and lets you reevaluate each year. You can withdraw part or all of the money with no surrender charge or MVA. Or you can convert the value to a guaranteed income stream by annuitizing.
If you make no election, the contract does not lock you into a new multi-year term. After a 30-day grace period, the money moves automatically to the one-year annually declared rate option. That default protects owners who miss the renewal notice from being committed to a new surrender schedule without meaning to be, but it also means the money may earn a lower declared rate than a new multi-year guarantee would pay. Mark the end date of your guarantee period on a calendar and review the renewal rates, along with competing MYGA rates, before the window closes. Renewal terms can also be limited at older ages so the new period does not run past the contract’s maturity age.
Annuitization and Income Options
RateLock can also become a source of guaranteed income. According to the product guide, the policy may be annuitized after policy year five or at the end of any guaranteed period without surrender charges. If annuitization occurs during the surrender charge period, the market value adjustment may apply to amounts above the penalty-free amount.
The income options listed are Life Income Only, which pays for the annuitant’s life with no guaranteed number of payments; Life Annuity with Installment Payments, which pays for life or a selected number of payments, whichever is longer, similar to a life with period certain annuity; and Life Income with Installment Refund, which pays for life or until total payments equal the amount applied, whichever is longer. A standalone period certain option is not listed, and if no option is selected, the default is life income with five years of guaranteed payments. Once fixed annuity payments begin, they cannot be changed.
One detail deserves attention. The product guide states that annuity payments under these options are based on the guaranteed minimum interest rate provided when the policy was purchased. Contract annuitization rates built on a guaranteed minimum can be lower than what a new immediate annuity might pay at the time you want income. If income is the plan once the term ends, compare RateLock’s annuitization payout with current immediate annuity quotes before deciding.
Maturity Age and Long-Term Planning
Every deferred annuity has a maturity date, the point at which payments are required to begin under an annuity payout option. For RateLock, the default maturity date is the policy anniversary nearest the owner’s 95th birthday, and it may vary by state. The owner may choose an earlier or later maturity date by written notice at least 30 days before the intended date, up to the policy anniversary following the owner’s 105th birthday. If you extend the maturity date, any active riders must allow the same extension.
For most buyers, maturity is far in the future and rarely affects day-to-day decisions. It matters more for older buyers. A 90-year-old buying a seven-year term would reach the default maturity age of 95 before that term ends, so the maturity date would need to be extended or the term chosen with that date in mind, and renewal choices may be limited so a new term does not extend past maturity. Confirm which terms are available at older ages before applying. Planning for what happens at maturity, whether that means taking a lump sum, choosing an income option, or extending the date, avoids an automatic outcome you did not intend.
Maturity also interacts with estate planning. If the goal is to leave the money to heirs rather than to draw income, the death benefit and beneficiary options described above, along with the ability to extend maturity, help keep the contract in accumulation for longer. Reviewing these dates with family members or an estate attorney can make the transition smoother for everyone involved.
How RateLock Is Taxed
Like other deferred annuities, RateLock grows tax deferred. Interest is not taxed each year while it remains in the contract, so it compounds without annual taxation until withdrawn. That can be a meaningful advantage over a CD or savings account, where interest is generally taxable as it is earned.
With a nonqualified RateLock, the IRS treats withdrawals as earnings until all the gain has come out, and that gain is taxed at ordinary income rates. Once earnings have been withdrawn, the remaining amounts are a return of your original premium. The rules are covered in more depth under non-qualified annuity taxation. For a qualified contract, such as a Traditional IRA, withdrawals are generally fully taxable, while qualified distributions from a Roth IRA can be tax free.
Age matters too. On top of income tax, the IRS may add a 10 percent penalty to the taxable part of withdrawals made under age 59 and a half, unless an exception applies. Since issue ages start at 0, younger owners may hold RateLock well before age 59 and a half. The exceptions and details are explained in our look at the IRS early withdrawal penalty. Ameritas notes that it does not provide tax advice, so consult a tax professional about your situation.
What RateLock Does Not Include
Knowing what a contract leaves out is as important as knowing what it includes. RateLock does not allow additional premiums after issue, so it is not suited to someone who wants to add money over time. It does not accept non-spousal inherited annuities. And it offers a single guarantee period per contract, so you cannot split one premium across several terms within the same policy.
The product materials we reviewed also do not describe an annuity bail-out provision, a feature some fixed annuities use to lift surrender charges when a renewal rate drops under a stated threshold. Because RateLock guarantees its rate for the full term you choose, the bail-out question matters mainly at renewal, when you can move to the one-year declared rate or withdraw without charges anyway.
Finally, RateLock is a fixed annuity with no index-linked crediting, and the product guide lists no optional income rider. It is designed for guaranteed growth over a set period, not for market-linked upside or lifetime withdrawal guarantees. If you want those features, an indexed annuity paired with a lifetime income benefit may fit better, although it will come with its own complexities and trade-offs. Being clear about what you want the money to do makes it easier to judge whether a simple guaranteed rate is the right tool.
Not sure which term or carrier fits your plan?
Talk Through My Options
Using RateLock in a MYGA Ladder
Because RateLock offers three guarantee periods, it can serve as one or more rungs in a fixed annuity ladder. A ladder splits money across several contracts with different guarantee-period end dates, so a portion becomes available every few years. That provides regular access without paying surrender charges and lets you reinvest at whatever rates prevail when each rung matures. Our guide to a fixed annuity ladder strategy explains how to build one.
A simple example would place part of a sum in a three-year RateLock, part in a five-year, and part in a seven-year. As each contract reaches the end of its term, the owner can renew, move to the one-year declared rate, withdraw the money, or annuitize, depending on needs and rates at that time. Each RateLock in the ladder would also keep its own 10 percent yearly penalty-free allowance and its own waivers.
Two RateLock features shape how a ladder should be built. First, each contract requires a separate premium of at least $10,000, and the rate band depends on each contract’s size, so splitting money into smaller pieces may drop some rungs below the $100,000 band. Second, rates for each term may not rise with length, so a ladder built from more than one carrier can sometimes capture better rates for each rung. Comparing across carriers before setting up the ladder helps each piece earn a competitive rate.
How RateLock Compares With Other MYGAs
RateLock competes in a crowded market of multi-year guaranteed annuities. Most MYGAs share the same basic design, so the meaningful differences come down to a handful of factors: the rate for each term and premium band, the strength of the issuing insurer, the surrender charge schedule, the penalty-free withdrawal terms, the waivers included, the market value adjustment, and what happens at the end of the term.
RateLock’s strengths include its 60-day rate lock with a higher-of comparison, an A (Excellent) AM Best rating for the issuer, a 10 percent yearly penalty-free withdrawal with no MVA, three waiver riders at no cost, a death benefit with no surrender charge or MVA, and a default to a one-year declared rate rather than an automatic new multi-year term. Its trade-offs include a 9 percent first-year surrender charge, an MVA during the surrender period, a single premium with no additions, and annuitization rates based on the guaranteed minimum.
Rates change frequently, and the best-paying MYGA for a given term and deposit can shift from one month to the next. Our page on the best MYGA annuity rates shows how competing contracts compare. The right comparison weighs the rate against the insurer’s strength and the contract terms, because a slightly higher rate from a weaker insurer, or with harsher surrender terms, is not always the better deal.
Who RateLock Fits and Who Should Look Elsewhere
RateLock may fit savers who want a guaranteed rate for three, five, or seven years from a highly rated insurer, who can commit the funds through the end of the term, and who value the protection of a rate lock while a transfer or exchange is in process. It may suit retirees moving money from maturing CDs or other annuities, IRA owners who want guaranteed growth for part of their savings, and buyers with $100,000 or more who can take advantage of the higher rate band.
It also suits buyers who appreciate built-in waivers for nursing care, home health care, and terminal illness, and who want their beneficiaries to receive the full accumulation value without surrender charges or an MVA. Because issue ages run through 90, it is available to many older buyers who are shut out of contracts with lower maximum ages.
Others should look elsewhere. Anyone who may need more than 10 percent of the money in a given year during the guarantee period should weigh the 9 percent first-year charge and the MVA carefully. Buyers who want to add money over time, who are funding the contract with a non-spousal inherited annuity, or who plan to hold it in a trust and rely on the waivers will find limits here. And buyers who want market-linked growth or a lifetime income rider should consider other annuity types.
How Our Office Helps
Our first step is learning the job this money has to do and the timeline for it. That includes how long you can commit the funds, whether you expect to need withdrawals, where the money is coming from, and how this purchase fits with the rest of your retirement savings. Those answers point to the right term and help decide whether a MYGA is the right tool at all.
If RateLock is a candidate, we compare its current rates for your term and premium band with other multi-year guaranteed annuities, along with each insurer’s financial strength, surrender schedule, withdrawal terms, and waivers. We explain the rate lock, the MVA, and the renewal options in plain language, so you know what to expect at every stage of the contract.
When you decide, we help with the application and coordinate any transfer, rollover, or 1035 exchange so the funds arrive within the 60-day rate lock window when possible. As the end of your guarantee period approaches, we can review the renewal options with you and compare them with current MYGA rates elsewhere. As an independent office, we base our recommendation on your goals and the numbers rather than on any single carrier’s lineup.
Ready to lock in a guaranteed rate?
Start My RateLock Quote
Financial Protection Essentials
More reading for savers who want guaranteed, predictable growth.
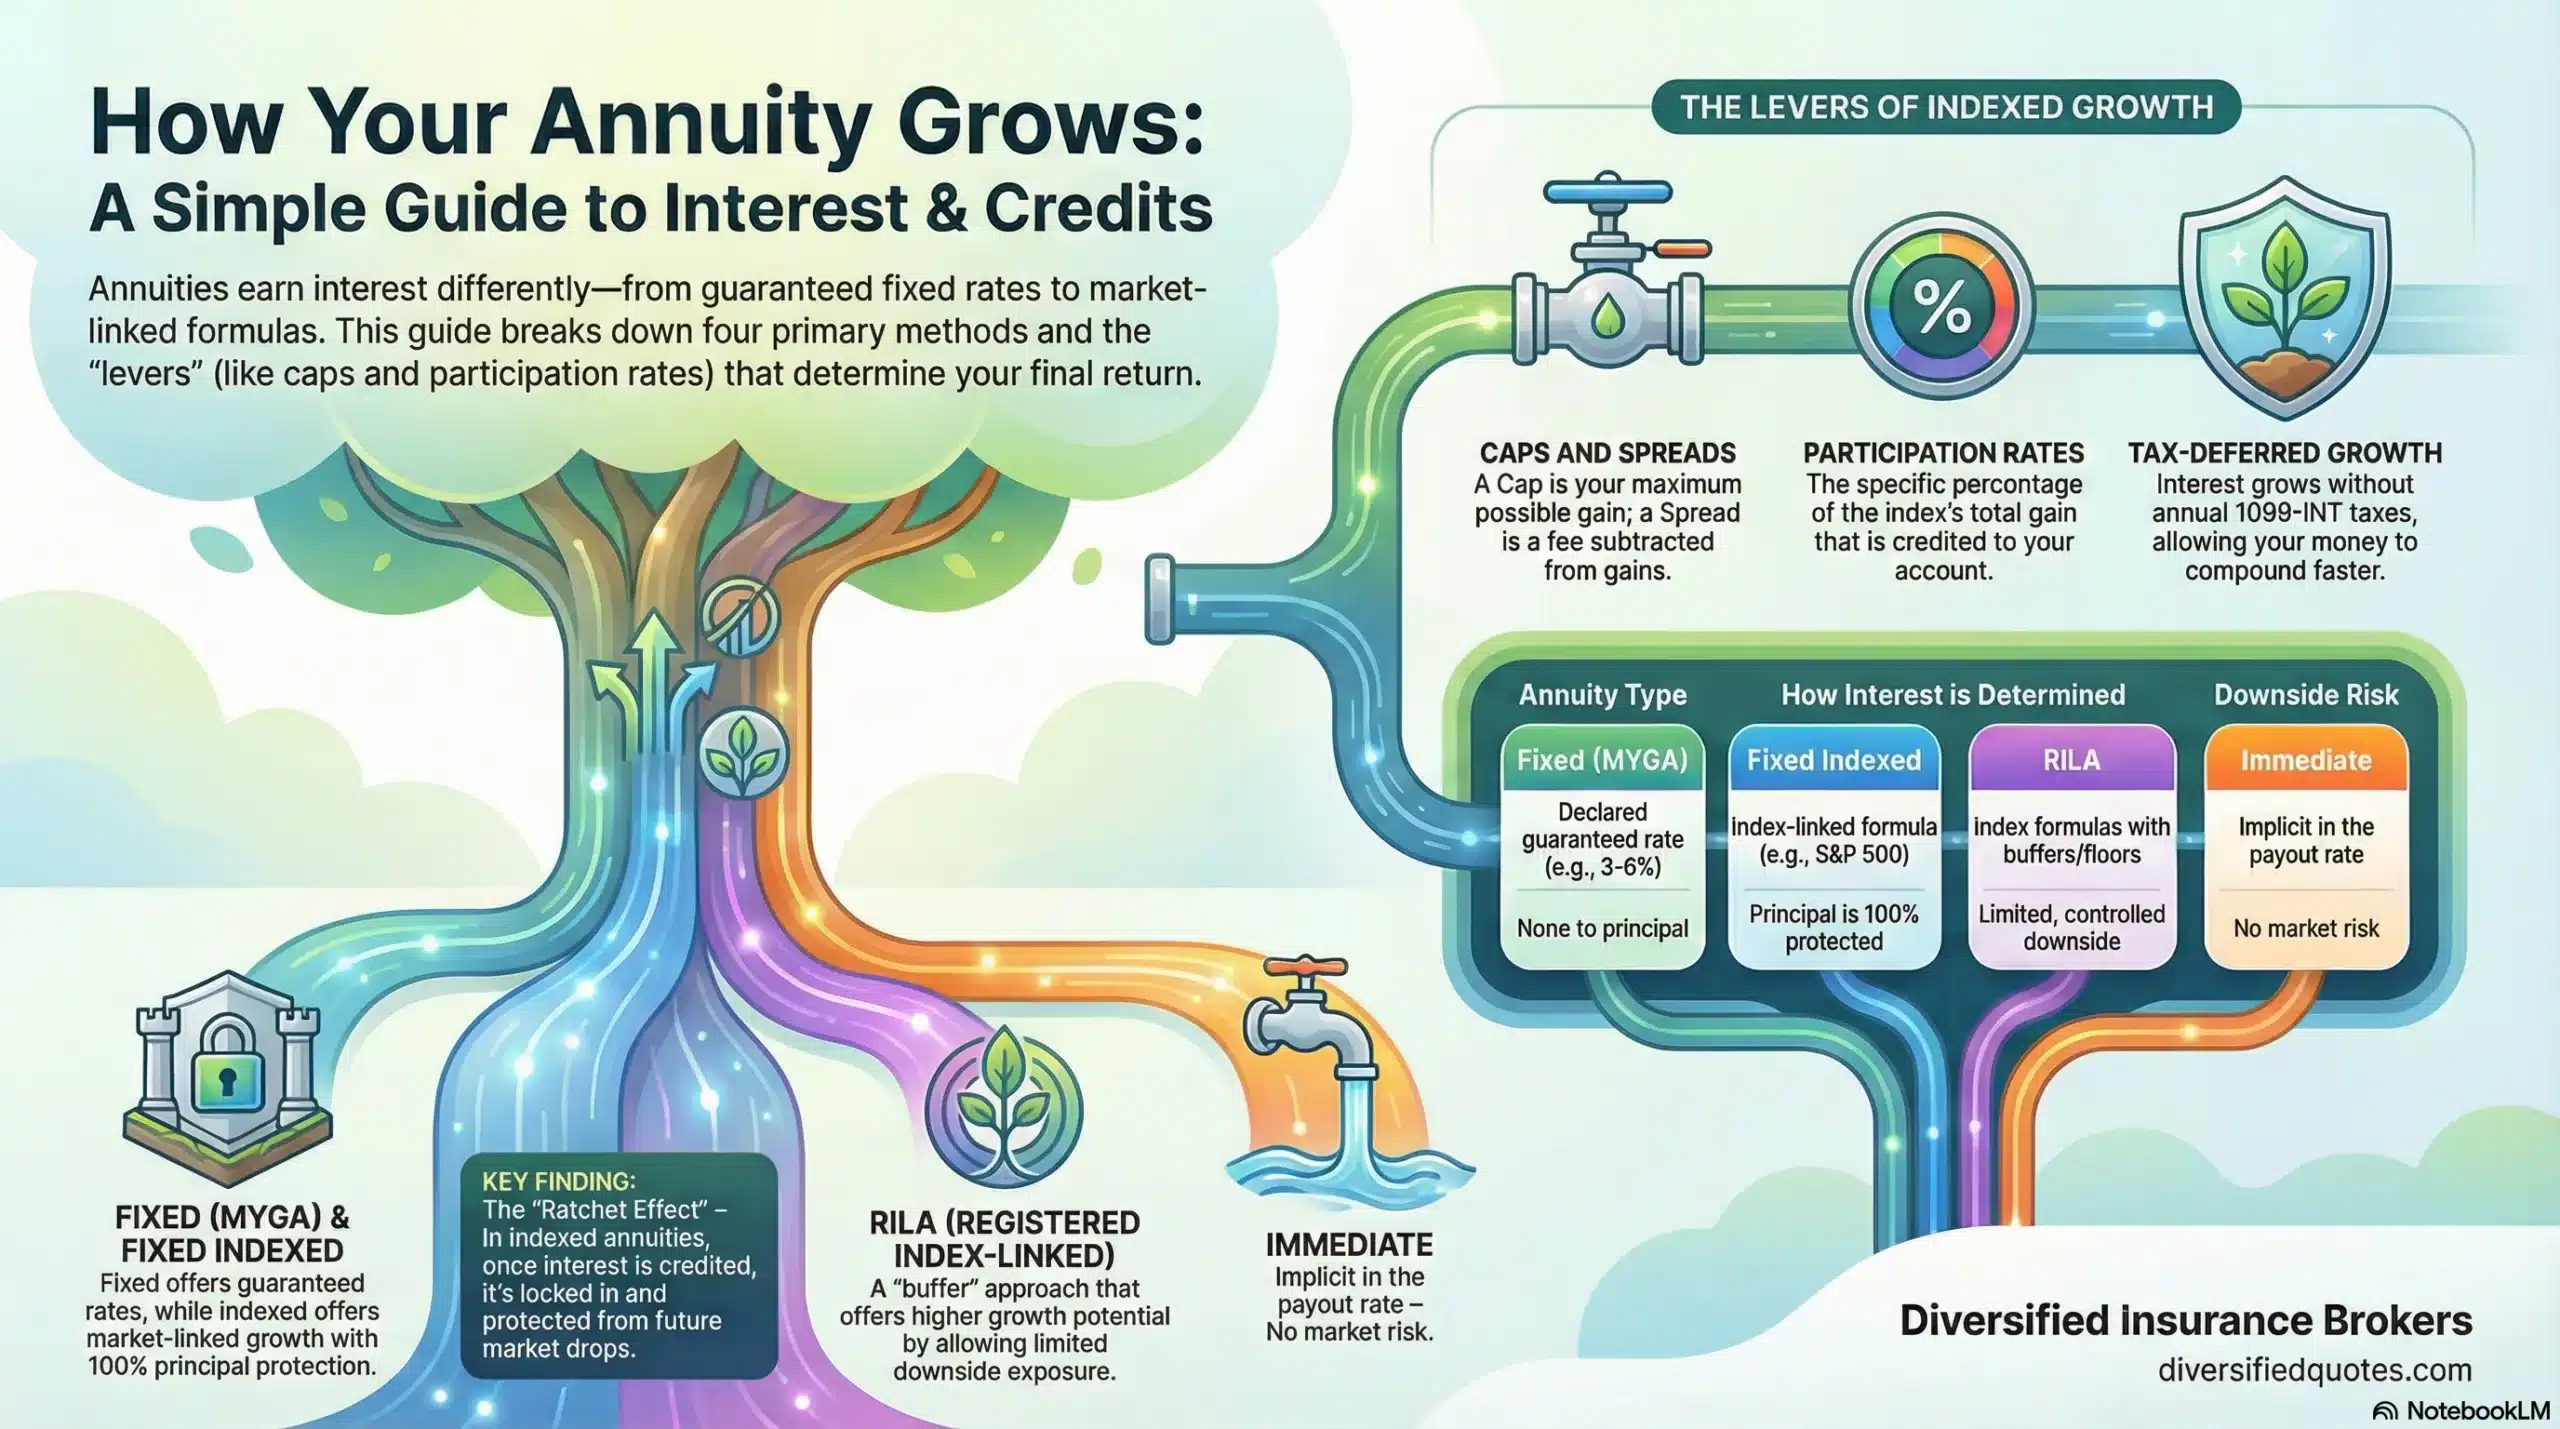
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
How does the RateLock 60-day rate lock work?
If your premium arrives within 60 days after the application date, Ameritas compares the rate in effect on the application date with the rate on the day the money is received and applies the higher one. After 60 days, the funds receive the rate in effect on the date they arrive.
Is the Ameritas RateLock MYGA FDIC insured?
No. RateLock is an insurance contract, not a bank deposit, so FDIC coverage does not apply. Its promises rest on Ameritas Life Insurance Corp.’s ability to pay claims. Read more about whether annuities are FDIC insured.
What protects my money if the insurer fails?
If an insurer is placed in liquidation, the life and health guaranty association in your state of residence generally covers annuity values up to a limit set by that state. Limits vary by state. Learn how your state guaranty association coverage works.
Can I move my IRA or 401(k) into RateLock?
Yes. RateLock accepts Traditional, Roth, SEP, and SIMPLE IRAs as well as pension, profit sharing, 401(k), and 457 money, subject to plan rules. A direct transfer or direct rollover keeps the money tax deferred. See how to transfer a retirement account into an annuity.
How are RateLock withdrawals taxed?
With nonqualified money, gains are withdrawn first and taxed at ordinary income rates, and the IRS may add a 10 percent penalty under age 59 and a half. Interest is not taxed until withdrawn. The basics of how annuities are taxed apply here too.
How is RateLock taxed inside an IRA?
Inside an IRA, RateLock follows the account’s tax rules. Traditional IRA withdrawals are generally fully taxable, required minimum distributions apply, and qualified Roth distributions can be tax free. Read about qualified annuity taxation for details.
What do my beneficiaries receive from RateLock?
When the owner passes away before income payments start, beneficiaries get the accumulation value without surrender charges or an MVA. They can take a lump sum within five years or an annuity option, and a spouse may continue the contract. See what beneficiaries receive from annuities.
Is the RateLock death benefit taxable to heirs?
The earnings portion is generally taxable as ordinary income to beneficiaries, and pre-tax qualified money, such as a Traditional IRA, is generally fully taxable, while inherited Roth money is generally tax free if the five-year rule is met. Unlike stocks or real estate, annuity gains carry no basis step-up when the owner dies. Find out more about whether annuity death benefits are taxable.
Should I choose RateLock or a fixed indexed annuity?
RateLock offers a known rate for a set term with no market link. A fixed indexed annuity offers index-linked growth potential with caps or participation rates and often longer surrender periods. Compare fixed versus fixed indexed annuities to decide.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to MYGA Reviews: American Gulf to Global Atlantic — covering MYGA product reviews from American Gulf, Athene, Corebridge, Global Atlantic & more from 100+ carriers.
Last Reviewed: November 13, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
