
Americo Liberty Mark Freedom Fixed Indexed Annuity
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Americo Liberty Mark Freedom Fixed Indexed Annuity
LibertyMark Freedom, issued by Americo Financial, stands out among fixed indexed annuities for a feature few competitors match at its price: an optional enhanced death benefit rider that grows the amount your beneficiaries receive by 8 percent simple interest on your premium each year for up to 15 years, topping out at 220 percent of the premium and paid in a single sum with no waiting period and no medical underwriting, for an annual charge of 0.15 percent. The base contract carries no mandatory fees, protects principal from index losses, and offers a range of index options, but it is that legacy feature that makes LibertyMark Freedom a planning tool rather than just another accumulation annuity. Everything else on this page sits on top of that.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and LibertyMark Freedom is an annuity our office places regularly, especially for clients who want to leave more to heirs and for those who cannot qualify for life insurance. As an independent annuity broker, our office compares it with other carriers’ contracts and shows you, in plain numbers, when its strengths fit your goals and when another product would serve you better.
Want to see what LibertyMark Freedom could leave your beneficiaries?
Get My LibertyMark Freedom Quote
LibertyMark Freedom at a Glance
| Feature | Details |
|---|---|
| Issuer | Americo Financial Life and Annuity Insurance Company, Kansas City, Missouri; AM Best A (Excellent) |
| Product Type | Single premium deferred fixed indexed annuity |
| Versions | Freedom 7, Freedom 10, and Freedom 10 LT, with California variations |
| Issue Ages | 0 to 85; enhanced death benefit rider through age 75 |
| Minimum Premium | $10,000, qualified or non-qualified |
| Annual Withdrawal Allowance | Up to 10% of accumulation value each year after the first; see annuity free withdrawal rules |
| Market Value Adjustment | Applies during the surrender period; see surrender charges and MVA |
| Crediting Options | A Declared Interest Option plus eight index options, each fee-free or with a 1% buy-up |
| Guaranteed Minimum Value | 87.5% of premium, less withdrawals and premium tax, plus a guaranteed interest rate set at issue |
| Standard Death Benefit | Greater of accumulation value or guaranteed minimum value, including partial-year index credits |
| Optional Enhanced Death Benefit | 8% simple roll-up for up to 15 years to 220% of premium; 0.15% annual charge; not available in California |
| Availability and Suitability | All states and the District of Columbia except New York; versions vary by state |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Who Issues LibertyMark Freedom
LibertyMark Freedom is issued by Americo Financial Life and Annuity Insurance Company, the main life and annuity company within the Americo Life, Inc. family of insurers, based in Kansas City, Missouri. AM Best rates Americo Financial Life and Annuity A (Excellent), the third-highest of its fifteen rating categories, and the company is authorized to do business in the District of Columbia and every state except New York. Our overview of Americo company review covers its history, ownership, and product lineup in more detail.
Americo is privately held, and its family of companies has operated for more than a century. Its product line spans fixed indexed annuities, multi-year guaranteed annuities, final expense, and other life insurance. Americo’s own retirement solutions page describes its annuity lineup, which includes both fixed indexed and multi-year guaranteed contracts. LibertyMark Freedom is one of several fixed indexed annuities issued by Americo and sold through independent agents, which is why you will not find it available for direct purchase from the carrier.
Financial strength matters with any annuity, because the guarantees, including the guaranteed minimum value and the enhanced death benefit, depend on the issuing company’s ability to pay. An A (Excellent) rating reflects a strong ability to meet ongoing obligations. It is a step below the A+ and A++ ratings held by some of the largest carriers, which is worth weighing alongside the product’s features.
Each state also maintains a guaranty association that protects annuity owners up to limits that vary by state. That protection should be viewed as a backstop rather than a reason to choose a weaker carrier, and our office considers ratings, size, and product features together when recommending any contract.
Choosing a Version: Freedom 7, Freedom 10, and Freedom 10 LT
LibertyMark Freedom comes in three main versions that differ primarily in the length and shape of the surrender schedule. Freedom 7 has a seven-year surrender period. Freedom 10 and Freedom 10 LT each have ten-year surrender periods, with different charge schedules, and a California version of the 10 LT runs nine years. All versions are available for issue ages 0 through 85, though availability of each version varies by state.
The trade-off is familiar to anyone who has compared annuities. A longer surrender period generally supports higher caps and participation rates, because the insurer can invest the premium for a longer period with less risk of early withdrawal. A shorter period offers more flexibility in exchange for somewhat lower crediting rates. Current rates for each version are declared by Americo and can change, so the comparison should be run with the rates in effect when you apply.
Which ten-year version you can buy depends largely on where you live, because Americo offers Freedom 10 in some states and Freedom 10 LT in others. The difference is the surrender schedule. Freedom 10 starts with higher charges, beginning at 12 percent, while Freedom 10 LT starts lower, at 9.2 percent, and declines steadily. In recent rate sheets the two ten-year versions have shared the same declared crediting rates, so the schedule, not the growth potential, is usually what separates them.
The contract accepts both non-qualified money and qualified money, including traditional, Roth, SEP, and inherited IRAs, and certain 403(b) transfers. The minimum premium is $10,000, and larger amounts may require home office approval above set limits. Our office matches the version to your time horizon, the source of the money, and the state where you live.
Surrender Charges and the Market Value Adjustment
Like all deferred annuities with a surrender period, LibertyMark Freedom charges a percentage of any amount withdrawn above the penalty-free allowance, or surrendered entirely, during the surrender period. The charges decline each year until they reach zero. Schedules like these are compared across carriers in our article on how surrender charges work. The schedules for each version are shown below.
| Version | Surrender Period | Charge by Contract Year |
|---|---|---|
| LibertyMark Freedom 7 | 7 years | 9%, 8.5%, 8%, 7%, 6%, 5%, 4%, then 0% |
| LibertyMark Freedom 7 (California) | 7 years | 8.3%, 8.2%, 7.2%, 6.2%, 5.2%, 4.2%, 3.1%, then 0% |
| LibertyMark Freedom 10 | 10 years | 12%, 11.5%, 11%, 10.5%, 10%, 9%, 8%, 7%, 6%, 5%, then 0% |
| LibertyMark Freedom 10 LT | 10 years | 9.2%, 9.2%, 8.2%, 7.2%, 6.2%, 5.2%, 4.2%, 3.1%, 2.1%, 1%, then 0% |
| LibertyMark Freedom 10 LT (California) | 9 years | 8.3%, 8.2%, 7.2%, 6.2%, 5.2%, 4.2%, 3.1%, 2.1%, 1%, then 0% |
A market value adjustment also applies during the period shown in the contract. The adjustment is based on changes in Treasury Constant Maturity rates published by the Federal Reserve between the date the contract was issued and the date of a withdrawal or surrender. If rates have fallen, the adjustment increases the amount received; if rates have risen, it decreases it. The adjustment does not apply to death benefits, does not apply when the guaranteed minimum value is higher than the contract value after surrender charges, and does not apply to withdrawals under the confinement waiver.
The practical lesson is simple: money placed in LibertyMark Freedom should be money you expect to leave in place for the full surrender period, apart from the annual penalty-free amount. Our office reviews your other savings and liquidity needs before recommending a version, so the surrender schedule fits your plans rather than working against them.
Access to Your Money: Withdrawals, Confinement, and Annuitization
LibertyMark Freedom is designed to grow over the long term, but it includes several ways to reach your money. Beginning in the second contract year, you may withdraw up to 10 percent of the accumulation value each year without surrender charges. Each withdrawal must be at least $500, and the surrender value must remain at least $2,000. Withdrawals are taken first from the Declared Interest Option and then from the index options, which matters when index terms have not yet ended.
The contract also includes a confinement waiver in most states. If, after the contract date, you are confined to a nursing home or hospital for at least 90 consecutive days, you may withdraw up to 100 percent of the accumulation value without surrender charges. The request and proof of confinement must be submitted no later than 30 days after discharge. The waiver is not available in Massachusetts. Our page on the annuities with nursing home provisions compares how waivers like this differ from carrier to carrier.
Required minimum distributions from IRA-funded contracts are generally accommodated as well, under the company’s current practice, though owners should confirm how a required distribution in the first contract year will be handled.
For those who want income, the contract can be annuitized at any time. Two payout options are offered: a lifetime option that pays for the longer of the annuitant’s life or a fixed period, and a fixed period option that pays for at least 60 months or the annuitant’s life expectancy, if shorter. LibertyMark Freedom does not offer a guaranteed lifetime withdrawal rider, so annuitization is its path to guaranteed income. That is an important distinction for anyone whose primary goal is income, discussed later on this page.
How Interest Is Credited
LibertyMark Freedom offers up to nine interest crediting options at a time: a Declared Interest Option and as many as eight index options. You can divide your premium among them and, at the end of each option’s term, which is either one or two years, move money to a different option. That flexibility allows you to adjust as markets and your goals change.
The Declared Interest Option pays a fixed rate guaranteed for a one-year term, credited daily rather than at the end of the period. Because withdrawals are taken from this option first and its interest is credited daily, it is a sensible place for money you may need to withdraw during the year. Its rate is declared by Americo and can change at each renewal, subject to a guaranteed minimum.
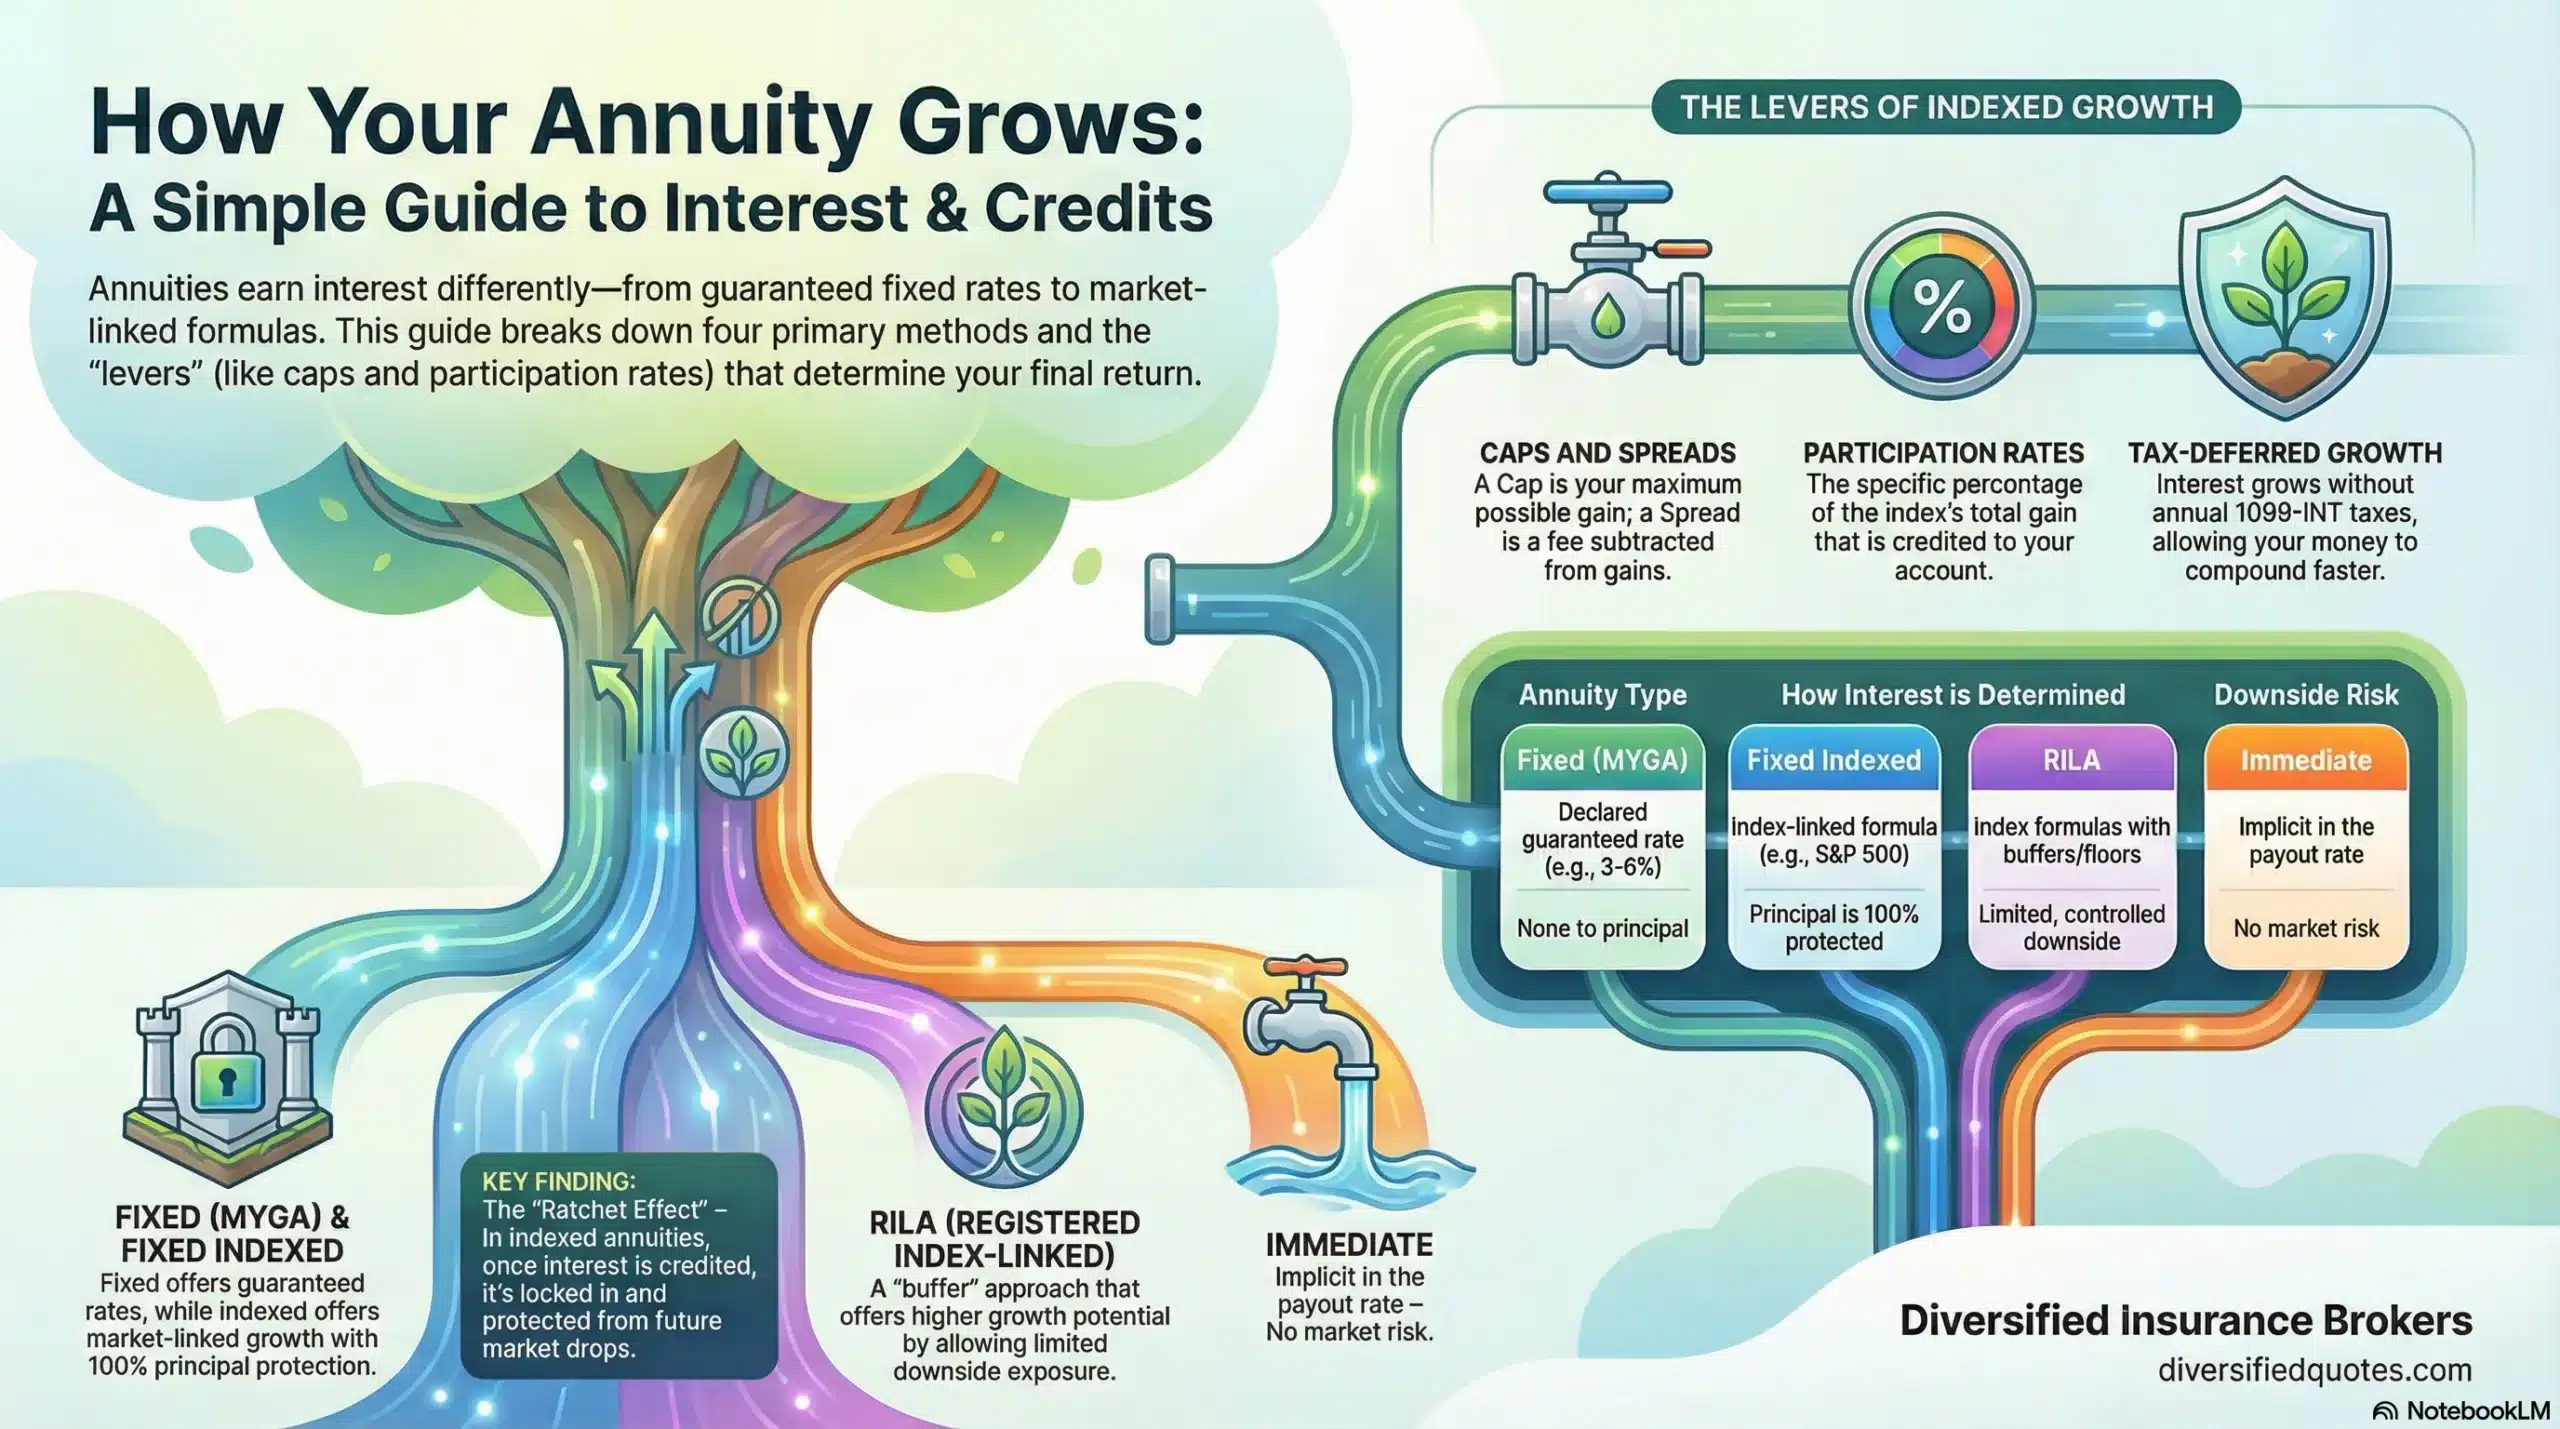
Index options credit interest based on the change in a market index over the term, subject to a cap or a participation rate. Interest is locked in at the end of each term and is never less than zero, so a down market produces no credit rather than a loss. Your money is not invested directly in the market, and S&P 500 credits are based on price changes, not dividends. The trade-off for that protection is that your share of index gains is limited.
Choosing among options is one of the most important decisions an owner makes, and the right mix depends on your outlook and comfort with variability. Our guide on choosing the correct indexes in an annuity walks through how to think about that allocation.
The Index Options
LibertyMark Freedom offers four underlying indexes, each available with different crediting methods. The S&P 500 is the familiar benchmark of large-company U.S. stocks and is offered as a one-year point-to-point option with a cap and a two-year point-to-point option with a participation rate.
The S&P 500 IQ Index, also known as the S&P 500 IQ 0.5% Decrement Index, provides exposure to the S&P 500 with an intraday volatility control that targets 15 percent volatility. It measures volatility over a short window during the trading day and rebalances the same day. Its published values are reduced by a fixed 0.5 percent decrement, which is the cost of that more stable pricing. It is available as a one-year option with either a cap or a participation rate.
The SG Columbia Adaptive Risk Allocation Index, a collaboration between Société Générale and Columbia Threadneedle, combines a globally diversified mix of assets with a 5 percent volatility control and an allocation model that adjusts risk to market conditions. The SG Lead Asset Select Exposure Rotation Index, called the SG Laser Index, covers U.S. stocks, U.S. government bonds, and commodities, uses a lead asset method to judge the market’s phase, and applies a 5 percent volatility control. Both SG indexes are offered as one-year and two-year point-to-point options with participation rates, and both deduct a 0.50 percent annual maintenance fee plus transaction and replication costs in calculating their values.
Volatility-controlled indexes tend to support higher participation rates because their returns move within a narrower range. That does not make them better or worse than the S&P 500, only different, and many owners split their premium between a traditional index and a controlled one.
Caps, Participation Rates, and Guaranteed Minimums
Each index option limits your share of index gains through either a cap or a participation rate. A cap is the maximum interest that can be credited for the term. If the index rises more than the cap, you receive the cap; if it rises less, you receive the full increase; if it falls, you receive zero. Our explanation of what an annuity cap rate is covers the concept in more detail.
A participation rate credits a percentage of the index gain. With a 60 percent participation rate and a 10 percent index increase, for example, the credit would be 6 percent. Participation rates above 100 percent are possible on volatility-controlled indexes, where the index itself moves less.
Caps and participation rates are declared by Americo and can change at the start of each index term. LibertyMark Freedom guarantees that caps will never fall below 1 percent and participation rates will never fall below 5 percent for any index option. Those minimums are low, which is typical for the industry, so the renewal history of a carrier matters as much as the starting rates. Our article on whether fixed indexed annuity rates change explains why renewal rates deserve attention.
Because current rates change with interest rates and market conditions, this page does not list them. Our office provides the rates in effect at the time you apply and compares them with competing contracts, so you can judge the starting position and the guarantees side by side.
Standard and Buy-Up Index Options
One of LibertyMark Freedom’s distinctive features is that every index option is available in two forms. The standard form carries no fee. The buy-up form costs 1 percent of the amount allocated each year and, in exchange, provides a higher cap or participation rate. You can split money between standard and buy-up options and change the mix at the end of each index term.
The buy-up math is easy to evaluate. The higher cap or participation rate only pays off when the index rises enough for the improvement to exceed the 1 percent cost. In flat or down years, the buy-up costs 1 percent while the standard option costs nothing, so the buy-up can reduce your accumulation value in a year when the index credits zero. In strong years, the higher cap or participation rate can more than make up for the fee.
The decision depends on expectations and temperament. An owner who values the certainty of never losing value in a down year will usually favor the standard options. An owner with a longer horizon who is comfortable with an occasional small reduction in exchange for higher upside may allocate part of the contract to buy-up options. Splitting the allocation is a common middle ground.
The base contract itself carries no mandatory fees. The only charges an owner pays are those chosen deliberately: buy-up options, if selected, and the enhanced death benefit rider, if elected. That transparency is one of the product’s strengths.
The Guaranteed Minimum Value
LibertyMark Freedom includes a built-in floor called the guaranteed minimum value. Upon full surrender, death, or annuitization, you are guaranteed to receive no less than 87.5 percent of your premium, minus any gross withdrawals and applicable premium tax, accumulated at the guaranteed minimum value interest rate shown on your contract. That rate is set when the contract is issued and does not change for the life of the contract.
The guaranteed minimum value exists for situations where the accumulation value, after surrender charges, would otherwise fall below a reasonable floor, such as a full surrender in the early years after several years of zero index credits. It is a safety net rather than a growth expectation. For most owners who hold the contract through the surrender period, the accumulation value will exceed the guaranteed minimum value.
The guaranteed minimum value also interacts with other features. The market value adjustment does not apply when the guaranteed minimum value is higher than the contract value after surrender charges, and the standard death benefit is the greater of the accumulation value and the guaranteed minimum value.
Guarantees such as this one depend on the claims-paying ability of the issuing company, which is why carrier strength remains part of the evaluation. Taken together, the zero floor on index credits and the guaranteed minimum value give LibertyMark Freedom the principal protection that makes fixed indexed annuities appealing to conservative savers.
Want current LibertyMark Freedom rates for your state and version?
Request Current Rates
The Standard Death Benefit
Every LibertyMark Freedom contract includes a death benefit at no additional cost. If the owner dies before annuity payments begin, beneficiaries receive the greater of the accumulation value or the guaranteed minimum value, reduced by any applicable premium tax. Surrender charges and the market value adjustment do not reduce the death benefit, so beneficiaries are not penalized because death occurred during the surrender period.
The contract also credits partial-year index gains at death. If the owner dies partway through an index term, the death benefit includes any index growth since the last contract anniversary rather than ignoring it. Many fixed indexed annuities credit index interest only at the end of a term, so this detail can add meaningfully to the benefit after a strong market stretch.
Because the death benefit passes by beneficiary designation, it generally avoids probate, along with the delays, costs, and publicity probate can involve. Our guide to annuity beneficiary death benefits explains the payout choices beneficiaries typically have and how those choices affect taxes.
Married owners should pay particular attention to how the contract is titled. A surviving spouse named as sole beneficiary can often step into the owner’s role and keep the contract going instead of cashing it out, which keeps the money growing tax-deferred. Our page on continuing an annuity as a spouse outlines when keeping the contract makes more sense compared with taking the death benefit.
The Optional Enhanced Death Benefit Rider
The feature that sets LibertyMark Freedom apart is its optional enhanced death benefit rider. It is available to owners who are age 75 or younger when the contract is issued, must be elected at purchase, and requires no medical underwriting. The rider is not available in California.
The enhanced benefit equals the single premium, reduced by any prior withdrawals and surrender charges, multiplied by a guaranteed roll-up of 8 percent simple interest for up to 15 years. Because the roll-up is simple rather than compound, the benefit grows by the same dollar amount each year: $8,000 a year on a $100,000 premium. There is no waiting period, so whatever has accrued is payable from the start, and beneficiaries receive it in one payment.
The rider costs 0.15 percent of the enhanced death benefit payable, deducted at the end of each contract year. On a $100,000 premium, that is $150 at the end of the first year, rising as the enhanced benefit grows. The table below shows how the enhanced benefit builds on a $100,000 premium with no withdrawals, based on the values Americo publishes in its product materials.
| Contract Year | Enhanced Death Benefit | As a Share of Premium |
|---|---|---|
| Year 1 | $100,000 | 100% |
| Year 3 | $116,000 | 116% |
| Year 6 | $140,000 | 140% |
| Year 11 | $180,000 | 180% |
| Year 16 and Later | $220,000 | 220% |
Because the rider charge reduces the accumulation value each year, an owner who never needs the enhanced benefit pays a modest cost for it. For owners whose priority is the legacy, that cost buys a guaranteed, predictable increase that does not depend on index performance.
What the Rider Costs Over Time
A low percentage can still add up, so it is worth running the numbers on the enhanced death benefit rider before electing it. The charge is 0.15 percent of the enhanced death benefit payable, deducted at the end of each contract year. On a $100,000 premium with no withdrawals, the charge starts at $150 in the first year, rises to $198 in the fifth year as the enhanced benefit reaches $132,000, and reaches $318 in the fifteenth year, when the enhanced benefit is $212,000.
Added together over the first fifteen contract years, those charges total about $3,510. In exchange, the enhanced benefit available to beneficiaries reaches $220,000, which is $120,000 more than the original premium. Put another way, roughly $3,500 in rider charges supports a guaranteed increase of $120,000 in the amount payable at death, provided the owner makes no withdrawals and holds the contract long enough for the full roll-up.
The calculation has two caveats. First, the charges are deducted from the accumulation value, so they also reduce the base on which index interest is credited, which slightly lowers growth over time. Second, the enhancement only matters if the enhanced benefit exceeds the standard death benefit. In a period of unusually strong index credits, the accumulation value could approach or exceed the enhanced amount, in which case the rider would have cost money without changing the result.
For most owners whose primary goal is the legacy, the trade is favorable, because an 8 percent simple roll-up is far more predictable than index performance. For owners who mainly want growth or income, the rider charge is a cost with little benefit, and the contract works well without it. Our office illustrates both versions side by side so the decision is based on your numbers.
A Life Insurance Alternative for Declined Applicants
The enhanced death benefit rider makes LibertyMark Freedom one of the more useful tools available for people who cannot qualify for life insurance because of their health or occupation. The annuity itself requires no medical underwriting, and neither does the rider, so a history of heart disease, cancer, or a hazardous job does not affect eligibility. Our page on alternatives to life insurance after a decline explains how this strategy compares with guaranteed issue coverage and other options.
Consider a 70-year-old who was declined for life insurance and has $150,000 in certificates of deposit intended for children. Placed in LibertyMark Freedom with the rider, that money would carry an enhanced death benefit that grows by $12,000 a year, reaching $330,000 if held for 15 years. The same money left in CDs would pass at its balance plus whatever interest it earned.
The strategy has limits that should be understood. The death benefit is built from your own deposit, so it cannot match the leverage of a life insurance policy for a healthy applicant. Heirs owe ordinary income tax on growth above the premium, whereas life insurance proceeds generally arrive free of income tax. And the full enhancement takes 15 years to build, so the benefit in the early years is much closer to the deposit.
For the right person, though, the comparison is not with life insurance that is unavailable. It is with savings that would otherwise pass without any enhancement. Measured that way, a guaranteed 8 percent simple roll-up at a 0.15 percent annual cost is a strong result, and our office reviews this option for declined clients alongside the other paths available to them.
How LibertyMark Freedom Is Taxed
As with any deferred annuity, interest credited to LibertyMark Freedom grows tax-deferred, so no tax is due until money is withdrawn. For a non-qualified contract funded with after-tax money, earnings come out first and are taxed as ordinary income, and anything taken out before age 59½ can also trigger a 10 percent federal penalty. Those rules are covered in our article on taxes on non-qualified annuities.
For a qualified contract funded with IRA or other retirement plan money, every dollar withdrawn is generally ordinary income, since those contributions were made before tax, and required minimum distributions apply. A Roth IRA funded contract follows Roth rules, which can allow qualified withdrawals to be received tax-free.
Death benefits follow the same pattern. Beneficiaries of a non-qualified contract owe ordinary income tax on the gain above the owner’s premium, while beneficiaries of a qualified contract generally owe tax on the full amount, subject to the distribution rules for inherited retirement accounts. Unlike stocks or real estate, annuity gains are not stepped up when the owner dies, so the enhanced death benefit’s growth is taxable to the beneficiaries when paid.
These rules are not unique to LibertyMark Freedom, but they shape how it should be used. Many owners keep non-qualified money intended for heirs in the contract and use other assets for income, which keeps withdrawals, and the taxes on them, to a minimum. Your CPA should review the tax picture for your situation.
Using Rollover and IRA Money
Many LibertyMark Freedom buyers fund their contracts with retirement plan rollovers. Money moving from a 401(k), 403(b), Thrift Savings Plan, or other employer plan can be transferred directly into an IRA annuity without current taxes, as long as the transfer is handled as a direct rollover. Our guide to the best annuities for a TSP rollover covers the steps and considerations for federal employees.
A rollover into LibertyMark Freedom offers principal protection and index-linked growth that many employer plan options do not. It also allows the owner to add the enhanced death benefit rider, which can be attractive for retirees who expect to leave part of their IRA to heirs.
The trade-offs should be weighed before moving money. Employer plans may offer lower-cost investment options, institutional funds, or creditor protections that differ from those of IRAs. Some plans allow penalty-free withdrawals after separation from service at age 55, which an IRA does not. The surrender schedule on the annuity also limits access in ways a plan may not.
For IRA money intended primarily for heirs, the combination of tax deferral, principal protection, and the rider can be compelling. For IRA money needed for income, required minimum distributions and withdrawals reduce the enhanced benefit, so our office models those effects before recommending how much of an IRA to place in the contract.
Declined for life insurance and want to leave more to your family?
Illustrate My Enhanced Death Benefit
Who LibertyMark Freedom Fits, and Who It Does Not
LibertyMark Freedom fits savers who want principal protection, index-linked growth, and no mandatory fees, and who can leave their money in place for seven to ten years. It fits especially well for people with a legacy goal, including those who have been declined for life insurance, because the enhanced death benefit rider provides a guaranteed, growing benefit at a low cost. Owners who appreciate the ability to choose between fee-free and buy-up index options will also find more control here than in many competing contracts.
It is a poorer match when the main objective is guaranteed lifetime income. The contract does not offer a guaranteed lifetime withdrawal rider, so the only path to guaranteed income is annuitization, which gives up access to the principal. Buyers focused on income should compare contracts built for that purpose, and our list of the top indexed annuities with income riders is a good starting point.
It is also a weaker fit for anyone who may need substantial access to the money during the surrender period, for New York residents, who cannot buy it, and for California residents who want the enhanced death benefit rider, which is not offered there. Owners over age 75 can buy the base contract but cannot add the rider.
Finally, buyers who simply want a guaranteed fixed rate with no index variability may be better served by a multi-year guaranteed annuity. The right choice depends on goals, time horizon, and how much variability you are comfortable with in exchange for growth potential.
How LibertyMark Freedom Compares
Compared with a multi-year guaranteed annuity, LibertyMark Freedom trades a known fixed rate for the potential of higher index-linked credits, with a zero floor in down years. Americo’s own MYGA, covered in our review of the Americo Platinum Assure MYGA, shows the fixed-rate alternative within the same company. Our comparison of fixed annuities vs. fixed indexed annuities explains the trade-off more broadly.
Compared with other fixed indexed annuities, LibertyMark Freedom’s distinguishing features are the enhanced death benefit rider, the choice of fee-free or buy-up versions of every index option, partial-year index credits at death, and the absence of mandatory fees. Its main gaps are the lack of a lifetime income rider and the absence of a premium bonus in the versions described here.
Compared with life insurance, LibertyMark Freedom offers no leverage for a healthy applicant, since a life policy will usually provide a far larger, income-tax-free death benefit for the same dollars. For someone who cannot obtain life insurance, the comparison reverses, because the rider provides a meaningful enhancement where no other option exists.
No single annuity is right for everyone, which is why our office compares LibertyMark Freedom against several competing contracts for each client, using current rates, the client’s state, and the client’s goals, before recommending it.
Questions to Ask Before You Buy
A few questions sort out quickly whether LibertyMark Freedom belongs in your plan. The first is how long the money can stay in place. If you may need more than the annual penalty-free amount during the next seven to ten years, a shorter surrender period or a different product may be the better choice, because surrender charges and the market value adjustment can reduce an early withdrawal.
The second is what the money is for. If the goal is growth with principal protection, the base contract and the choice of index options matter most. If the goal is leaving money to heirs, the enhanced death benefit rider and your age at issue become central. If the goal is guaranteed lifetime income, a contract with an income rider will usually serve you better.
The third is which version is available where you live and whether the rider is available there. California residents cannot add the rider, New York residents cannot buy the contract, and the ten-year version offered depends on your state.
The fourth is how you plan to allocate between the Declared Interest Option, standard index options, and buy-up options. Each choice carries its own trade-off between predictability and growth potential, and allocations can be changed at the end of each term.
The last is how the contract fits with the rest of your finances, including emergency savings, other retirement income, existing life insurance, and beneficiary designations. Answering these questions with our office before applying helps ensure the contract you buy is the one that fits.
How Our Office Helps
Every recommendation starts with your goals. Jason and our office ask what the money is for, how long it can stay in place, whether leaving a legacy matters, and whether you have been able to obtain life insurance. Those answers determine whether LibertyMark Freedom belongs on the short list and, if so, which version fits your state and time horizon.
From there, we provide current caps, participation rates, and declared rates for your version, illustrate how the enhanced death benefit would grow for your premium and age, and show how fee-free and buy-up allocations might perform under different market conditions. We also compare the contract with competing products, including those with lifetime income riders or premium bonuses, so you can see what you would gain or give up.
When you are ready, we help with the application, beneficiary designations, rollover paperwork, and the decision to elect the rider. After the contract is issued, we review allocations with you at each index term and revisit the plan as your needs change. As an independent office, we let your goals, not a carrier’s product shelf, drive the recommendation.
Ready to compare LibertyMark Freedom with other top annuities?
Talk to Our Office
Financial Protection Essentials
More resources for growing, protecting, and passing on your retirement savings.
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Can I lose money in LibertyMark Freedom?
Not from index declines, because index credits never fall below zero and the guaranteed minimum value sets a floor. Your value can be reduced by surrender charges and a market value adjustment if you withdraw too much early, by the 1 percent charge on buy-up options in years when the index does not credit, and by the rider charge if you elect the enhanced death benefit. Our article on common fixed indexed annuity myths debunked covers these trade-offs.
Will my beneficiaries pay tax on the enhanced death benefit?
Generally yes, on the portion above what you paid in. For a non-qualified contract, heirs report that growth as ordinary income, and for an IRA-funded contract the full amount is generally taxable. There is no step-up in basis for annuity gains. More detail is in our article on taxes on annuity death benefits.
Can I name more than one beneficiary, or a trust?
Yes. Annuity owners can typically name multiple primary and contingent beneficiaries with set percentages, and a trust can be named when it fits the estate plan. The choice affects payout options and taxes, so it should be coordinated with your attorney. Our page on whether annuities have beneficiaries covers how designations work.
Can I move money from a CD into LibertyMark Freedom?
Yes. Maturing CDs are a common source of funds, especially for owners who want the enhanced death benefit for money intended for heirs. If a CD has not matured yet, ask the bank what penalty applies before moving it. The steps are laid out in our guide to moving a CD into an annuity.
Can I roll my 401(k) into LibertyMark Freedom?
Yes, typically through a direct rollover into an IRA annuity, which avoids current taxes. Compare the plan’s investment options, fees, and access rules with the annuity’s surrender schedule before moving money. Our guide to the best annuities for a 401(k) rollover covers the decision.
How are IRA-funded LibertyMark Freedom contracts taxed?
Withdrawals from a traditional IRA contract are generally fully taxable as ordinary income, required minimum distributions apply, and money taken before age 59½ can face a 10 percent penalty. A Roth IRA contract follows Roth rules. Our page on qualified annuity taxation explains the rules.
How does LibertyMark Freedom compare with other top indexed annuities?
Its strengths are the enhanced death benefit rider, fee-free and buy-up versions of every index option, and no mandatory fees. Contracts with lifetime income riders or premium bonuses may fit better for other goals, and current rates change the comparison. Our ranking of the best fixed indexed annuity options shows how leading contracts differ.
I already own an annuity. Should I move it to LibertyMark Freedom?
It depends on remaining surrender charges in your current contract, the benefits you would give up, your age, and whether the enhanced death benefit rider meets a real goal. A move can make sense, but it should be evaluated carefully. Our office can line up both contracts side by side through an annuity second opinion review.
What happens to the enhanced death benefit if I take a withdrawal?
It goes down. The enhanced benefit is calculated on your single premium reduced by prior withdrawals and any surrender charges, so every withdrawal, including penalty-free withdrawals and required minimum distributions, lowers the amount the roll-up applies to. Owners who want the full enhancement should plan to leave the contract untouched and use other assets for income.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to Best Fixed Indexed Annuity Products — covering individual fixed indexed annuity product reviews from top-rated carriers from 100+ carriers.
Last Reviewed: October 11, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
