
Global Atlantic SecureFore 5 – A Fixed Annuity with Guaranteed Growth and Flexibility
Global Atlantic SecureFore 5 – A Fixed Annuity with Guaranteed Growth and Flexibility
At Diversified Insurance Brokers, we specialize in helping individuals secure guaranteed growth, tax-deferred accumulation, and long-term financial stability through carefully structured annuity strategies. The Global Atlantic SecureFore 5 Fixed Annuity, issued by Forethought Life Insurance Company, a subsidiary of Global Atlantic Financial Group, is a single-premium deferred fixed annuity (MYGA) with a 5-year guaranteed rate period, designed for conservative savers who want predictable, contractually guaranteed returns without exposure to market volatility. Global Atlantic is wholly owned by KKR & Co. (full ownership completed January 2024) — one of the world’s largest alternative asset managers with over $500 billion under management. That KKR backing is the mechanism behind Global Atlantic’s rate competitiveness: KKR’s alternative credit investment platform allows Global Atlantic to generate higher yields on its reserves than traditional bond-portfolio carriers, which translates into MYGA rates that consistently rank in the top five nationally. Global Atlantic carries an AM Best A (Excellent) rating, a NAIC Complaint Index of 0.55 (below the 1.00 industry average — fewer complaints than expected for its size), and $170+ billion in total assets. The SecureFore 5 is an accumulation-focused product — no income rider, no bonus, no index exposure. Its competitive position is rate leadership at the A-rated MYGA tier for 5-year terms, supported by the institutional KKR investment platform. Reviewing current fixed annuity rates and current annuity rates across the full market establishes how the SecureFore 5 competes at any point in time.
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Global Atlantic SecureFore 5: Key Product Features at a Glance
| Product Feature | Details |
|---|---|
| Issuing Carrier | Forethought Life Insurance Company. Subsidiary of Global Atlantic Financial Group, wholly owned by KKR & Co. (full ownership January 2024). $170+ billion in total assets. AM Best: A (Excellent) — 3rd highest of 13 categories. NAIC Complaint Index: 0.55 (below 1.00 industry average — fewer complaints than expected). Comdex: 78 (November 2025). Distributed exclusively through licensed independent insurance agents and broker-dealers — no direct consumer sales. In certain states, contracts may be issued by Accordia Life and Annuity Company or Commonwealth Annuity and Life Insurance Company. Not FDIC insured. All guarantees backed by claims-paying ability of the issuing company. |
| Product Type and Term | Single-premium deferred fixed annuity (MYGA). 5-year guarantee period. After the guarantee period, the rate is declared for one-year periods — confirm whether the contract auto-renews or requires action at the carrier level at application. No bonus, no income rider, no index exposure. No monthly or annual fees. Tax-deferred compound growth. MVA applies on excess withdrawals. Single premium only. SecureFore series also available in 3-year and 7-year terms (SecureFore 3, SecureFore 7) — confirm current availability at application. SecureFore II (an updated version) is also currently available with current rates approximately 5.10% on 5-year — confirm which version is active and current at application. |
| Minimum Premium and Rate Banding | Minimum: $10,000. Two rate bands: $10,000–$99,999 (lower rate) and $100,000+ (higher rate). Higher premium band earns meaningfully more — confirm the current rate differential between bands at application. Qualified and non-qualified funding accepted: Non-Qualified, Traditional IRA, Spousal IRA, IRA Rollover, IRA Transfer, SEP IRA, IRA-Roth, Inherited IRA, NQ Stretch, Roth Conversion. Funding timelines: Qualified — 60 days; Non-Qualified — 14 days; 1035 Exchange — 60 days. |
| Free Withdrawal Provision | Year 1: Up to 10% of the Annuity Deposit (premium paid) penalty-free. Year 2+: Up to 10% of the beginning-of-year contract value annually, penalty-free and without MVA. Non-cumulative. RMD waiver: IRS-required minimum distributions are available without surrender charges even if the RMD amount exceeds the standard 10% free withdrawal limit — except in the year of full surrender. Excess withdrawals above the free provision trigger surrender charges and MVA. |
| Health Waivers (No Cost) | Nursing Home Confinement Waiver: After the first contract anniversary, withdrawal charges waived if confined to an approved nursing facility for at least 90 consecutive days (60 days in CA, DE, FL, ND, SD). Does not include home health care. Terminal Illness Waiver: After the first contract anniversary, withdrawal charges waived on any withdrawal upon qualifying diagnosis (12-month life expectancy). Annuitization Waiver: Withdrawal charges waived when converting to an annuity income stream. All three included at no additional charge. |
| Surrender Charges and MVA | 5-year surrender charge schedule starts near 8% in Year 1 and grades down linearly to 0% at the end of Year 5. Market Value Adjustment (MVA) also applies on excess withdrawals during the surrender period — can increase or decrease withdrawal value depending on interest rate conditions since issue. MVA does not apply to free withdrawals, the death benefit, or qualifying health event waivers. Surrender charges also waived at death. Principal is 100% guaranteed if held to the end of the withdrawal charge period, less prior withdrawals and less withdrawal charges on any prior withdrawals. |
| Optional Return of Premium Feature | Optional feature available at issue: if selected, guarantees that upon full surrender the owner receives no less than the original premium less all prior withdrawals — regardless of MVA or surrender charge impact. This provides a contractual principal floor on any early full surrender. Selecting this feature may result in a slightly lower declared rate — confirm the rate cost of electing Return of Premium at application. |
| Death Benefit | Full contract value paid to named beneficiaries at death — no withdrawal charges, no MVA. Proper beneficiary designation allows assets to transfer outside probate in most cases. Beneficiaries may choose a lump sum or available annuitization options. Reviewing annuity beneficiary death benefits covers distribution options and tax treatment for heirs. |
| Tax Treatment | Interest grows tax-deferred — no annual 1099 during accumulation. Non-qualified: LIFO — earnings distributed first, taxed as ordinary income; cost basis returned tax-free. Qualified accounts: full distributions taxed as ordinary income. No additional tax deferral for qualified accounts beyond the plan itself. Withdrawals before age 59½ subject to 10% IRS early withdrawal penalty. Not FDIC insured. |
KKR Ownership and Global Atlantic’s Rate-Leadership Model
Global Atlantic’s rate competitiveness is not accidental — it is structural. KKR’s alternative asset management platform allows Global Atlantic to invest its policyholder reserves in private credit, infrastructure debt, and other alternative assets that generate higher yields than the investment-grade public corporate bonds used by more traditional insurance carriers. The same model drives Athene’s rate leadership (Apollo-backed) and explains why KKR-backed Global Atlantic and Apollo-backed Athene consistently appear at or near the top of MYGA rate comparison tables among A-rated carriers. The trade-off: buyers are accepting the investment complexity of KKR’s alternative credit strategy as the backing for their guaranteed rate. AM Best’s A rating reflects its assessment that Global Atlantic’s financial strength is sufficient to meet policyholder obligations despite the more complex investment approach — the A (vs. A+ or A++) reflects that complexity premium. For buyers comparing the SecureFore 5 against similarly priced 5-year MYGAs from more traditional carriers, reviewing current 5-year MYGA rates and best MYGA annuity rates across the full market provides the direct competitive comparison — including how Global Atlantic’s current rate compares against A+ carriers like Athene, Nationwide, and Midland National at the same term and premium band. Global Atlantic also carries the legacy Forethought Life Insurance Company issuing entity name on many contracts — buyers searching for “Forethought Life” are searching for the same carrier now operating under the Global Atlantic brand following the 2014 acquisition.
Tax Deferral, CD Repositioning, Rollovers, and Portfolio Role
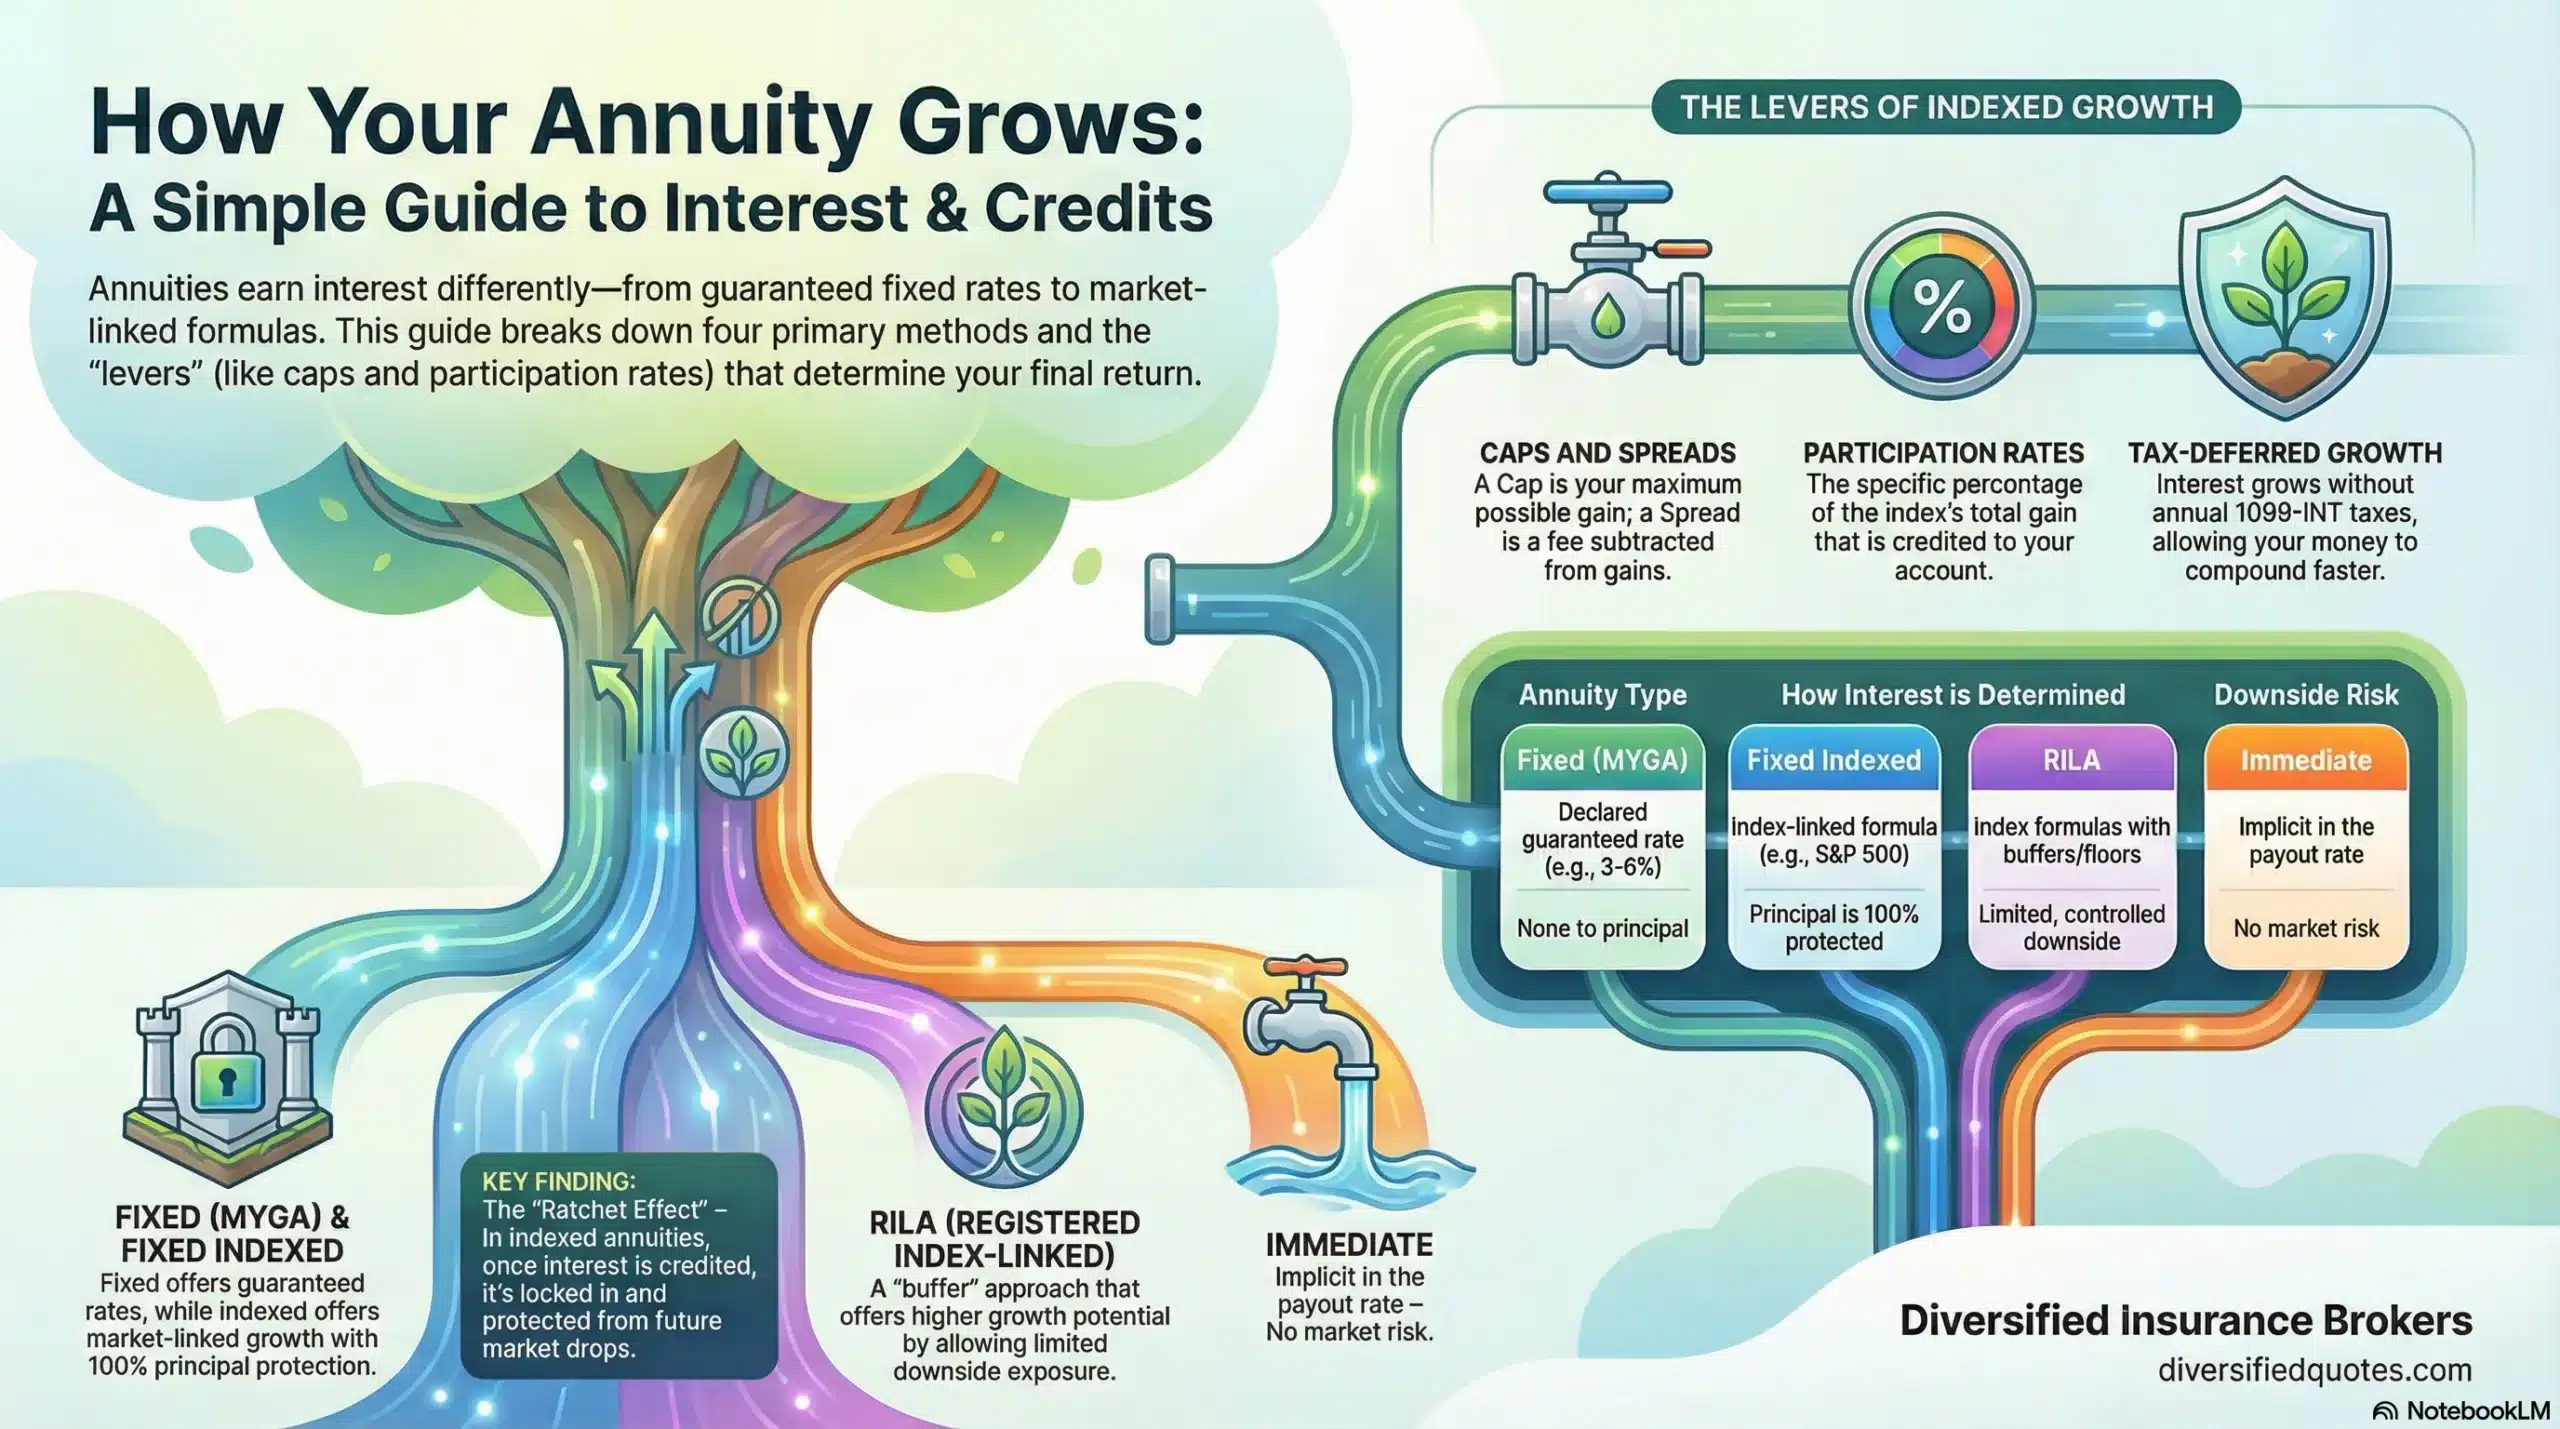
The SecureFore 5’s tax deferral advantage over bank CDs is identical to any MYGA: interest compounds without annual taxation, while CD interest generates a 1099 each year. Reviewing fixed annuities vs. CDs covers the full accumulated value comparison across tax brackets. For buyers repositioning maturing CDs, reviewing how to transfer a CD into an annuity covers the process and timing. For IRA rollover buyers, reviewing how to transfer an IRA to an annuity ensures the transfer is executed correctly — note that Global Atlantic’s non-qualified funding window is 14 days while qualified transfers allow 60 days. For qualified account holders managing required minimum distributions: the SecureFore 5’s RMD waiver allows distributions beyond the standard 10% free provision without surrender charges, making it compatible with IRA accounts subject to RMD obligations. From a portfolio perspective, the SecureFore 5 addresses sequence of returns risk by creating a principal-protected accumulation core entirely insulated from market performance. The fixed annuity ladder strategy works naturally with the SecureFore series — the 3-year, 5-year, and 7-year versions allow staggered maturity windows capturing different rate points along the yield curve. Reviewing laddering annuities covers how this rolling approach works. Coordinating SecureFore 5 maturity with Social Security and other income sources reduces bracket surprises — reviewing how Social Security and annuities work together covers that coordination. At maturity, reviewing whether to annuitize or use an income rider on a separate product covers the income transition options. Within the Global Atlantic product family, the ForeAccumulation II FIA is the alternative for buyers who want index-linked growth potential, and the Forethought Income 150 SE addresses buyers who want guaranteed lifetime income from Global Atlantic products. For buyers evaluating safe fixed annuity options across the full A-rated carrier landscape and the broader context of multi-year guaranteed annuities for retirees, the SecureFore 5 earns its position through KKR-backed rate leadership at the A-rated tier, a comprehensive waiver package (nursing home, terminal illness, annuitization), and the RMD waiver that makes it immediately compatible with qualified IRA assets. Reviewing pension alternatives alongside the SecureFore 5 provides context for buyers without defined benefit pension income who want guaranteed accumulation as a foundation.
Related Pages
Explore additional Global Atlantic products and MYGA planning resources.
Financial Protection Essentials
Explore life insurance strategies for seniors, global travel medical protection resources, and financial planning tools that help manage risk and long-term coverage needs.
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
FAQs: Global Atlantic SecureFore 5 Fixed Annuity
Why does Global Atlantic offer higher MYGA rates than many competing A-rated carriers?
Global Atlantic’s rate competitiveness is structural, not coincidental. As a wholly owned KKR subsidiary since January 2024, Global Atlantic benefits from KKR’s alternative asset management platform — one of the world’s largest, with over $500 billion in assets under management. KKR places Global Atlantic’s policyholder reserves into private credit, infrastructure debt, and other alternative assets that generate higher yields than the investment-grade public corporate bonds that traditional insurance carriers rely on. The additional yield from that investment approach flows through to the declared rates Global Atlantic can offer on the SecureFore 5 and its other MYGA products, which is why Global Atlantic’s 5-year MYGA rates regularly appear near the top of A-rated carrier rate tables. The parallel model: Apollo-backed Athene uses the same strategy to offer A+-rated rate leadership. The trade-off worth understanding: buyers are accepting the investment complexity of KKR’s alternative credit strategy as the backing for their guaranteed rate, rather than a more traditional bond portfolio. AM Best’s A (rather than A+ or A++) rating reflects that complexity premium. For buyers comparing the SecureFore 5 against Athene (A+, Apollo-backed, similar business model) or Nationwide (A+, traditional carrier model) at the same 5-year term, reviewing current 5-year MYGA rates with carrier ratings side by side provides the full context for the rate-vs.-rating evaluation.
Should I elect the Return of Premium feature — and what does it cost?
The optional Return of Premium (ROP) feature guarantees that upon full surrender at any time during the contract, the owner receives no less than the original premium paid less all prior withdrawals — regardless of what the Market Value Adjustment or surrender charge schedule would otherwise produce. Without ROP: on a full surrender during the surrender period, the combination of surrender charges and a negative MVA (in rising rate environments) could theoretically reduce the surrender value below original premium — though the contractual minimum guaranteed value also provides some protection. The ROP eliminates that scenario entirely and provides an absolute principal floor on full surrender at any time. The cost: electing ROP at issue typically results in a slightly lower declared rate. Confirm the current rate differential at application — on a $100,000 5-year contract, even 15 basis points of reduced rate equals approximately $750 in foregone accumulated interest over 5 years. Whether the ROP is worth that cost depends on the buyer’s actual probability of needing to fully surrender during the term. For buyers who have strong confirmed liquidity reserves outside the annuity and are genuinely committed to holding the full 5 years, the ROP may not be worth the rate cost. For buyers who have any meaningful probability of needing to fully exit the contract — particularly in an environment where interest rates might rise significantly, creating a sizable negative MVA — the ROP provides meaningful protection at a modest rate cost. Understanding how surrender charges and MVAs interact before evaluating the ROP election provides the analytical foundation for this decision.
How does the SecureFore 5 compare to the ForeAccumulation II MYGA?
The SecureFore 5 and ForeAccumulation II are both Global Atlantic (Forethought Life) products in the fixed accumulation space, but they serve different objectives. The SecureFore 5 is a pure MYGA: declared fixed rate locked for 5 years, no index exposure, maximum simplicity, no annual fees. The ForeAccumulation II is a fixed indexed annuity — it offers multiple index crediting strategies tied to external benchmarks (S&P 500, proprietary volatility-controlled indices), a zero floor protecting against market losses, and optional enhanced death benefit features. In a strong index year, the ForeAccumulation II may credit meaningfully more than the SecureFore 5’s declared rate. In a flat or negative index year, the ForeAccumulation II credits zero while the SecureFore 5 continues at its declared rate regardless of any index performance. The SecureFore 5 is right when the buyer wants maximum certainty about the accumulated value at maturity — no variability, no index exposure, predictable outcome from day one. The ForeAccumulation II is right when the buyer wants index-linked upside potential within a principal-protected structure and is comfortable with variable annual credits. The ForeAccumulation II also offers optional death benefit enhancements not available on the SecureFore 5. Within the Global Atlantic family, the Forethought Income 150 SE FIA addresses buyers whose primary objective is guaranteed lifetime income from the same carrier family.
What happens at the end of the 5-year term — and do I need to take action?
At the end of the 5-year guarantee period, a 30-day penalty-free window opens during which the full accumulated value is accessible without surrender charges or MVA. Multiple conflicting sources exist on whether the SecureFore 5 auto-renews — one credible source states the policy does not automatically renew for a new multi-year term and instead declares a new one-year rate; another source indicates it does auto-renew. Confirm the specific renewal behavior at application before purchasing. What is confirmed: after the 5-year guarantee period, the rate transitions to an annually declared structure, never falling below the Minimum Guaranteed Interest Rate (MGIR) established in the contract. During the 30-day penalty-free window, four options are available: (1) Withdraw the full accumulated value as a lump sum without any penalties; (2) Keep funds in the contract at the then-current annually declared rate; (3) 1035-exchange penalty-free into a new annuity — either another Global Atlantic product or a competing carrier’s product with a new multi-year rate lock; (4) Annuitize into a guaranteed income stream (annuitization waiver included at no cost). The critical planning step: before the 30-day window opens, compare Global Atlantic’s renewal rate offer against the best MYGA rates currently available across all carriers. In many cases, a 1035-exchange into a new 5-year MYGA at a competing carrier may capture a better rate than renewing with Global Atlantic — and the 1035-exchange eliminates any immediate tax consequence on the transfer. Diversified Insurance Brokers can run that comparison at no cost ahead of your maturity window.
How does the RMD waiver work — and is the SecureFore 5 compatible with IRA accounts subject to RMDs?
Yes — the SecureFore 5 explicitly accommodates required minimum distributions through a dedicated RMD waiver. In any year when the IRS-required minimum distribution from the contract exceeds the standard 10% annual free withdrawal limit, the excess RMD amount is still distributed without surrender charges. This means the mandatory distribution obligation does not create a penalty exposure regardless of the RMD amount relative to the contract value. The only exception: in the year of a full surrender, the full contract value liquidation includes surrender charges in the normal manner — the RMD waiver does not waive surrender charges on a complete contract liquidation in the same year. For qualified IRA account holders subject to RMDs, this waiver makes the SecureFore 5 compatible with ongoing distribution obligations during the 5-year guarantee period — no need to choose between RMD compliance and avoiding surrender charges. This waiver is meaningfully above the standard provision at many competing MYGAs where RMDs above the free withdrawal amount trigger partial surrender charges. Carriers like Nationwide (Secure Growth) and United of Omaha (Ultra-Secure Plus) similarly include RMD accommodations, but the specific mechanics vary — confirm the exact RMD waiver terms in the SecureFore 5 contract disclosure at application.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to What Is a Fixed Annuity? — covering fixed annuities, MYGAs, laddering strategies & conservative growth options from 100+ carriers.
Last Reviewed: June 23, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
