
Cincinnati Life Portfolio MYGA Annuity
Cincinnati Life Portfolio MYGA Annuity
Most fixed-rate annuities lock a rate for years and then leave you stuck negotiating your way out if the renewal disappoints you. Portfolio MYGA from Cincinnati Life is built around a genuinely useful alignment most competing contracts don’t offer: the same five-year window that guarantees your rate is also the exact window your surrender charge runs out in. When the guarantee period ends, so does the penalty for walking away. That single design decision is the most important thing to understand about this contract before anything else.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and this is a contract worth understanding on its actual mechanics rather than its marketing name. As an independent broker representing Cincinnati Life alongside dozens of other carriers, we’ll walk through exactly what’s guaranteed, what isn’t yet confirmed, and how this contract compares against other multi-year guaranteed annuities before you commit any funds.
Considering Portfolio MYGA and want the mechanics explained plainly?
Talk to an Annuity Specialist
| Feature | Detail |
|---|---|
| Issuing Carrier | The Cincinnati Life Insurance Company, Fairfield, Ohio, a subsidiary of publicly traded Cincinnati Financial Corporation (Nasdaq: CINF). For a full look at the carrier’s financial strength, see our standalone review of whether Cincinnati Life is a good insurance company. |
| Product Type | Single premium deferred multi-year guaranteed annuity. Base interest rate guaranteed for the first five contract years; after that, the base rate is declared annually. |
| Issue Ages | 0–85 |
| Maturity Age | 85, or 10 years after issue, whichever comes later |
| Premium Limits | Minimum $10,000. Maximum $1,000,000 without special approval; amounts above that require headquarters sign-off. |
| Premium Type | Qualified and non-qualified funds accepted. |
| Surrender Period | 5 years, declining to zero, with no charge from year six forward. |
| Guaranteed Minimum Interest Rate | Set at issue and fixed for the life of the contract, within a contractual range of 0.15% to 3%. |
| Contract Structure | Owner-driven — the contract owner’s death, not the annuitant’s, is what triggers the death benefit payout to the named beneficiary. |
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
Two Five-Year Clocks, and Why They’re Set to the Same Time
Here’s the mechanic worth understanding clearly before anything else on this page. The base interest rate on this contract is guaranteed for exactly five years from issue. After that fifth year, the rate is no longer locked — it’s declared annually going forward, meaning it can move, up or down, each year the contract continues beyond that point.
What makes this genuinely well-designed is that the surrender charge schedule runs on the identical five-year timeline and drops to zero at exactly the same point the rate guarantee ends. If the renewal rate declared after year five isn’t one you’re happy with, you’re not stuck absorbing a surrender charge to walk away from it — the exit is already clean by the time that renewal rate takes effect. This is a meaningfully different structure than a contract where the surrender period runs longer than the rate guarantee, which can leave a buyer locked into a contract they no longer want at a rate they didn’t agree to.
| Contract Year | 1 | 2 | 3 | 4 | 5 | 6+ |
|---|---|---|---|---|---|---|
| Surrender Charge | 7% | 6% | 5% | 4% | 3% | 0% |
Surrender charges are calculated from your contract date, not the date any specific premium payment was received — worth knowing if you’re funding the contract with a delayed transfer. A market value adjustment runs on this same five-year timeline as well, applying to withdrawals, surrenders, or annuitization during the surrender period, and it can move the amount you receive up or down depending on how interest rates have shifted since your contract was issued. In no case will this adjustment reduce your contract below the guaranteed minimum value required under standard nonforfeiture law.
One Withdrawal a Year, Not Unlimited Draws to 10%
In any contract year where a surrender charge still applies, you’re permitted one withdrawal of up to 10% of account value without triggering that charge or the market value adjustment. This is worth stating precisely, because it’s easy to misread: it’s one withdrawal, not an unlimited number of smaller withdrawals that together add up to 10%. Anyone planning to draw interest out on a regular schedule, such as quarterly, should understand this structure clearly before assuming that approach fits within the penalty-free allowance.
The Transfer Rate Lock: A Genuine Practical Advantage
Funding an annuity with cash alongside your application locks your rate at the greater of the rate in effect on your application date or the rate in effect when your application and funds actually arrive, provided everything is received in good order within seven calendar days of signing.
Funding through a 1035 exchange or a qualified transfer works differently, and meaningfully better for anyone who’s dealt with how slowly a surrendering carrier can move: this contract locks your rate for a full 90 calendar days from your application signature date, provided the signed paperwork itself reaches headquarters within the first seven days. If your transferred funds arrive anytime within that 90-day window, you still get the greater of the application-date rate or the funds-received-date rate. This matters more than it might seem — surrendering carriers routinely take 30 to 60 days to actually release funds, and a buyer who locks an attractive rate elsewhere can easily lose it while waiting on that transfer to complete. A 90-day window gives real breathing room most competing contracts don’t offer.
Working through a 1035 exchange or IRA transfer and want to understand your rate lock window?
Talk Through Your Transfer
A Genuine Open Question: The Annual Contract Charge
We want to be direct about something rather than gloss over it. This contract’s guaranteed minimum value calculation includes a deduction for a $50 annual contract charge, alongside a percentage of premium and any withdrawal activity. Separately, the same materials that describe this contract also state plainly that there are no up-front sales charges or fees to the client. Whether that $50 figure inside the minimum-value formula actually gets deducted from your everyday account value in practice, or whether it exists purely as a technical component of a floor calculation that rarely comes into play, isn’t something we’re going to guess at here. We confirm this specific point directly with the carrier before any client moves forward with this contract, and we’d encourage you to ask the same question plainly rather than assume either answer.
Protection If Your Health Changes: The Waiver Rider
Included automatically, at no additional cost, this contract carries a rider that waives surrender charges and any market value adjustment on a full or partial surrender if the owner is diagnosed with a terminal illness reasonably expected to result in death within 24 months, is confined to a hospital for at least 30 consecutive days, or is confined to a long-term care facility for at least 90 consecutive days.
The 30-day hospital confinement trigger is worth highlighting specifically, since it’s genuinely broader than what many competing MYGAs offer — most competing waiver riders trigger only on nursing home or long-term care confinement, leaving a purely hospital-based stay uncovered. This contract’s inclusion of a standalone hospital trigger is a real, practical advantage for a health event that doesn’t necessarily progress to long-term care at all.
What This Contract Can and Cannot Fund
| Can Fund | Cannot Fund |
|---|---|
| Traditional IRA | Coverdell Education Savings Accounts |
| Roth IRA | Section 529 College Savings Plans |
| SEP retirement plans | SIMPLE IRA plans |
| Non-qualified funds | Trusteed plans |
| Rollover money originating from a 401(k), 403(b), or certain pension plans | 401(k), 403(b), or 412(i) plans directly |
That last row deserves a direct explanation, because it’s a genuine point of confusion. This contract can accept rollover money that originated from a 401(k) or 403(b) plan — meaning funds that have already left that plan and are being transferred into this annuity. What it cannot do is serve as the 401(k) or 403(b) plan itself. The distinction is between receiving money that used to sit in one of those plans versus functioning as one, and the two are not the same thing.
Guaranteed Income Options at Annuitization
When you’re ready to convert this contract into income, four settlement options are available. Life income with payments guaranteed for a fixed period continues for whichever is greater: your lifetime or the selected guarantee period, giving some protection to a beneficiary if you don’t outlive that period. Joint and one-half to survivor life income bases payments on two lives, continuing at a reduced level for a surviving spouse. Income for a fixed period, with a 10-year minimum, pays out over your chosen timeframe. Income of a fixed amount, also with a 10-year minimum, pays a selected dollar amount until the funds are exhausted. Which of these fits depends entirely on whether your priority is lifetime protection, a defined payout period, or a specific income amount.
An Unusual Feature: Issue Age 0
Most multi-year guaranteed annuities are built with adult retirement savers in mind and set a meaningfully higher minimum issue age. This contract’s willingness to issue coverage from age 0 opens a genuine planning use most competing MYGAs simply can’t serve: custodial or minor-owned accumulation, funded and held on behalf of a child, growing on a tax-deferred basis well before that child reaches adulthood. This is a narrow use case, but a real one, and it’s worth knowing this contract can serve it when most alternatives can’t.
Extending Past Maturity: The Optional Maturity Date Provision
Standard maturity on this contract lands at age 85, or 10 years after issue, whichever is later. Many MYGAs force a decision at maturity — annuitize, or take a lump-sum payout — whether or not that timing actually suits the owner. This contract includes an optional provision allowing the owner to extend the maturity date indefinitely, in 10-year increments, while continuing tax deferral the whole time. For an older buyer, or anyone with a legacy-oriented goal rather than an income-timing need, this flexibility is a genuinely meaningful feature that avoids being forced into a decision on a schedule the contract sets rather than one the owner chooses.
The Death Benefit
This is an owner-driven contract, meaning it’s the contract owner’s death, not necessarily the annuitant’s, that triggers the death benefit payout. Beneficiaries receive the proceeds without any surrender charge and without IRS penalty, and the payout passes directly to the named beneficiary rather than through probate. Our broader explanation of how annuity death benefits work covers this mechanism in more general depth.
Tax Treatment
Growth inside this contract is tax-deferred until withdrawal. Surrenders taken before age 59½ are generally subject to the standard 10% federal early withdrawal penalty, unless the withdrawal is due to death or disability. Our overview of how annuities are taxed covers the broader framework governing qualified and non-qualified contracts alike.
Who This Contract Genuinely Fits
Portfolio MYGA suits a buyer who wants a straightforward rate guarantee without an especially long commitment, and who values knowing in advance that their exit from the contract is clean the moment that guarantee period ends, regardless of what happens to the renewal rate. It’s a strong fit for anyone funding through a 1035 exchange or a retirement account transfer, given the genuinely useful 90-day rate lock protecting against a slow-moving surrendering carrier. And it’s one of the few MYGAs worth considering for a custodial or minor-owned account, given the unusually low issue age.
It fits less well for a buyer who wants a longer rate guarantee locked in from the start and is willing to trade flexibility for it, or for anyone who wants to draw regular partial withdrawals more frequently than once a year without triggering a charge. And it’s worth applying with full clarity on the annual contract charge question addressed above before assuming you know exactly what ongoing costs, if any, apply to your specific account value.
How We Help
We’ll confirm directly with the carrier exactly how the annual contract charge functions in practice before you commit any funds, walk through your specific rate lock timeline if you’re funding this through a transfer or exchange, and compare this contract honestly against other multi-year guaranteed annuities on the market, including ones with longer rate guarantees, to make sure the five-year structure genuinely fits your goals rather than assuming it’s automatically the right length for you.
Our broader guidance on choosing the right annuity and genuine annuity suitability reflects the same care we bring to every contract we place. If you already hold an annuity and are wondering whether a shorter, cleaner-exit structure like this one might serve you better, our second-opinion review is built for exactly that conversation, and our guide on replacing an annuity the right way walks through what that would actually involve.
Ready to see how Portfolio MYGA compares against other MYGA options for your specific goals?
Get Your Annuity Comparison
Financial Protection Essentials
Explore life insurance options, carrier strength, and underwriting resources.
Talk to an Advisor or Request Your Annuity Quote
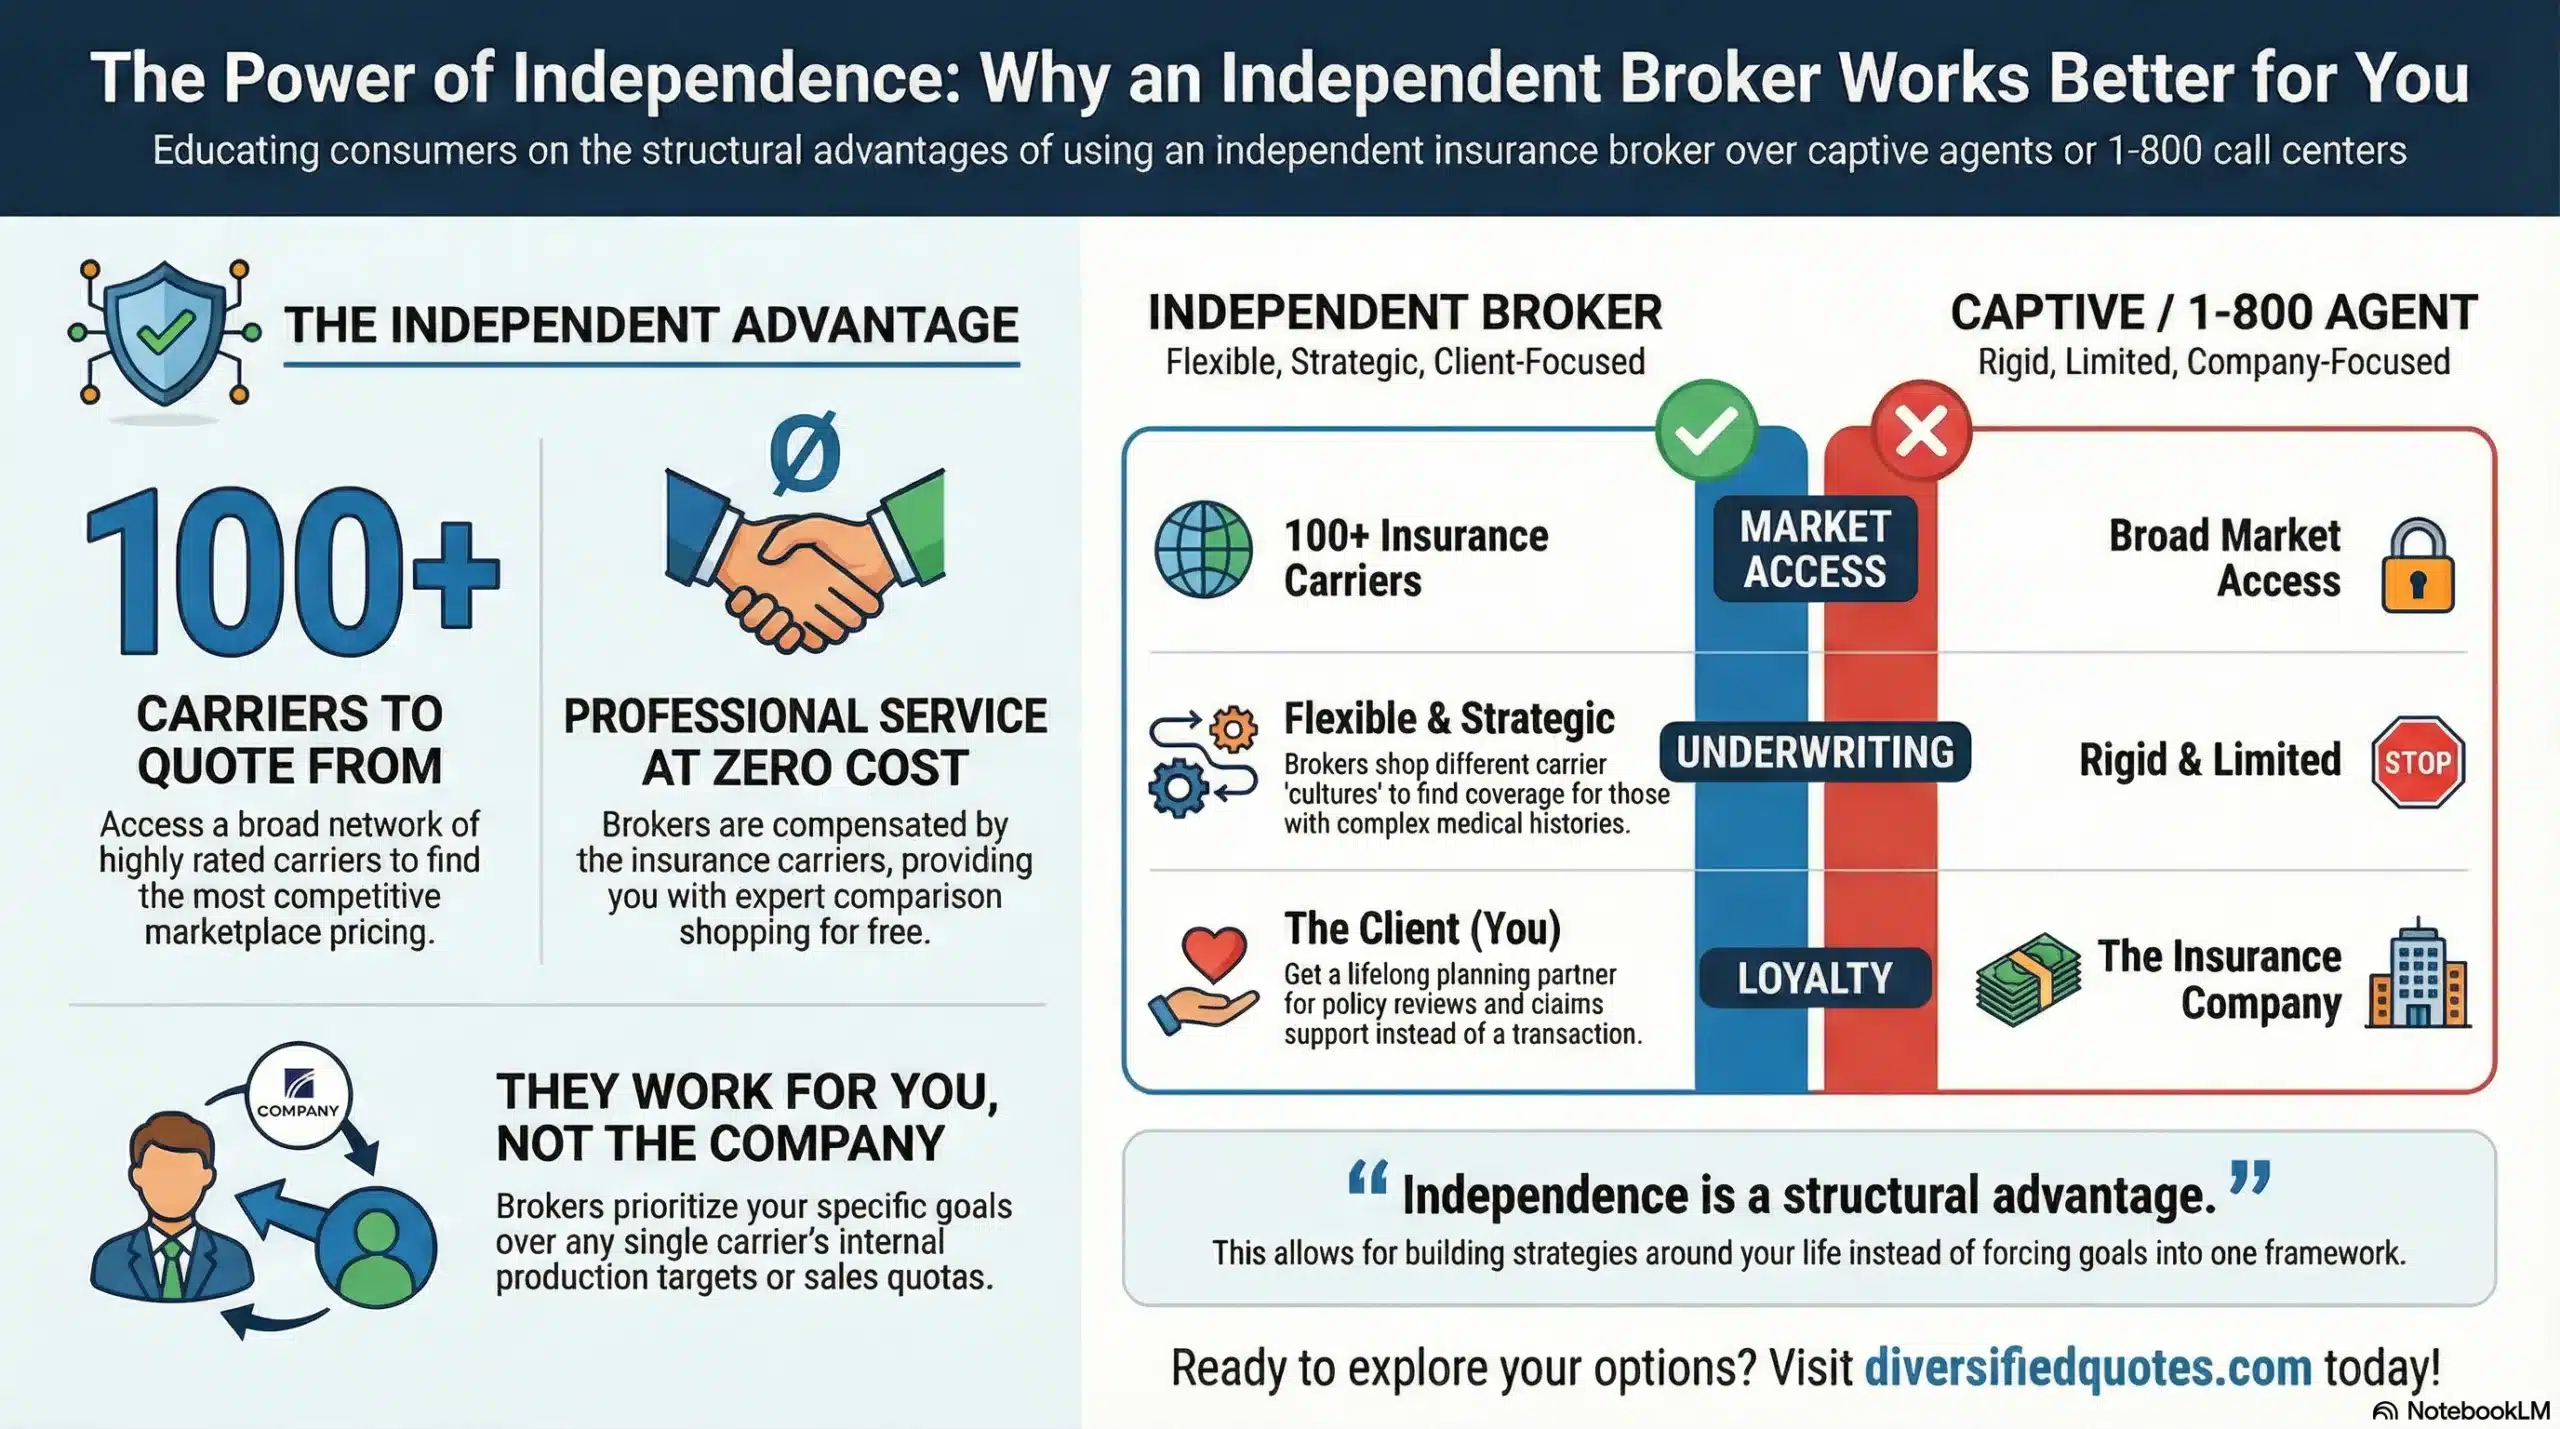
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Is the interest rate on Portfolio MYGA guaranteed for the entire contract?
The base rate is guaranteed for the first five contract years only. After that, the rate is declared annually and can move up or down. Conveniently, the surrender charge schedule also runs exactly five years and drops to zero at the same point the rate guarantee ends, so if the renewal rate isn’t one you want to accept, you can exit the contract cleanly with no surrender charge or market value adjustment at that point.
Can I withdraw 10% of my account value in multiple smaller payments each year?
No. The penalty-free allowance is structured as one withdrawal per contract year, up to 10% of account value, not an unlimited number of smaller withdrawals that add up to 10%. Anyone planning to draw interest on a regular schedule, such as quarterly, should understand this structure before assuming it fits within the penalty-free allowance.
How does the rate lock work if I’m funding this contract through a 1035 exchange or IRA transfer?
Rates can be locked for 90 calendar days from your application signature date, provided the signed paperwork reaches the carrier within the first seven days. If your transferred funds arrive anytime within that 90-day window, you receive the greater of the rate in effect on your application date or the rate in effect when funds are actually received. This is meaningfully longer than many competing contracts offer, which matters because surrendering carriers routinely take 30 to 60 days to release funds.
Does this contract charge an annual fee?
This is a genuinely open question worth being direct about. A $50 annual contract charge appears within the formula used to calculate the contract’s guaranteed minimum value, while separate materials state there are no up-front sales charges or fees to the client. Whether that $50 figure is actually deducted from ordinary account value in practice isn’t something we’ll assert either way without confirming it directly with the carrier first, which we do before any client moves forward with this contract.
What health events allow me to access funds without a surrender charge?
An included, no-cost rider waives surrender charges and any market value adjustment if the owner is diagnosed with a terminal illness reasonably expected to result in death within 24 months, is confined to a hospital for at least 30 consecutive days, or is confined to a long-term care facility for at least 90 consecutive days. The 30-day hospital confinement trigger is broader than what many competing MYGAs offer, since most limit this waiver to nursing home or long-term care confinement only.
Can I use 401(k) or 403(b) money to fund this annuity?
You can fund this contract with rollover money that originated from a 401(k), 403(b), or certain pension plans, but the contract itself cannot serve as a 401(k) or 403(b) plan. The distinction is between receiving funds that used to sit in one of those plans versus functioning as one directly — this contract can only do the former.
What happens to this contract at maturity?
Standard maturity is age 85, or 10 years after issue, whichever is later. Unlike many MYGAs that force a decision at maturity, this contract includes an optional provision allowing the owner to extend the maturity date indefinitely, in 10-year increments, while continuing tax deferral throughout. This is particularly useful for an older buyer or anyone with a legacy-oriented goal rather than an immediate income need.
Is Cincinnati Life a financially strong company?
Cincinnati Life is a subsidiary of publicly traded Cincinnati Financial Corporation. For a complete look at the carrier’s financial strength ratings and overall standing, our standalone carrier review covers this in full detail.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to What Is a Fixed Annuity? — covering fixed annuities, MYGAs, laddering strategies & conservative growth options from 100+ carriers.
Last Reviewed: September 11, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
