
Revol One Breakthrough Annuity Account MYGA
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
Revol One Breakthrough Annuity Account MYGA
If you’ve been parking after-tax savings in CDs because you wanted something simple, safe, and not locked away until retirement, the BreakThrough Annuity Account MYGA from Revol One Insurance Company is worth a close look before you renew that CD one more time. It’s a Multi-Year Guarantee Annuity — a fixed-rate contract with a guaranteed interest rate for a set number of years — but it’s built specifically around a different tax structure and a different promise than the traditional non-qualified annuity most people picture when they hear the word “annuity.”
The short version: it targets after-tax, fixed annuity money that isn’t earmarked purely for retirement — the fund for a future home purchase, a business opportunity, a kid’s wedding, or simply money you want growing at a guaranteed rate without a decade-long lockup. Below, we walk through exactly how it works, what makes it different from both a CD and a traditional deferred annuity, and — because this is the part that actually matters most before you apply — the honest, non-buried truth about its tax treatment claim.
A Rating You Should Know Before You Apply
Revol One Insurance Company, the issuer behind the BreakThrough Annuity Account, carries a Financial Strength Rating of B++ (Good) and a Long-Term Issuer Credit Rating of bbb (Good) from AM Best, with a positive outlook. That’s meaningfully lower than the A- and higher carriers that make up most of what we place. AM Best is currently the only major agency that publishes a rating on this carrier — there’s no S&P, Moody’s, or Fitch rating available for comparison, and no independent Comdex composite score exists for a single-agency-rated company. If you require a carrier rated A- or better as a condition of where your money sits, this may not be the right fit, and we’re happy to walk you through comparably structured MYGAs from more highly-rated carriers instead. Ratings are a point-in-time opinion and can change — confirm the current rating directly at ambest.com before you apply.
Ensure you are receiving the absolute top rates
Current Fixed Annuity Rates
Compare today’s best fixed annuity rates from top carriers.
Current Bonus Annuity Rates
See which annuities offer the highest upfront bonus today.
Request an Annuity Quote
Submit our annuity request form to get personalized rate options.
Lifetime Income Calculator
Use our calculator to see how much guaranteed income your annuity can provide.
BreakThrough Annuity Account MYGA — Product Highlights
| Feature | Details |
|---|---|
| Product Type | Single-premium deferred annuity — Multi-Year Guarantee Annuity (MYGA) |
| Issuer | Revol One Insurance Company (marketed as Revol One Financial) |
| Interest Guarantee Periods | 3, 5, 7, or 10 years — rate is fixed at issue, compounded daily, and locked for the full period selected |
| Issue Ages | 0–90 |
| Minimum Premium | $10,000 |
| Maximum Premium | $1,000,000 (higher amounts considered case-by-case with company approval) |
| Funds Accepted | Non-qualified (after-tax) funds only — this is not a vehicle for IRA or other qualified retirement dollars |
| Annuitization Options | Life with 5-Year Period Certain, Life with 10-Year Period Certain, 5-Year Period Certain, or 10-Year Period Certain |
| Maximum Annuitization Age | 100 |
| Free Look Period | 30 days |
| Renewal Notice | Contract owner is notified at least 15 days before each Interest Guarantee Period ends, with renewal choices to select from |
| State Availability | Not currently available in New York or California; other state variations may apply to riders and provisions |
Interest rates, riders, and rate reductions for optional riders vary and are set at issue — ask us for a current rate sheet for your state and guarantee period.
What Actually Separates This From the CD You’re Renewing
A CD and a MYGA solve the same basic problem — a guaranteed rate for a fixed term — through two structurally different products, and it’s worth understanding that difference before assuming they’re interchangeable. MYGAs and CDs compare on several dimensions that rarely get explained side by side: CDs are bank or credit union deposit products, insured by the FDIC or NCUA up to applicable limits. The BreakThrough Annuity Account is an insurance product, backed instead by the claims-paying ability and reserves of Revol One Insurance Company — which is exactly why the AM Best rating above matters as much as it does.
In exchange for giving up FDIC/NCUA insurance, MYGAs like this one generally offer higher guaranteed fixed rates than what’s available on most bank CDs of comparable term, plus features banks simply don’t build into a CD at all: a contractual death benefit that bypasses probate when a beneficiary is named, and the option to annuitize into guaranteed lifetime income later if you want it. If you’re currently sitting on CD money you’ve been meaning to move, both transferring a maturing CD into an annuity and the mechanics of how that transfer actually works are more straightforward than most people expect — it doesn’t require touching the funds yourself or triggering a taxable event on money that’s already been taxed.
The Trade-Off Nobody Should Skip Past: Annual Taxation Instead of Deferral
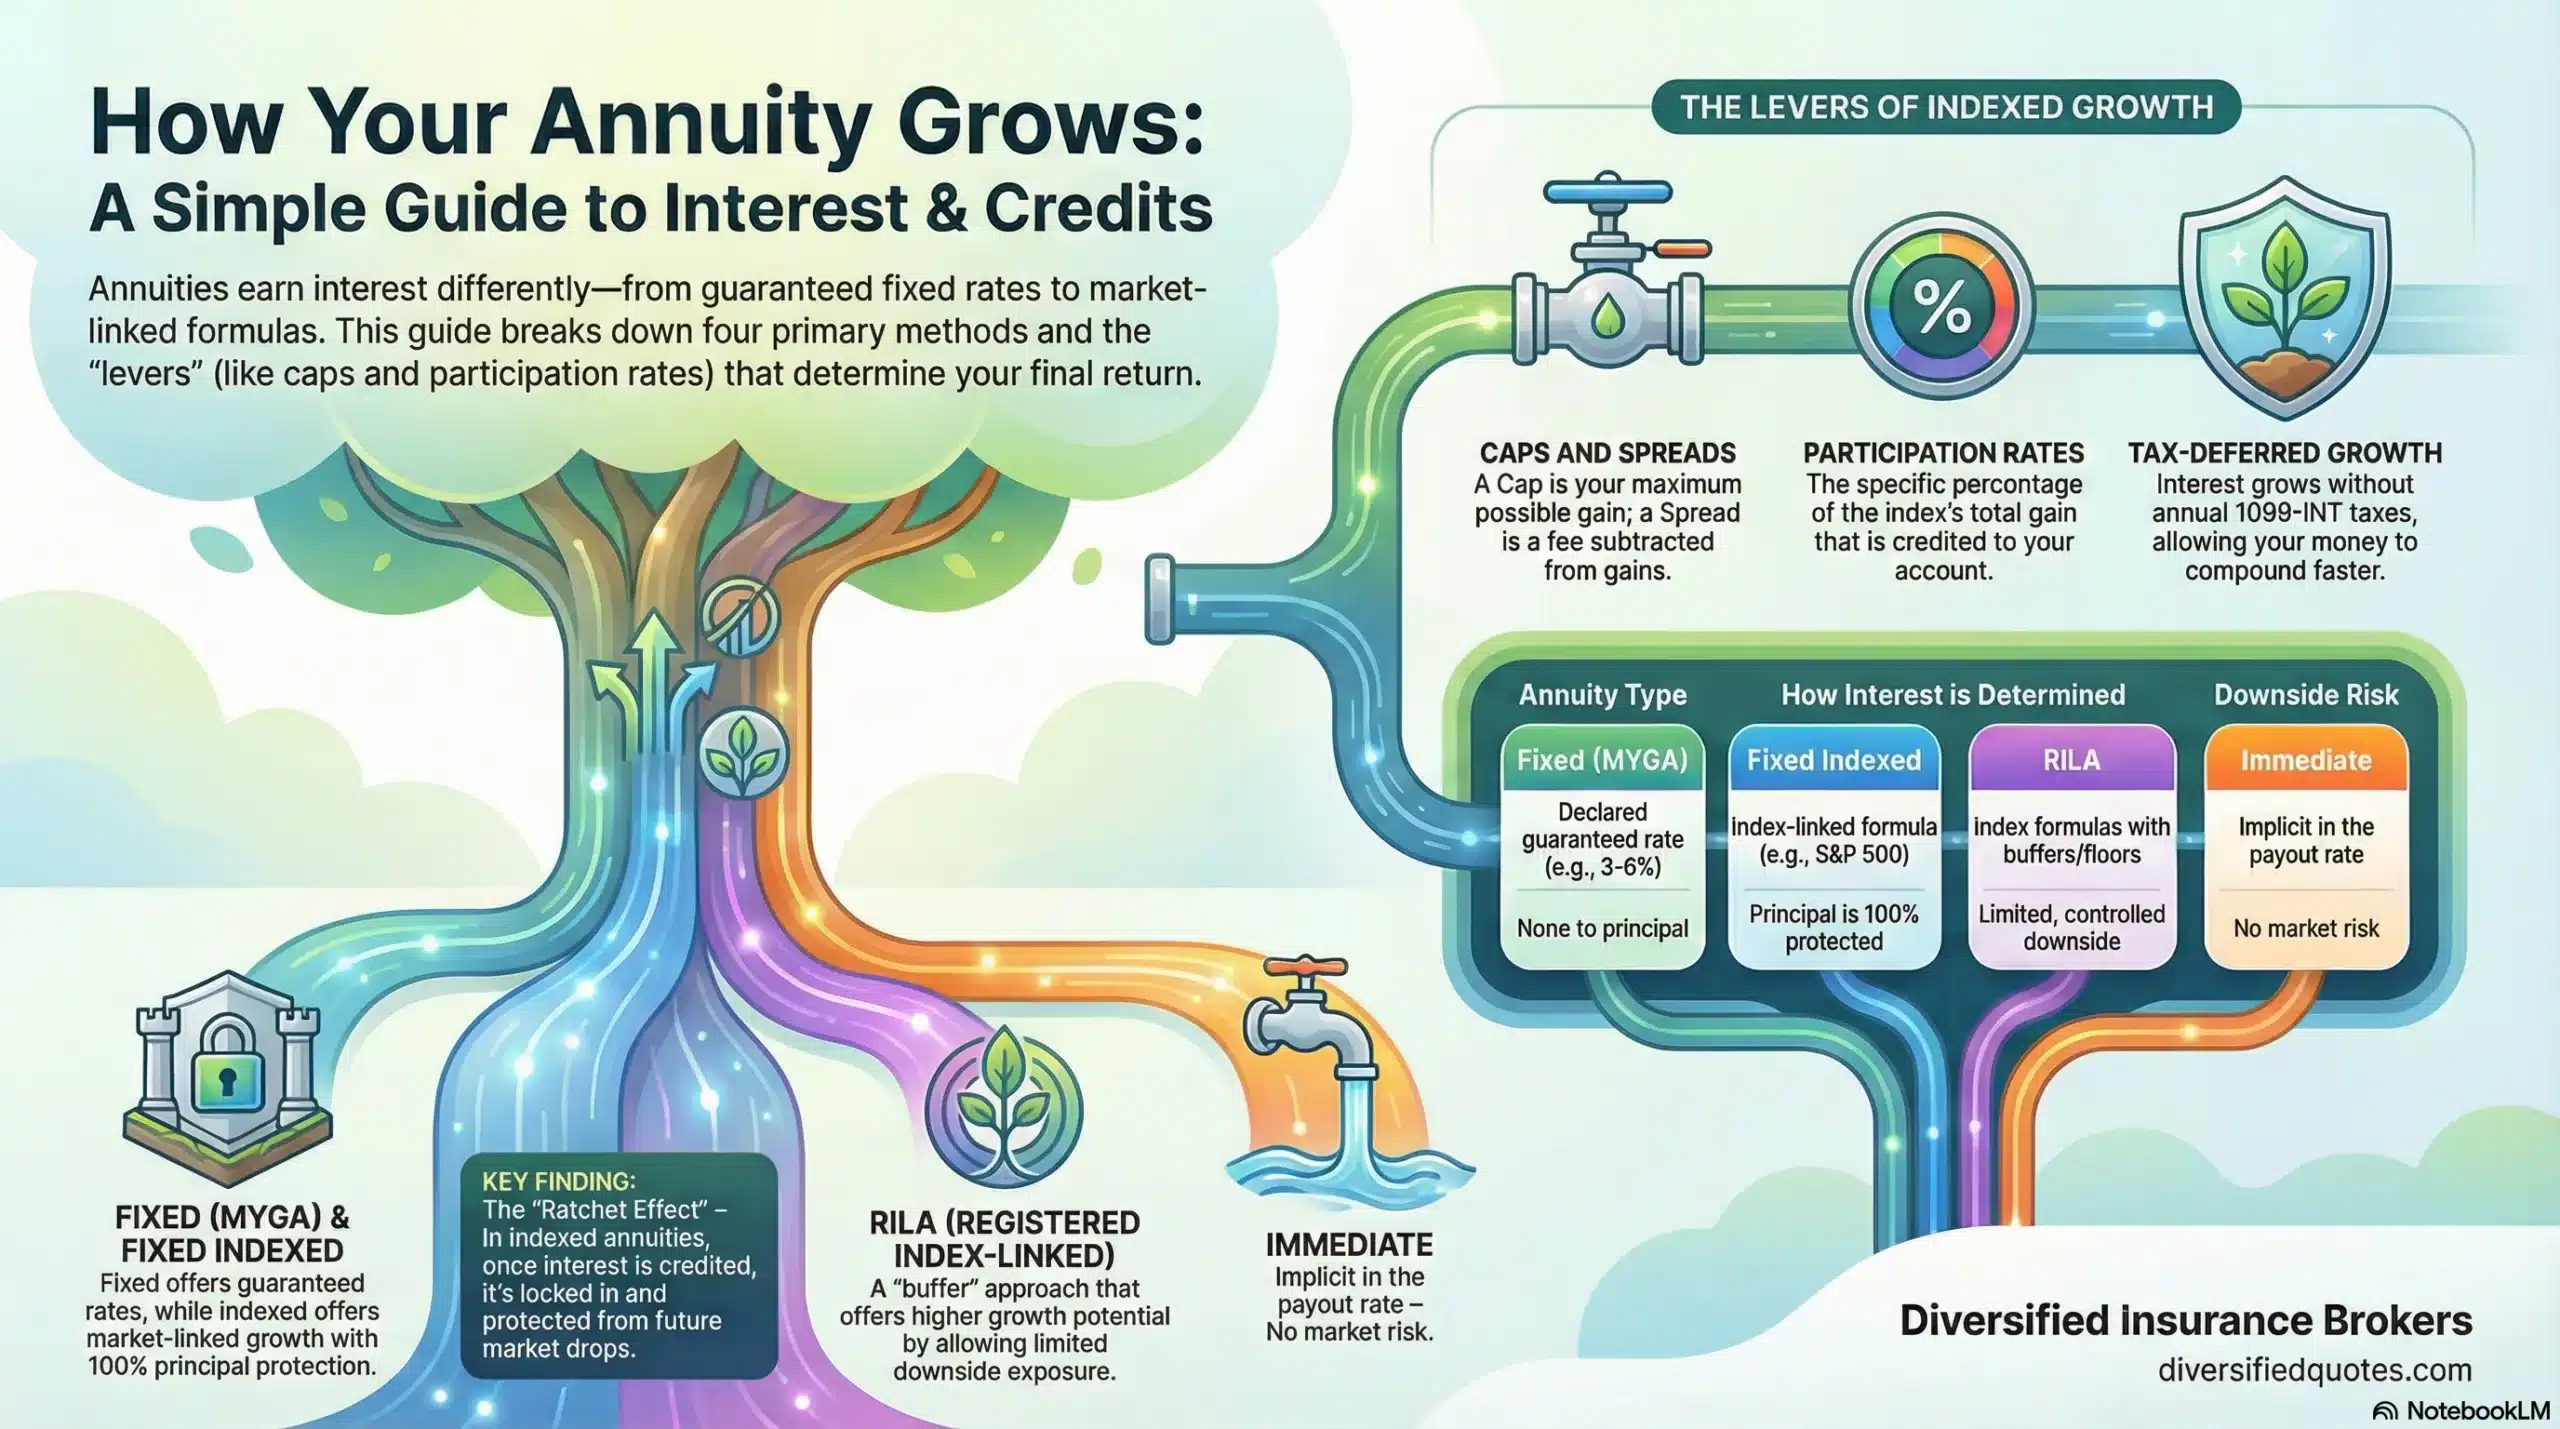
Here’s the part of this product that deserves your full attention, because it cuts against how most people assume annuities work. Traditional non-qualified annuity taxation defers taxes on growth until you actually withdraw money — that deferral is usually the headline selling point of an annuity. The BreakThrough Annuity Account does not work that way. Interest credited to the contract is taxed annually, in the year it’s earned, whether or not you actually withdraw it. You’ll receive a 1099 each year reporting that interest as taxable income, the same way you already do with a CD.
This isn’t a flaw buried in fine print — it’s the deliberate trade the whole product is built around, and understanding how annuities are typically taxed elsewhere makes the contrast clear. You give up tax deferral. In exchange, you get out from under a restriction that comes bundled with that deferral: the IRS 10% early withdrawal penalty on gains taken before age 59½, which is the very next section, and the one we want to be completely straight with you about.
The 10% Early Withdrawal Penalty Claim — Explained Honestly, Not Glossed Over
Most non-qualified deferred annuities tie their tax-deferral benefit to a real restriction: under IRC Section 72(q), gains withdrawn before age 59½ generally trigger a 10% federal early withdrawal penalty on top of ordinary income tax, the same way annuity free withdrawal rules typically work. Revol One Financial’s position is that because the BreakThrough Annuity Account taxes interest annually as it’s earned rather than deferring it, the contract falls outside the structure that triggers that IRS penalty in the first place — meaning gains can generally be withdrawn before age 59½ without the 10% penalty applying.
We want to be direct with you about exactly how settled that claim is, because it matters to your decision: there is no IRS private letter ruling confirming that the BreakThrough Annuity Account is exempt from the 10% early withdrawal penalty. The carrier states this explicitly, more than once, in its own product materials. This is Revol One Financial’s own current interpretation of how the tax code applies to this contract’s structure — a reasonable, deliberately engineered interpretation, but an unconfirmed one, not a settled ruling from the IRS itself. Tax law can also be interpreted differently by different tax professionals, and interpretations can be challenged or change. Before you rely on this feature as a reason to choose this product, we strongly recommend you review the specifics with a qualified tax advisor of your own — this is exactly the kind of detail that shouldn’t be taken on faith from any brochure, including ours.
What withdrawals from this contract are not automatically exempt from: ordinary state and federal income tax on the taxable gain, and — separately from the IRS penalty question — the contract’s own surrender charges and market value adjustment if you withdraw more than the penalty-free amount during the guarantee period. Those are covered next.
Surrender Charges and Market Value Adjustments, In Plain Terms
Like essentially every MYGA on the market, the BreakThrough Annuity Account applies a surrender charge if you take out more than the permitted free withdrawal amount before your Interest Guarantee Period ends. Unlike a CD’s flat early-withdrawal fee, that charge follows a declining schedule tied to how many contract years remain, and it can be paired with a Market Value Adjustment (MVA) — a separate mechanism, explained further below, that can move the amount you receive up or down depending on where interest rates have moved since your contract was issued. Reviewing how surrender charges and MVAs interact generally, and specifically how surrender charge schedules are structured, will help this table make more sense at a glance:
| Contract Year | 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
|---|---|---|---|---|---|---|---|---|---|---|
| 3-Year Period | 9% | 8% | 7% | 0% | — | — | — | — | — | — |
| 5-Year Period | 9% | 8% | 7% | 6% | 5% | 0% | — | — | — | — |
| 7-Year Period | 9% | 8% | 7% | 6% | 5% | 4% | 3% | 0% | — | — |
| 10-Year Period | 9% | 8% | 7% | 6% | 5% | 4% | 3% | 2% | 1% | 0.9% |
A 10-year contract’s charge falls to 0% starting in contract year 11. State variations may apply to this schedule. A new schedule applies if you renew into a new Interest Guarantee Period, and the first 30 days of any renewal period carry no surrender charge or MVA.
The MVA is the part people find least intuitive, so here’s the plain-language version: it’s a separate adjustment, applied only when a surrender charge also applies, that can move your payout up or down based on how interest rates have shifted since your contract started. Broadly speaking, if rates have fallen since your Interest Guarantee Period began, the MVA works in your favor and increases what you receive; if rates have risen, it works against you and reduces what you receive. In no case, regardless of surrender charges or a negative MVA, can your Cash Surrender Value fall below the contract’s Guaranteed Minimum Cash Surrender Value — a nonforfeiture floor set by state insurance law, not by the carrier’s discretion.
The contract also includes an optional Free Partial Surrender Rider (detailed further down) that lets you withdraw up to your annual interest-earnings potential each year without triggering any surrender charge or MVA at all — worth knowing about if liquidity during the guarantee period matters to you.
Death Benefit and Beneficiary Flexibility
Unlike a CD, which simply becomes part of an estate or payable-on-death account, this contract carries a built-in death benefit with no separate election required. If you pass away while the contract is in force, your named beneficiaries receive a death benefit equal to your Cash Surrender Value (or the Guaranteed Minimum Cash Surrender Value, if that’s higher) — a distinction worth understanding if you’re weighing this against other options, since not every annuity structures its death benefit the same way.
Where this contract stands out is beneficiary flexibility. You can name multiple beneficiaries, and each one independently decides how to proceed after your death — receive their portion as a lump-sum death benefit payout, or continue their share of the contract forward as a new owner under the contract’s terms. That means a single contract can be split and carried forward across several family members rather than forcing one all-or-nothing outcome, which is a meaningfully different experience than what typically happens to an annuity at death under a more rigid, single-beneficiary structure. A death benefit paid this way is also tax-efficient for beneficiaries in a specific sense: because the underlying interest has already been taxed annually as it accrued, beneficiaries generally owe tax only on interest earned since the most recent tax filing — not on years of deferred, untaxed growth all at once.
Optional Riders: Free Partial Surrender and Enhanced Death Benefit
Two optional riders can be elected at the time of purchase. Electing either one reduces your guaranteed fixed interest rate somewhat — ask us for the current rate sheet to see the exact trade-off for your state and guarantee period.
The Free Partial Surrender Rider lets you withdraw, each contract year, up to an amount equal to your Accumulation Value at the start of that year multiplied by your guaranteed fixed interest rate — in effect, your annual interest-earnings potential — without triggering any surrender charge or MVA (including forfeiting a positive MVA you’d otherwise be entitled to). It’s a meaningful option if you expect to want access to your interest income periodically rather than letting it fully compound and lock away for the whole guarantee period.
The Enhanced Death Benefit Rider changes what your beneficiaries receive at death from the Cash Surrender Value (which can be reduced by surrender charges and a negative MVA) to the full Accumulation Value, with any surrender charges and MVA waived entirely on that death benefit payout. Electing this rider also automatically bundles in, at no additional rate reduction, a Nursing Home Rider and a Terminal Illness Rider. Those two riders waive surrender charges and MVA if you’re confined to a nursing home for at least 90 consecutive days (or a total of 90 days with no more than a 6-month gap between related confinements), or if you’re diagnosed as terminally ill and not expected to live more than 12 months, provided a qualified physician documents it. Neither of these riders is long-term care insurance or a substitute for it — they simply waive the exit costs on your own contract if one of those events happens to you.
Renewal Options at the End of Your Guarantee Period
At the end of your Interest Guarantee Period, you’re notified at least 15 days in advance and given a choice between three paths: renew into a new guarantee period of the same length at a new fixed rate (the default if you don’t actively choose), renew into a different available guarantee period length at its own new fixed rate, or roll into a daily fixed-rate account with no surrender charges or MVA at all (the default after your second or any later renewal, if you again make no election). Whichever you choose, the first 30 days of any new Interest Guarantee Period carry no surrender charge and no MVA — giving you a genuine window to move funds elsewhere penalty-free if a better opportunity has come along, including via a 1035 exchange into another annuity without triggering a taxable event on any gain that hasn’t already been recognized.
Who Stands Behind the Contract: Revol One Insurance Company
Revol One Insurance Company does business under the marketing name Revol One Financial, is domiciled in Michigan, and maintains administrative offices in Urbandale, Iowa. The company holds insurance licenses across most of the country but is not currently authorized to conduct business in New York, and the BreakThrough Annuity Account MYGA is separately not currently available in California. As detailed in the disclosure box above, AM Best has assigned the company a Financial Strength Rating of B++ (Good) and a Long-Term Issuer Credit Rating of “bbb” (Good), with a positive rating outlook — meaning AM Best’s own assessment is that the trend in the company’s underlying fundamentals is favorable, even though the current rating sits below the A- threshold some buyers require.
Where the BreakThrough Annuity Account Fits — and Where It Doesn’t
This contract tends to make the most sense for someone who has after-tax, non-qualified money sitting in CDs or a similar guaranteed-rate vehicle, wants a generally higher guaranteed fixed rate than typical CD offerings, is comfortable paying tax annually on interest as it’s earned rather than deferring it, and values the possibility of penalty-free access to gains before age 59½ enough to accept that the tax treatment behind that access is the carrier’s own interpretation rather than an IRS-confirmed ruling.
It tends to make less sense for retirement-specific dollars where tax deferral is the primary goal, for anyone who wants the simplicity of FDIC/NCUA-insured principal above all else, or for buyers who require a carrier rated A- or higher by AM Best. If any of those describe your situation better, we can walk you through how to think through which annuity actually fits your goals — including options from higher-rated carriers that may be a better structural or ratings match.
Financial Protection Essentials
Explore retirement income planning, savings longevity, and the broader coverage decisions that pair with this contract.
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
Is the BreakThrough Annuity Account actually an annuity?
Yes. It’s a Multi-Year Guarantee Annuity issued by a licensed insurance company, meaning your interest rate is guaranteed for a set period and your principal is protected when the contract is held for that full period. Where it differs from other multi-year guarantee annuities isn’t what it is, but how its taxation is structured — which is where its flexibility comes from.
Why doesn’t this annuity trigger the IRS 10% early withdrawal penalty before age 59½?
Because it’s structured to tax interest annually as it’s earned rather than deferring it, the carrier’s position is that the contract falls outside the tax structure that the IRS penalty is tied to. Importantly, there is no IRS private letter ruling confirming this — it’s the carrier’s own current interpretation of the tax code, not a settled ruling. Talk to a qualified tax professional about how this compares to how other retirement and non-qualified accounts are taxed before relying on this feature.
How is this different from a typical tax-deferred annuity?
Most non-qualified annuities defer taxes on growth entirely until you withdraw money. The BreakThrough Annuity Account does not offer that deferral — interest is taxed annually as it’s credited, the same way CD interest is taxed. In exchange for giving up deferral, you generally avoid the early withdrawal penalty issue that comes bundled with it. If tax deferral itself is your primary goal, other tax-deferred annuity strategies may be a better structural fit.
Can my beneficiaries continue the contract instead of cashing it out?
Yes. You can name multiple beneficiaries, and each one independently decides what to do after your death — take their portion as a death benefit payout, or continue their share of the contract as a new owner under its terms. This lets a single contract be divided and carried forward across several beneficiaries rather than forcing one outcome for everyone. It’s a good reason to revisit your designations periodically using something like our annual beneficiary review checklist.
Can I still lose money or face charges on this contract?
Your principal is protected for the length of your Interest Guarantee Period if the contract is held to term, and in no case can your Cash Surrender Value fall below the Guaranteed Minimum Cash Surrender Value required by state nonforfeiture law. That said, surrendering early or withdrawing beyond the free amount can trigger a surrender charge and a market value adjustment, which is a different question from whether you can lose money in an annuity more broadly. The optional Free Partial Surrender Rider can eliminate that risk for a limited annual withdrawal amount.
Why would someone choose this over a traditional non-qualified annuity?
It tends to fit people who want access to their money before age 59½ without the IRS early withdrawal penalty, who’d rather pay tax annually and predictably than face a large deferred tax bill later, and who want more flexible options for how the contract passes to beneficiaries. If your priority is maximum long-term tax deferral instead, a more traditional multi-year guaranteed annuity built for retirement dollars may fit better.
Can this contract provide guaranteed income later on?
Yes. Through annuitization, you can convert your Cash Surrender Value into a guaranteed stream of income payments under several payout options, including lifetime income with a period-certain guarantee. It’s not the contract’s primary purpose, but the option is built in at no separate cost, which is worth knowing if your plans shift toward needing guaranteed lifetime income down the road.
What if I only want to commit my money for a short time?
Guarantee periods start at 3 years, which is on the shorter end for a MYGA, and you’re not locked into renewing for a longer term afterward — you can choose a new short period, a different length, or roll into a no-surrender-charge daily rate account at each renewal point. If a short commitment matters most to you, it’s worth comparing this against other short-term MYGA options as well.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Annuity Options: Browse our complete guide to What Is a Fixed Annuity? — covering fixed annuities, MYGAs, laddering strategies & conservative growth options from 100+ carriers.
Last Reviewed: September 26, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
