
One America AssetCare and AnnuityCare Hybrid Long Term Care Insurance
As an Independent Long Term Care Insurance Broker, we compare traditional, hybrid, and partnership-qualified policies across dozens of carriers to find the structure that actually fits your situation.
As an Independent Annuity Broker, we compare rates across 100+ carriers and 1,000 different annuities— not just one company’s product offerings — to find the best fit for your goals.
One America AssetCare and AnnuityCare Hybrid Long Term Care Insurance
Most hybrid long-term care policies cap their benefits at a set number of years. OneAmerica is one of the few carriers that can extend long-term care benefits for the rest of your life, on both its life insurance-based Asset Care and its annuity-based Annuity Care, through an optional Continuation of Benefits rider. For a family worried about the long-duration claims that do the most financial damage, most often extended cognitive decline, that lifetime option changes the planning math entirely. Everything else on this page, from the tax treatment of Annuity Care to the guarantees inside Asset Care, sits on top of that one feature.
Jason Stolz, CLTC, CRPC, DIA, CAA, is Chief Underwriter at Diversified Insurance Brokers, and OneAmerica’s Care Solutions products, Asset Care and Annuity Care, are ones our office places regularly for clients who want to turn an existing asset into long-term care protection without giving up a legacy for their family. As an independent long-term care insurance broker representing OneAmerica alongside more than one hundred other carriers, our office can show you exactly how these two products compare with each other and with the rest of the hybrid and traditional market, and help you decide whether either one is the strongest fit for your situation.
Wondering whether Asset Care or Annuity Care fits your savings and your goals?
Request Your LTC Quote
Asset Care and Annuity Care at a Glance
| Feature | Asset Care | Annuity Care |
|---|---|---|
| Base Product | Whole life insurance with long-term care riders; see our guide to understanding hybrid long-term care insurance | Deferred annuity with long-term care benefits, in fixed (Annuity Care, Annuity Care II) and indexed (Indexed Annuity Care) versions |
| Where Care Dollars Come From First | Up to 100% of the death benefit is accelerated for care, paid monthly over a two-year or three-year period | The annuity’s own long-term care value is used for care first |
| How Long Benefits Can Last | Benefit period options up to lifetime with the Continuation of Benefits rider | From 24 months up to lifetime with the Continuation of Benefits rider |
| How You Fund It | Single premium, recurring premiums, or annuity-funded designs; often from CDs, savings, money market funds, life insurance cash values, or retirement accounts | A single premium, often from a tax-free 1035 exchange of an existing annuity |
| Covering a Spouse | Single or joint coverage; compare shared spousal LTC benefits | Joint ownership or naming a spouse as an Eligible Person |
| Underwriting | Medical underwriting for long-term care | Simplified underwriting with no invasive medical exams |
| Key Guarantees | Premiums cannot increase once issued; long-term care benefits never decrease; guaranteed cash value growth; Continuation of Benefits rider is noncancelable | Continuation of Benefits premiums are noncancelable and will never increase |
| If Care Is Never Needed | Death benefit to beneficiaries; return of premium available with a single-premium policy and rider | Annuity value passes to beneficiaries |
| Issuer | The State Life Insurance Company, Indianapolis, Indiana | The State Life Insurance Company, Indianapolis, Indiana |
Two Products, One Care Solutions Suite
OneAmerica Financial markets its asset-based long-term care products under the name Care Solutions, and they are issued by The State Life Insurance Company, a OneAmerica Financial company based in Indianapolis. The suite starts from a simple idea: many people already have money set aside that they think of as their “just in case” fund, whether it sits in a savings account, a certificate of deposit, a life insurance policy, or an old annuity. Care Solutions products put that money to work as long-term care protection while keeping it available as a legacy if care is never needed. You can read OneAmerica’s own overview on its long-term care protection page.
Asset Care and Annuity Care approach that idea from two different directions. Asset Care is built on whole life insurance. Your premium buys a death benefit, and long-term care riders allow that death benefit to be paid out for care while you are living, with an optional rider that continues benefits after the death benefit has been used. Annuity Care is built on a deferred annuity. Your premium becomes an annuity account that earns interest, and long-term care provisions allow that account to be withdrawn for care, again with an optional rider that continues benefits once the annuity’s care value is exhausted.
Which one fits depends largely on where your money is today and what you want it to do. Someone repositioning savings or income into a guaranteed care and legacy plan will usually look first at Asset Care. Someone holding an existing annuity with years of untaxed growth will often look first at Annuity Care, for reasons covered in the tax section below. It is often worth illustrating both for the same client, because the better fit is not always the one a client expects.
Both products share the same core promise that defines the hybrid category: the money does something useful no matter how life unfolds. If you need care, it pays for care. If you never do, it passes to your family. And both are designed with guarantees that remove the risk of future premium increases on the coverage you buy, which is the single biggest difference between hybrid designs and traditional long-term care insurance.
Asset Care: Whole Life Insurance That Pays for Care
Asset Care is a whole life insurance policy with an accelerated death benefit for qualifying long-term care expenses. OneAmerica describes it plainly as “your asset,” and that framing is useful. The policy has guaranteed cash value growth, a death benefit that passes to your beneficiaries if it is not used for care, and long-term care riders that let up to 100% of the death benefit be paid out for qualifying care while you are living. Once the policy is issued, OneAmerica cannot increase the premium for that coverage, and the long-term care benefits never decrease.
The long-term care benefit works in stages. First, the death benefit is accelerated for qualifying care, paid monthly as a percentage of the death benefit that depends on the acceleration period you choose. A shorter acceleration period pays a larger monthly amount over fewer months, while a longer one pays a smaller monthly amount over more months. OneAmerica has long offered a two-year acceleration option and has added a three-year option for both individual and joint policies, noting that it adds flexibility in coverage design and legacy planning and may allow a death benefit that equals or exceeds the premiums paid. Our guide to how accelerated death benefit riders work explains the acceleration concept.
Once the base policy’s long-term care benefits have been reduced to zero, the optional Continuation of Benefits rider takes over, continuing benefits for the period you selected, up to and including your lifetime. The rider must be added when you apply, for an additional premium. It is noncancelable, its premiums cannot increase, and only the policyholder can terminate it. It may not be available in every state. That second stage is where the long-duration protection comes from, and choosing its length is one of the most important decisions in the design, because it determines whether the policy covers a typical claim or protects against the rare but devastating claim that lasts many years.
Asset Care also offers single or joint protection, so one policy can cover you and a spouse or other loved one, and an optional inflation protection rider to help offset the rising cost of care over time, covered in more detail in the inflation section below. For couples, joint coverage is often the most efficient way to protect both spouses under one set of guarantees.
OneAmerica has also focused Asset Care on how care actually happens at home. It added and enhanced benefits for informal caregivers, independent providers, and in-home care, and it offers flexibility for a cash benefit that can be used to meet informal care needs. The cash indemnity benefit is not available on the acceleration of benefits portion of the policy in California. Our overview of what in-home care services include shows why that flexibility matters for families who want to keep care close to home.
Ways to Fund Asset Care
Asset Care has been built in several versions over the years, and they differ mainly in how the premium gets paid. The simplest is a single-premium policy, funded with one deposit. A single-premium version with a return of premium rider adds the ability to get your premium back if you surrender the policy, less any prior distributions, which is the only way to add a return of premium feature to Asset Care. Recurring-premium versions let you pay over a set number of years or over a longer period, annually or on a monthly, quarterly, or semiannual schedule, for buyers who would rather fund coverage from income than commit a lump sum.
For money held in retirement accounts, OneAmerica offers an annuity-funded approach, which it calls Annuity Funding Whole Life. Instead of paying the whole life premium directly, you fund an annuity, and an income rider on that annuity pays the Asset Care premium over time. Current income rider options run 5, 10, or 20 years, which lets the funding schedule match how quickly you want the money moved. Because this approach has historically been designed for buyers at or past age 59½, it is typically used by people in or near retirement who have savings in a 401(k), 403(b), or IRA that they do not expect to need for income. Our overview of using qualified funds for LTC insurance covers the tax considerations, which deserve careful review before any retirement money is moved.
Issue ages vary by version and design. OneAmerica has generally issued Asset Care up to age 80, with the annuity-funded versions starting at 59½, but the exact ages available depend on the version, the premium schedule, and your state, so our office confirms them for each illustration rather than assuming.
Where the Money for Asset Care Usually Comes From
Asset Care is rarely funded with money a client is counting on for growth. OneAmerica positions it for the conservative part of a portfolio, the dollars held for safety rather than returns, and the most common funding sources reflect that: certificates of deposit, money market funds, savings accounts, and the cash value in existing life insurance policies. These are the dollars many people already think of as their emergency or “just in case” fund, and in many cases the emergency they are quietly saving for is a future care need.
Repositioning that money into Asset Care changes what it can do. Sitting in a savings account, a dollar pays for one dollar of care. Inside Asset Care, the same dollar buys a death benefit that can be accelerated for care, and with the Continuation of Benefits rider, care benefits can extend well beyond the death benefit itself, up to lifetime. If care is never needed, the death benefit passes to heirs, and the policy’s guaranteed cash value remains available in the meantime.
Existing life insurance deserves special attention. An older policy that was bought to protect a young family may no longer be needed for that purpose, but its cash value can often be moved into Asset Care through a tax-free 1035 exchange, converting a policy that only pays at death into one that can also pay for care. As with any exchange, the existing policy’s surrender charges, guarantees, and death benefit should be weighed carefully first, and Jason reviews the existing policy alongside the Asset Care illustration before recommending any change.
Lifetime Benefits: The Feature That Sets OneAmerica Apart
Most long-term care coverage, hybrid or traditional, runs for a defined period. Nationwide’s CareMatters II tops out at eight years, as covered on our Nationwide CareMatters hybrid page and Securian Financial’s SecureCare. Among traditional policies, Thrivent long-term care insurance offers up to 96 months, and Mutual of Omaha MutualCare coverage is built around a multiplier or a pool of dollars with a defined limit. Those are all sound designs, and for many people a benefit of four to eight years is enough.
The problem is the claims that last longer. Long-duration care needs are most often driven by dementia and other forms of cognitive decline, where a person may be physically healthy for years while needing continual supervision. Those are exactly the claims that exhaust a fixed benefit and leave a family paying out of pocket for years afterward. OneAmerica’s Continuation of Benefits rider, available on both Asset Care and Annuity Care, can extend benefits for the rest of the insured’s life, which means the policy does not run out no matter how long care is needed.
A lifetime benefit costs more than a defined period, and it is not the right answer for everyone. For someone with substantial other assets, a six- or eight-year benefit plus personal savings may be the more efficient design. But for someone with a family history of Alzheimer’s disease, a strong desire to protect a spouse’s financial security, or simply a low tolerance for the risk of running out, the lifetime option is often the deciding factor. Our guide to long-term care insurance with lifetime benefits explains how lifetime coverage fits into a broader plan, and our comparison of hybrid life versus traditional LTC covers the wider trade-offs.
Want to see what lifetime long-term care benefits would cost for your age?
Price Lifetime Benefits
Annuity Care: Turning an Annuity Into Care Dollars
Annuity Care is a single-premium deferred annuity with long-term care benefits built in. It comes in fixed versions, Annuity Care and Annuity Care II, and an indexed version, Indexed Annuity Care. In each case, your premium becomes an annuity account that grows over time, and if you or a covered spouse need qualifying long-term care, money can be withdrawn from the annuity’s long-term care value to pay for it. Our overview of the non-qualified long-term care annuity covers the category in more depth.
The structure mirrors Asset Care in one important way. The annuity’s own long-term care value is used first, paid out over a set minimum period so that it lasts at least a defined number of months if the full monthly limit is used, and longer if care costs less. Once that value is exhausted, the optional Continuation of Benefits rider can keep benefits going for a chosen period, from as little as 24 months of total protection up to lifetime. The continuation rider’s premium is noncancelable and will never increase, and if you choose to pay it annually rather than as a single premium, it is waived while a covered person is receiving continuation benefits.
Annuity Care also keeps the flexibility of an annuity. After the first contract year, you can withdraw up to 10% of the account value each year without surrender charges. Larger withdrawals during the surrender charge period are subject to a surrender charge, and any withdrawal that is not used for long-term care reduces the long-term care value available later. If care is never needed, the annuity value passes to your beneficiaries. As with any annuity decision, comparing products across carriers matters, and working with an independent annuity broker gives you that comparison rather than a single company’s menu.
Indexed Annuity Care adds a different growth engine. Instead of relying only on a declared interest rate, part or all of the account can earn interest linked to the performance of a market index such as the S&P 500, subject to caps or participation rates that are declared each year and change over time, with guaranteed minimums. Because index-linked interest is never credited below zero, index declines do not reduce the account value. The long-term care benefit balance on Indexed Annuity Care is calculated from the account value and premium using factors that can increase the longer the contract is held, which rewards buyers who plan to keep the contract for many years before needing care.
The Pension Protection Act and the 1035 Exchange
This is where Annuity Care can do something few other planning tools can. Millions of retirees hold non-qualified deferred annuities they bought years ago and never touched. Many of those contracts have grown substantially, and the owners have no intention of taking income unless they need it for an emergency or for care. The problem is taxes. When gains come out of a traditional deferred annuity, they are taxed as ordinary income, and that extra income can also increase how much of your Social Security is taxed and push Medicare premiums higher through income-related surcharges.
The Pension Protection Act changed that picture for long-term care. Under its provisions, an existing non-qualified annuity can be exchanged into a PPA-compliant annuity with long-term care benefits, such as Annuity Care, through a tax-free 1035 exchange, and withdrawals used for qualified long-term care expenses are federal income-tax-free, regardless of how much gain the contract has built up. In other words, the same growth that would have been taxed if you withdrew it for any other reason can be used for care without federal income tax. Our guides to the Pension Protection Act annuity and to how 1035 exchanges work cover the mechanics.
A 1035 exchange is not automatically the right move. Before exchanging, it is important to weigh any surrender charges on the existing annuity, any guaranteed benefits you would give up, the new contract’s own surrender period, and whether the long-term care benefit is actually worth more to you than the flexibility of the old contract. Withdrawals from Annuity Care that are not used for qualified long-term care are taxed under the normal annuity rules. Jason reviews the existing contract and the replacement side by side before any exchange is recommended, because the right answer depends on the details of both.
Underwriting: Simpler Than Most Long-Term Care Coverage
One of Annuity Care’s biggest advantages is how people qualify. OneAmerica describes its underwriting as simplified, with no invasive medical exams and more relaxed requirements than other types of long-term care insurance, and it offers higher issue ages than many other long-term care options. Through the electronic application, applicants who answer no to a short set of health questions can receive an instant decision, for premiums up to $1.5 million. That makes Annuity Care a realistic option for some people in their seventies and eighties, or with health histories, who would struggle to qualify for traditional coverage.
Simplified does not mean guaranteed. Applicants still answer health questions, and answers must be complete and accurate, because a misrepresentation discovered during the policy’s contestability period can put a future claim at risk. Asset Care is medically underwritten as well. The specific requirements for either product depend on age, the amount of coverage, and health history.
This is where an experienced underwriter matters. Jason reviews a client’s health history before any application is submitted, so the product and design you see are ones you are likely to be approved for, and so a client who would not qualify for Asset Care can be steered toward Annuity Care, or another carrier, before going through an unnecessary decline. For someone who has been declined for traditional coverage, an annuity-based option is often worth a look.
Covering a Spouse
Both products can protect a married couple, but they do it differently. Asset Care is available with single or joint coverage, so a couple can share one policy’s long-term care protection. Annuity Care can provide benefits to a spouse in two ways: if the annuity is jointly owned, the spouse is covered automatically, and the Eligible Person provision allows you to name your spouse to receive long-term care benefits from the contract even if the spouse is not an owner.
Joint coverage has an important practical effect. When one annuity or policy covers two people, both draw from the same benefit pool, and if both spouses need care at the same time, that pool is used up faster than it would be for one person. For couples, this is a strong argument for considering the Continuation of Benefits rider, especially the lifetime option, so that one spouse’s care does not leave the other without protection.
Couples also face a planning question that single buyers do not: what happens to the healthy spouse’s finances while the other is receiving care. Keeping enough outside income and savings for the healthy spouse is as important as the policy itself, and it is part of every couples review our office conducts.
What Happens If Care Is Never Needed
The most common objection to long-term care insurance is simple: “What if I pay for years and never use it?” Both OneAmerica products answer that objection directly. With Asset Care, if long-term care is never needed, the death benefit passes to your beneficiaries, generally income tax-free. If some long-term care benefits were used, the remaining death benefit passes to them instead. With a single-premium Asset Care policy that includes the return of premium rider, you also have the option of getting your premium back if you change your mind, which turns the policy into something much closer to a reversible decision than traditional coverage.
With Annuity Care, the annuity value itself is the legacy. If care is never needed, the remaining annuity value passes to your beneficiaries, and a surviving spouse who is the beneficiary can generally continue the contract. It is important to understand one distinction here: the long-term care value that the annuity builds up for care is available only for care. When the last covered person dies, what passes to beneficiaries is the annuity’s regular account value, not the enhanced long-term care value. The care value is a benefit for the living, and the account value is the legacy.
That combination is why these products appeal to people who have been reluctant to buy long-term care coverage for years. The money is not spent and gone. It is repositioned so that it does one of two useful things, pay for care or pass to family, and in either case it does not simply disappear the way a traditional premium does in a year when no claim is filed.
Repositioning Savings: Asset Care Versus Self-Funding
Many people who ask about long-term care insurance already have enough savings to pay for some care themselves, and their real question is whether they should buy anything at all. Self-funding has real advantages. You keep full control of the money, there is no underwriting, and if you never need care, nothing has been spent on premiums. The weakness is leverage. A dollar of savings pays for one dollar of care, and a long claim can consume savings intended for a spouse or for heirs.
Asset Care is designed to change that ratio. A single premium, often money that was sitting in a savings account or a certificate of deposit earmarked for emergencies, buys a death benefit that can be paid out for care, and the Continuation of Benefits rider can extend that care benefit far beyond the premium itself, up to lifetime. If care is never needed, the death benefit passes to your family. In effect, the same dollars that would have sat in savings are repositioned so that they multiply if care is needed and still transfer to heirs if it is not.
Whether that trade makes sense depends on how much of your savings you are comfortable committing, how important liquidity is to you, and how you feel about the risk of a long claim. Laying out three scenarios side by side, keeping the money in savings, funding Asset Care, and funding Annuity Care if an annuity is involved, and comparing the care benefit, the legacy, and the liquidity of each in the same view, is often what makes the decision clear.
How Care Benefits Can Be Used
OneAmerica’s Care Solutions products cover the full range of care settings, including informal care, home health care, adult day care, assisted living, and nursing home care. To qualify for benefits, the covered person must be certified by a licensed health care practitioner as chronically ill, meaning they need substantial help with at least two of the six activities of daily living (bathing, continence, dressing, eating, toileting, and transferring) for an expected period of at least 90 days, or require substantial supervision because of a severe cognitive impairment. Care must be provided under a plan of care prescribed by a licensed health care practitioner.
Annuity Care generally pays benefits as withdrawals for actual long-term care expenses, up to a monthly limit, which is the reimbursement model most traditional policies use. Asset Care offers additional flexibility for informal care through its cash benefit option, which can help when a family member, friend, or independent provider is doing much of the caregiving. As with any policy, the specific definitions, waiting periods, and exclusions are spelled out in the contract, and our office reviews them with you before you apply so that there are no surprises at claim time.
Benefits may be subject to a waiting or elimination period before they begin, and the details vary by product and state. Knowing how that period is counted, and planning to cover those early costs from other resources, is part of building a complete care plan.
Inflation Protection
A benefit that looks adequate today may fall short decades from now, when a claim is more likely. Both Asset Care and Annuity Care offer inflation protection as an option, and OneAmerica has expanded the inflation protection choices on Asset Care. On Annuity Care, compound inflation protection is available on the Continuation of Benefits coverage, increasing the remaining continuation balance and monthly limit each year.
The value of inflation protection depends heavily on age. For buyers in their fifties or early sixties, whose claim may be twenty or more years away, compound inflation can be the difference between a benefit that keeps pace with care costs and one that covers a shrinking share of them. For buyers in their late seventies or eighties, a larger starting benefit without inflation may be the more efficient choice. Illustrating the same premium with and without inflation protection is the clearest way to see the trade-off for your age.
The Care Benefit Concierge
Every Care Solutions product includes access to OneAmerica’s Care Benefit Concierge at no additional cost. When a policyholder needs long-term care, OneAmerica assigns a Concierge, based in its home office, to the claim. The Concierge helps complete the required forms, communicates with doctors and other care providers to gather the necessary information, answers questions, and offers support and guidance throughout the claims process. OneAmerica encourages families to contact it first when a care need arises, because the sooner the Concierge is involved, the sooner the claim can move forward.
For families facing a care event for the first time, that kind of hands-on help can be as valuable as the benefit itself. Coordinating paperwork and medical records is often the most stressful part of a claim, and having a dedicated person handle much of it lets a family focus on the person who needs care. OneAmerica notes that the Concierge service is a company practice and may change over time.
Jason and our office stay involved as well. Clients often call us first when a care need arises, and we help them understand what their policy provides and how to start the claim process with OneAmerica.
Tax Treatment
For Annuity Care, withdrawals used to pay for qualified long-term care expenses are federal income-tax-free under the Pension Protection Act, regardless of the gain in the contract. Withdrawals for other purposes are taxed under normal annuity rules, and withdrawals before age 59½ may be subject to an additional tax penalty. For Asset Care, long-term care benefits for qualified services are generally received income tax-free, and a death benefit paid to beneficiaries is generally income tax-free as well.
State tax treatment can differ from federal treatment, and individual circumstances vary, so the specifics should always be confirmed with a qualified tax professional. Our guide to the tax advantages of hybrid LTC policies explains how these rules generally apply.
The size of the tax advantage depends on the annuity you start with. An old annuity with a large gain, meaning a large difference between what was paid in and what it is worth today, benefits the most, because that gain would otherwise be taxed as ordinary income whenever it comes out. A contract with little gain has less to protect. That is why reviewing the existing contract’s cost basis and current value is the first step in any Annuity Care conversation, alongside its surrender charges and any guaranteed features that would be given up in an exchange.
Have an old annuity you have never touched? Find out whether it could fund care tax-free.
Review My Annuity
Financial Strength
Asset Care and Annuity Care are issued by The State Life Insurance Company, a OneAmerica Financial company. AM Best rates The State Life Insurance Company and its sister company, American United Life Insurance Company, A+ (Superior), and S&P Global Ratings rates both companies A+, each with a stable outlook, according to OneAmerica’s strength and ratings page. Ratings reflect the agencies’ opinions of claims-paying ability and can change, so our office confirms a carrier’s current ratings before finalizing a recommendation.
OneAmerica Financial operates as a mutual organization, focused on the interests of its policyholders rather than outside shareholders, and its companies have served policyholders for well over a century. State Life policyholders are members of the mutual holding company that owns State Life. For a product whose guarantees may need to hold for thirty years or more, that long history and mutual orientation are meaningful.
OneAmerica continues to refine the Care Solutions suite, including adding a three-year acceleration option to Asset Care and expanding the ways qualified retirement money can fund it. A carrier that keeps investing in a product line is a better long-term partner than one that has stopped paying attention to it.
How OneAmerica Compares With Other LTC Options
We have reviewed several long-term care products alongside these two, and a side-by-side view makes the differences clear. Each design has real strengths, and the right one depends on what you value most.
| Feature | OneAmerica Asset Care | OneAmerica Annuity Care | Nationwide CareMatters II |
|---|---|---|---|
| Base Product | Whole life insurance | Fixed or indexed deferred annuity | Universal life insurance |
| Longest Benefit Available | Lifetime, with continuation rider | Lifetime, with continuation rider | Up to 8 years |
| Best Funding Source | Savings, income, or qualified money | An existing annuity via 1035 exchange | Savings or income |
| Underwriting | Medical underwriting | Simplified, no invasive exams | Underwritten; medical exam may be required |
| How Benefits Pay | Includes a cash benefit option for informal care | Withdrawals for actual care expenses | Cash indemnity, 100% of the monthly benefit |
| Premium Guarantee | Cannot increase once issued | Continuation rider premium never increases | Guaranteed never to increase |
| If Care Is Never Needed | Death benefit to beneficiaries | Annuity value to beneficiaries | Death benefit to beneficiaries |
Compared with traditional policies like Thrivent Long Term Care and Mutual of Omaha MutualCare, both OneAmerica products trade a higher up-front commitment for guarantees and a legacy if care is never needed. Compared with Nationwide CareMatters II, OneAmerica’s clearest advantages are the lifetime benefit option and, for Annuity Care, the ability to put an existing annuity’s untaxed gains to work for care through the Pension Protection Act. Nationwide’s clearest advantage is its cash indemnity design, which pays the full monthly benefit without receipts. Neither is universally better, which is why our office prices several options for nearly every client who asks about long-term care.
Two questions usually narrow the choice quickly. First, where is the money coming from? An existing annuity points toward Annuity Care, while savings or income can fit any of these designs. Second, how long do you want protection to last? If the answer is “no matter how long care is needed,” OneAmerica’s lifetime continuation option is one of the few ways to get there in a hybrid policy.
Questions Worth Asking Before You Apply
A few questions make the difference between a policy that fits and one that only looks good on an illustration. The first is where the premium is coming from, and what that money would otherwise be doing. Money already committed to an old annuity, a certificate of deposit, or a savings account earmarked for emergencies is usually the easiest to reposition, while money you may need for income or major purchases in the next several years is usually better left alone, because both products carry surrender charges or reduced values in their early years.
The second question is how long you want protection to last. A defined benefit period costs less, while lifetime continuation protects against the longest and most expensive claims. The third is who needs to be covered. A couple should decide whether one shared policy, two individual policies, or an annuity with an Eligible Person designation makes the most sense, and should think about what happens to the healthy spouse’s finances during the other spouse’s care.
The fourth question is how much inflation protection you need, which depends mostly on your age today. And the fifth is how comfortable you are with the trade-off between guarantees and leverage. Hybrid policies like Asset Care and Annuity Care offer guarantees and a legacy that traditional policies do not, while traditional policies often deliver more care benefit for each premium dollar. Jason walks through each of these questions with clients before any illustration is finalized, because the answers shape every other part of the design.
Important Information About These Products
Asset Care and Annuity Care are issued and underwritten by The State Life Insurance Company, Indianapolis, Indiana, a OneAmerica Financial company that offers the Care Solutions product suite. OneAmerica Financial is the marketing name for the companies of OneAmerica Financial. Products and features are not available in all states and may vary by state. All guarantees are backed by the claims-paying ability of the issuing company. These products are not a deposit, are not FDIC or NCUA insured, are not bank or credit union guaranteed, are not insured by any federal government agency, and may lose value.
Long-term care withdrawals and benefits reduce the policy’s or contract’s values, including the death benefit or annuity value available to beneficiaries. Annuity withdrawals above the penalty-free amount during the surrender charge period are subject to surrender charges. A policy may not cover all of the costs associated with long-term care. A 1035 exchange should be considered only after carefully weighing any surrender fees, costs, and benefits given up on the existing contract. This information is educational and is not tax, legal, or investment advice.
Who Fits OneAmerica, and Who Does Not
OneAmerica’s Care Solutions products tend to fit people who want long-term care protection that also protects a legacy. Asset Care is a strong match for buyers who want guaranteed premiums, guaranteed cash value, a death benefit for heirs, and the option of lifetime benefits, and who can qualify through medical underwriting. Annuity Care is a strong match for older buyers with an existing non-qualified annuity they are not using, for people whose health might make traditional underwriting difficult, and for anyone who wants long-term care benefits that are federal income-tax-free regardless of the gain in their annuity.
These products are a weaker fit for people who want the lowest possible premium for a given monthly benefit, where a traditional policy may deliver more coverage per dollar. They are also less suited to someone who needs the money in the near term, because surrender charges apply in the early years, and to someone who wants a pure cash benefit paid without receipts for every dollar, where a cash indemnity design like Nationwide’s may fit better. And because Annuity Care’s leverage depends on the annuity’s value, a smaller annuity will provide a smaller care benefit unless the continuation rider is added.
How We Help
Jason and our office help clients decide between Asset Care, Annuity Care, and the rest of the long-term care market from the first conversation. That starts with understanding where your money is today, reviewing your health history, and, if you own an existing annuity, reviewing that contract’s surrender charges, gains, and features before any exchange is considered. From there, we illustrate the designs that fit, including benefit periods, lifetime continuation, inflation protection, and joint coverage, and we compare them with other hybrid and traditional carriers.
Because we are independent, we are not obligated to recommend OneAmerica or any other carrier. If a different policy fits your health, your assets, or your goals better, that is the policy we will recommend. Our guide to why an independent LTC broker matters explains why that independence is especially valuable when two products from the same carrier work as differently as these do.
Ready to find out whether Asset Care or Annuity Care is the right fit for you?
Start My LTC Review
Financial Protection Essentials
Explore self-funding, annuity-based care options, and the estate planning decisions that pair with long-term care coverage.
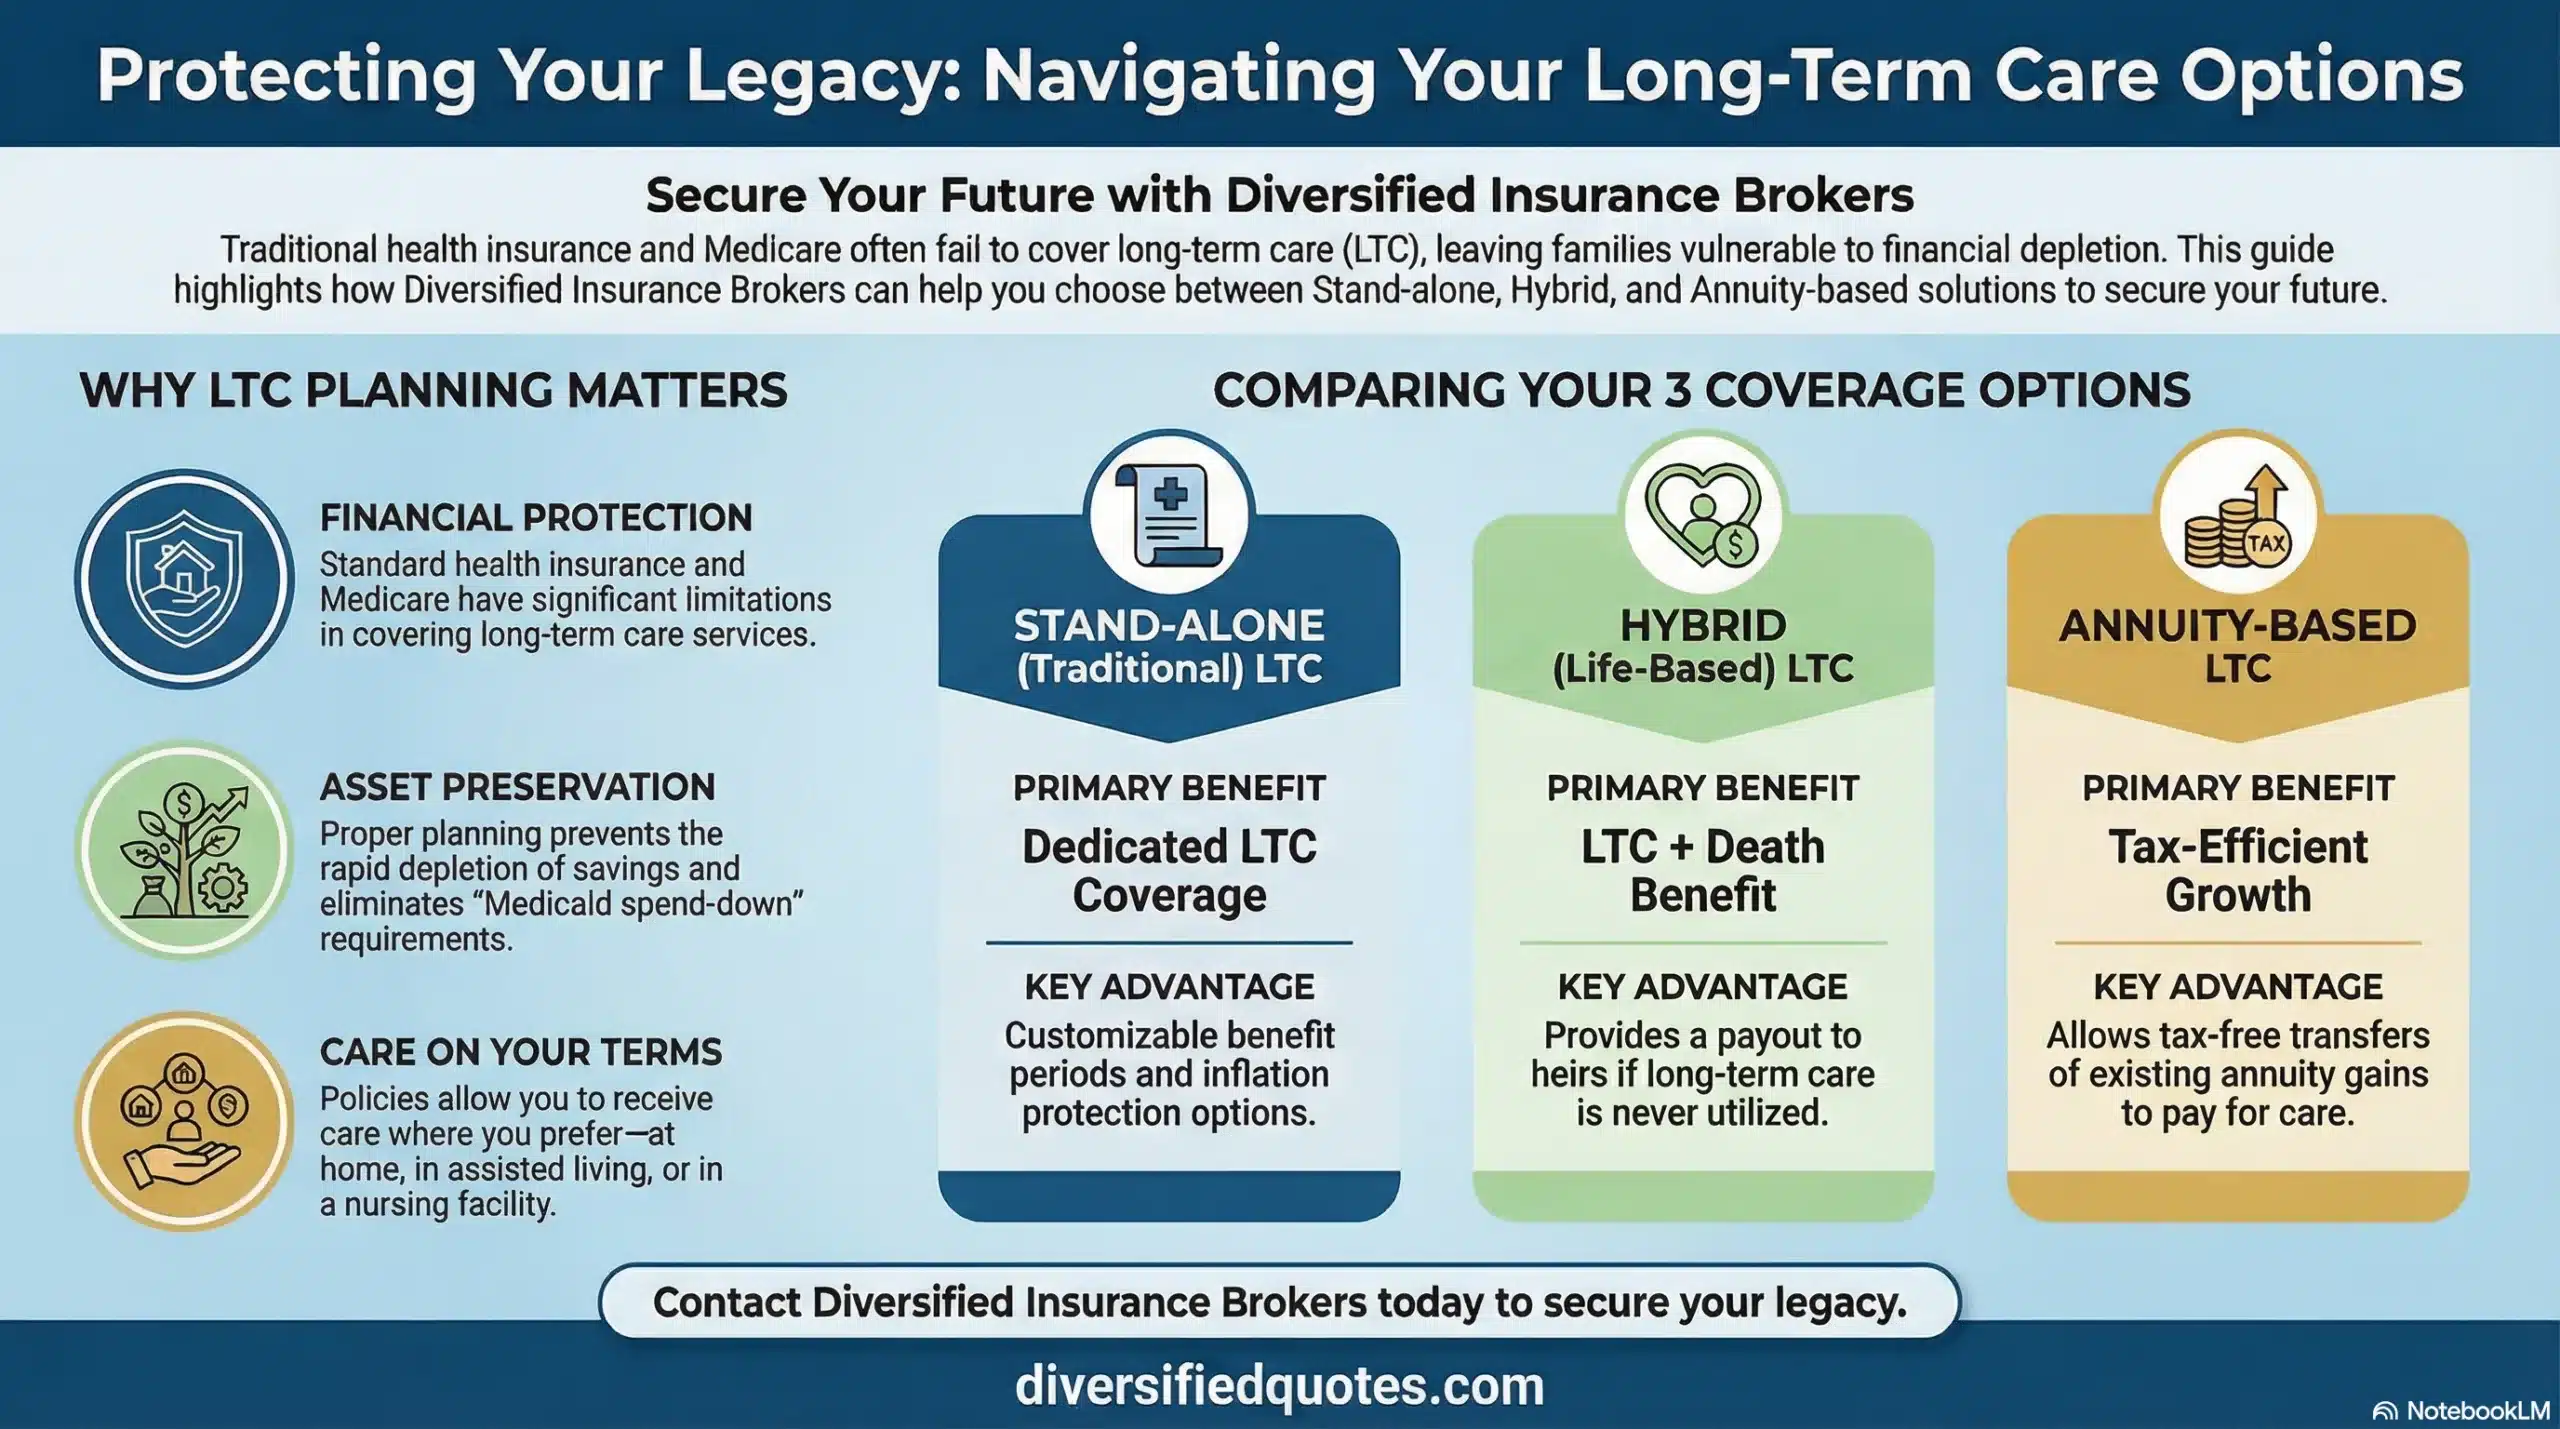
Talk to an Advisor or Request Your Annuity Quote
Ready to explore this annuity in more detail—or compare it with other carriers to see if even higher rates are available? With guaranteed income, principal protection, and long-term growth potential on the line, making the right choice is essential. The experienced advisors at Diversified Insurance Brokers will guide you through the options and design a strategy tailored to your retirement goals.
Schedule here:
calendly.com/jason-dibcompanies/diversified-quotes
Licensed in all 50 states • Fiduciary, family-owned since 1980
Frequently Asked Questions
What is the difference between Asset Care and Annuity Care?
Asset Care is whole life insurance with long-term care riders, so its death benefit is used for care first. Annuity Care is a deferred annuity with long-term care benefits, so the annuity’s own value is used for care first. Both can add a Continuation of Benefits rider that extends coverage up to lifetime. Our overview of hybrid long-term care insurance explains how these designs fit into the broader category.
Can I move my old annuity into Annuity Care without paying tax?
In many cases, yes. Under the Pension Protection Act, an existing non-qualified annuity can be exchanged into a PPA-compliant annuity with long-term care benefits through a tax-free 1035 exchange. Surrender charges on the existing contract and any benefits you would give up should be weighed first. See our guide to an annuity with long-term care benefits for more.
Are Annuity Care withdrawals for long-term care taxable?
Withdrawals used for qualified long-term care expenses are federal income-tax-free under the Pension Protection Act, regardless of the gain in the contract. Withdrawals for other purposes are taxed under normal annuity rules. State treatment can differ, so confirm your situation with a tax professional. Our overview of whether long-term care benefits are taxable covers the general rules.
Can these policies really pay benefits for life?
Yes, with the optional Continuation of Benefits rider, which is available on both Asset Care and Annuity Care for an additional cost. Without it, benefits last for the period funded by the death benefit or annuity value. Lifetime benefits are rare among hybrid policies, which is one of the main reasons clients consider OneAmerica. Our guide to how much long-term care insurance you need helps decide whether lifetime coverage is worth the added cost for you.
Is it hard to qualify for Annuity Care?
Annuity Care uses simplified underwriting with no invasive medical exams, and some applicants can receive an instant decision on the electronic application by answering no to a short set of health questions. Applicants still must answer accurately, and approval is not guaranteed. Our guide to LTC insurance with preexisting conditions explains how health history affects options.
Am I too old to buy one of these policies?
Not necessarily. OneAmerica describes Annuity Care as offering higher issue ages than other types of long-term care insurance, which makes it a realistic option for many people in their seventies and beyond. Asset Care’s availability depends on age, health, and the design selected. Our guide to long-term care insurance for seniors covers the options available at older ages.
Doesn’t Medicare pay for long-term care?
No. Medicare generally covers only temporary skilled care, not ongoing custodial care such as help with bathing, dressing, or supervision for dementia, which is what most long-term care consists of. Our guide to what Medicare covers for long-term care explains the gap that policies like these are designed to fill.
I already have a OneAmerica illustration. Can your office review it?
Yes. Our office can review the design you were shown, including the benefit period, continuation rider, inflation option, and funding source, and compare it with other hybrid and traditional carriers on the same benefits. You can request a second opinion on your LTC quote before you apply.
Can I use the cash value in an old life insurance policy to fund Asset Care?
Often, yes. Cash value in an existing life insurance policy is one of the most common funding sources for Asset Care, and it can frequently be moved through a tax-free 1035 exchange. The existing policy’s surrender charges, guarantees, and death benefit should be compared with the Asset Care illustration before making any change.
About the Author:
Jason Stolz, CLTC, CRPC, DIA, CAA and Chief Underwriter at Diversified Insurance Brokers (NPN 20471358), is a senior insurance and retirement professional with more than 25 years of real-world experience helping individuals, families, and business owners protect their income, assets, and long-term financial stability. As a long-time partner of the nationally licensed independent agency Diversified Insurance Brokers, Jason provides trusted guidance across multiple specialties—including fixed and indexed annuities, long-term care planning, personal and business disability insurance, life insurance solutions, Group Health, Travel Medical and Evacuation Insurance, and short-term health coverage. Diversified Insurance Brokers maintains active contracts with over 100 highly rated insurance carriers, ensuring clients have access to a broad and competitive marketplace.
His practical, education-first approach has earned recognition in publications such as VoyageATL, and contributions from his agency featured in Kiplinger and GoBankingRates— highlighting his commitment to financial clarity and client-focused planning. Drawing on deep product knowledge and years of hands-on field experience, Jason helps clients evaluate carriers, compare strategies, and build retirement and protection plans that are both secure and cost-efficient. Visitors who want to explore current annuity rates and compare options across multiple insurers can also use this annuity quote and comparison tool.
Explore More Long Term Care Insurance Options: Browse our complete guide to Hybrid & Annuity LTC Policies — covering hybrid life insurance, annuities with LTC benefits & linked benefit policies from top carriers.
Last Reviewed: September 30, 2026 |
Reviewed by: Jason Stolz, CLTC, CRPC, DIA, CAA
Chief Underwriter, Diversified Insurance Brokers, Inc. | NPN: 20471358 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Fact Checked by: Tonia Pettitt, CMIP©
Medicare Specialist, Diversified Insurance Brokers, Inc. | NPN: 14374308 | Diversified Insurance Brokers, Inc. — Licensed in all 50 states
Did you find this content helpful? Leave us a Google review — it helps others find trustworthy guidance too.
Editorial Standards: Diversified Insurance Brokers maintains rigorous editorial standards to ensure accuracy, clarity, and independence in all content. Learn more about our editorial standards and commitment to transparency.
